

 Posted By
By Kyle Prevost, Million Dollar Journey
Special to the Financial Independence Hub
One of the more interesting things I’ve learned from speaking with Canadians about retirement is that saving enough money is only half the battle. After spending 30 or 40 years accumulating investments, paying down mortgages, and generally trying to make responsible financial decisions, many people discover that actually spending their savings is more complicated than they expected.
After all, the financial rules that served you well during your working years don’t necessarily apply once the paycheques stop. Suddenly you’re juggling RRIF withdrawals, CPP and OAS decisions, investment income, tax brackets, and the possibility that your retirement could last another 30 years. Throw in the psychological adjustment of watching your investment accounts decline rather than grow, and it’s easy to see why retirement planning involves a lot more than reaching a magic number.
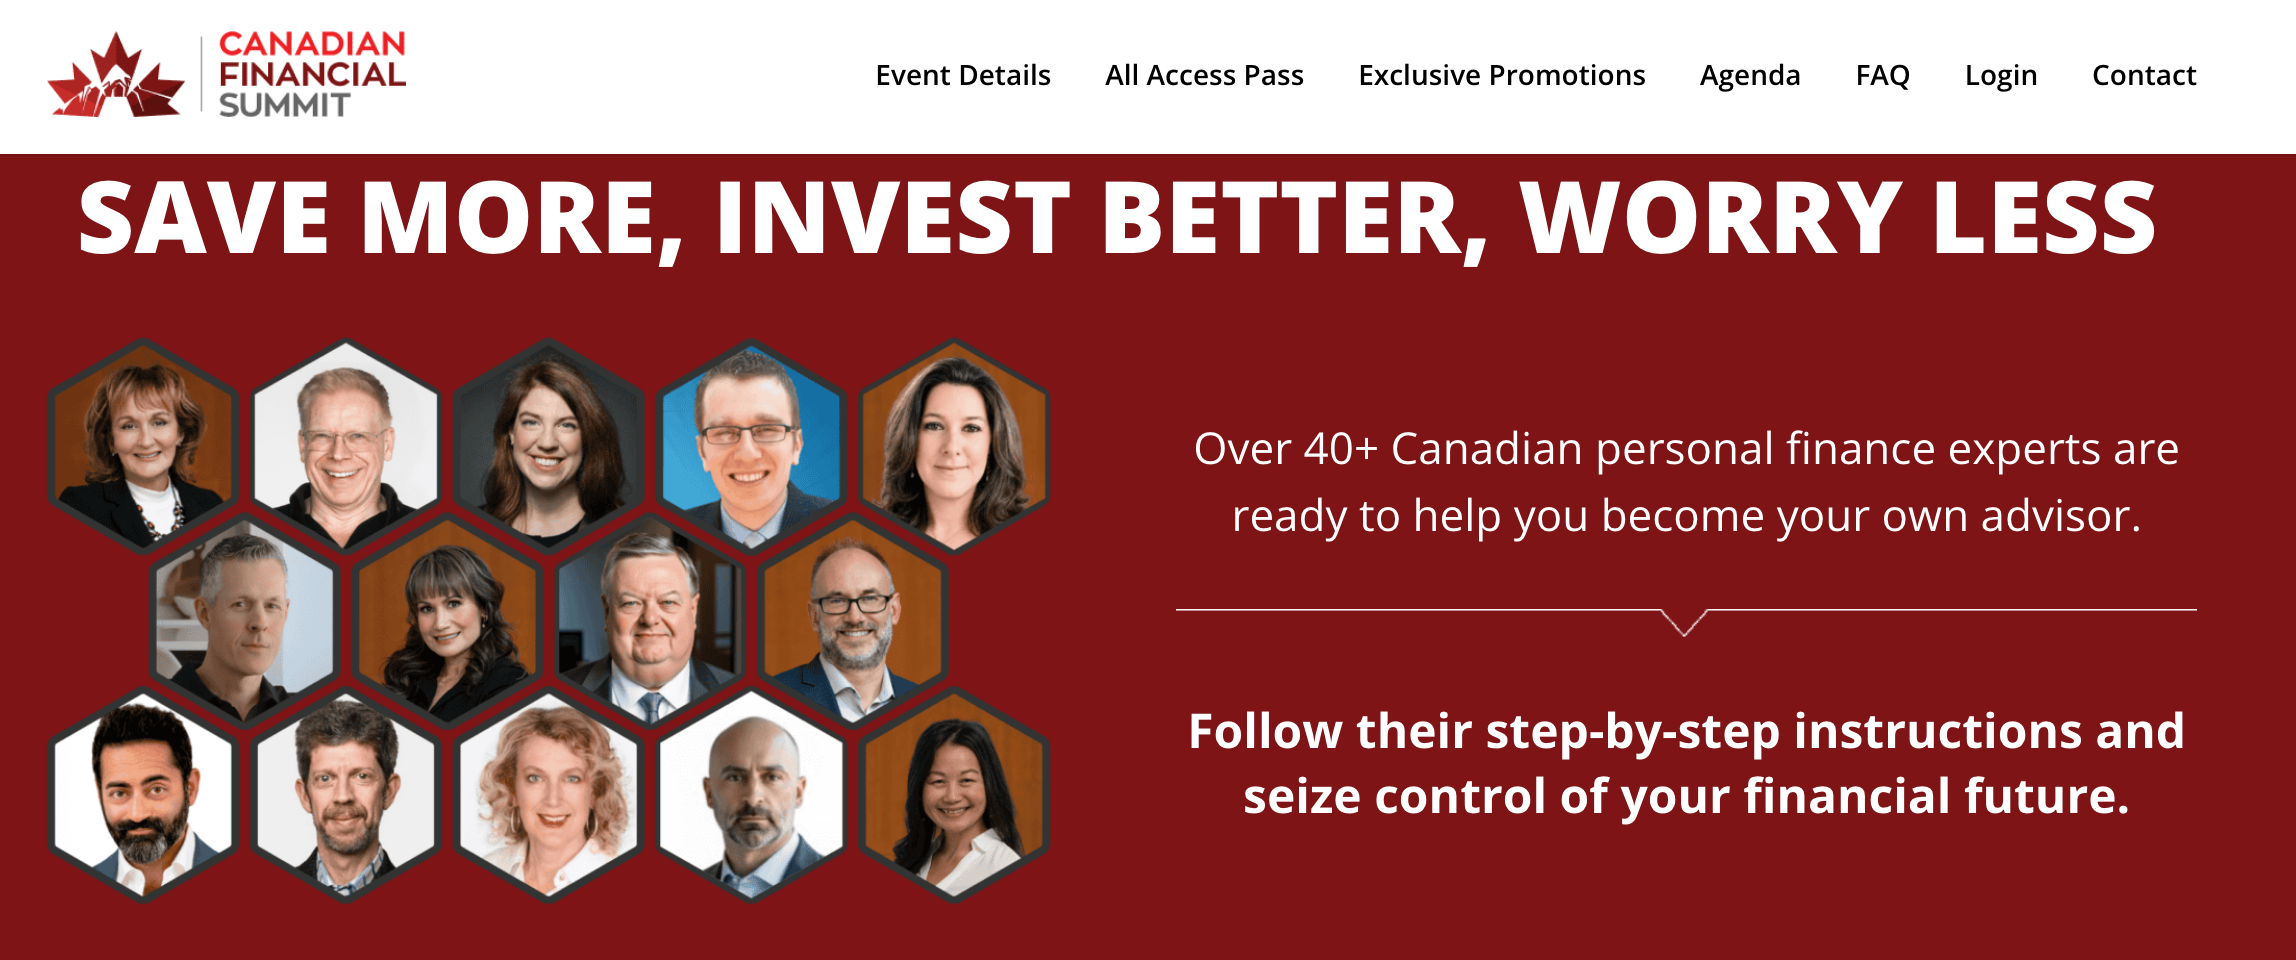
These are precisely the kinds of conversations I wanted to explore at this year’s Canadian Financial Summit, taking place online from October 21–24, 2026.
We’ve brought together more than 40 Canadian financial experts, with a particularly strong emphasis this year on retirement income, investment portfolios, tax efficiency, and making the transition from financial accumulation to financial independence.
The entire event is FREE to attend, with each presentation available to watch for 48 hours after its release.
Click here to reserve your free Canadian Financial Summit ticket.
What happens after you reach Financial Independence?
I was obviously pleased that Financial Independence Hub founder Jonathan Chevreau agreed to join us again this year. Jon has spent decades writing about financial independence, semi-retirement, pensions, investing, and the challenges of turning accumulated wealth into retirement income.
This year, however, we’re approaching the subject from a slightly different angle. Having made the transition from writing about retirement to experiencing it himself, Jon is sharing his perspective on what he got right, what surprised him, and what he might approach differently with the benefit of hindsight.
His session, From Retirement Columnist to Retiree: What I Got Right, Wrong, and Didn’t Expect, goes beyond the financial calculations to examine the actual experience of leaving employment behind. We’ll discuss the move from earning a paycheque to drawing on investments, the temptation to postpone spending, and why financial independence doesn’t automatically eliminate financial anxiety.
I suspect many readers here will find his observations especially interesting. After all, there aren’t many people who have spent as much time as Jon studying the theory of financial independence before testing it in their own lives.
Retirement Income & Taxes
Another major focus this year is what financial planners call decumulation: the process of converting your investments and other assets into money you can actually live on.
The challenge is that Canadians have several different sources of retirement income, each with its own tax treatment, withdrawal rules, and planning opportunities. Getting the sequence right can make a substantial difference over the course of retirement.
Here are some of the presentations I’m particularly looking forward to:
- Robb Engen: What retirement spending and taxes actually look like, including the confusion surrounding RRSP withholding taxes and how retirees establish a sustainable withdrawal routine.
- Nancy Grouni and Ed Rempel: Reducing lifetime retirement taxes, coordinating RRSP/RRIF withdrawals with CPP and OAS, and avoiding expensive tax surprises.
- Dale Roberts: Building a retirement cash flow plan that connects your investments, government pensions, tax brackets, and spending needs.
- James Gauthier: Adjusting your investment portfolio for retirement, with particular attention to sequence-of-returns risk and balancing growth with reliable income.
- Isabelle Bernier and Mike Heroux: Why Canadians who have saved diligently for decades sometimes struggle to spend their money, and how to balance financial security with actually enjoying retirement.
- Mark Seed and Kornel Szrejber: Firsthand perspectives on achieving financial independence, leaving traditional employment, and discovering what life looks like after reaching your savings goals.
We’ve also invited Jason Heath to explain how to evaluate the assumptions underlying professional financial plans, while Hannah McVean will demonstrate a step-by-step Canadian financial planning case study. Both sessions should be useful for anyone who wants to better understand the calculations behind their retirement projections.
Retirement Planning is about more than Investment Returns
One theme that runs through many of this year’s conversations is that the best retirement strategy isn’t necessarily the one that produces the highest possible net worth.
Consider a couple in their early 60s with a paid-off home, sizable RRSPs, and enough invested assets to comfortably support their lifestyle. Should they continue working to build a larger financial cushion? Begin drawing down their RRSPs before mandatory RRIF withdrawals begin? Delay CPP? Help their adult children with a down payment? Or spend more on travel while they’re young and healthy enough to enjoy it?
There isn’t one correct answer. The same investment portfolio can support very different retirement outcomes depending on tax planning, spending decisions, personal priorities, and how much financial uncertainty a household is comfortable accepting.
I’ll also be contributing a retirement-focused session of my own, examining what Canadians should do with rental properties as they approach retirement (aka “Rental Units Meltdown”). We’ll compare the financial implications of keeping rental real estate versus selling properties over time, including capital gains, depreciation recapture, and coordinating the proceeds with other retirement income.
Beyond retirement, the Summit includes sessions with Rob Carrick, Shannon Lee Simmons, Preet Banerjee, Ben Rabidoux, and Ron Butler, covering financial advice, investor behaviour, Canadian housing, mortgage rates, and the broader economy.
How to attend the Canadian Financial Summit for Free
The Canadian Financial Summit begins Wednesday, October 21, with the main presentations released October 22–24. Everything takes place online, and registered attendees will receive emails explaining how to access each day’s sessions.
Each presentation can be viewed free for 48 hours. There’s no credit card required to register, no subscription to cancel, and no need to download any special software.
We also offer an optional All Access Pass for those who would prefer lifetime access to the presentations, along with additional retirement-planning sessions and expert Q&As. However, there’s no requirement to purchase anything to enjoy the free event.
My hope is that whether you’re ten years away from retirement, already enjoying retirement, or simply looking to optimize your current financial situation, you’ll come away with a few practical ideas that you can apply to your own life.
 Register here for your FREE Canadian Financial Summit ticket, October 21–24.
Kyle Prevost is a Canadian personal finance writer, educator, and founder of the Canadian Financial Summit. He writes extensively about investing and retirement planning at MillionDollarJourney.com and is the creator of the 4 Steps to a Worry-Free Retirement course.
