By Dale Roberts, Retirement Club/cutthecrapinvesting
Special to Financial Independence Hub
It appears to be an overlooked part of retirement planning. While we should always invest within our risk tolerance level we should also match our investment portfolios to the retirement cash flow plan. The plan gives the marching orders for each account. If you create a portfolio-to-plan mismatch, you could increase the risk of depleting an account too soon. On the other side if you are too conservative where an account has the time horizon to run, you create opportunity cost. You missed the opportunity to create significantly more wealth over time.
As always the following is not advice.
We can look to the Canadian asset allocation ETFs for a lesson on risk and asset allocation. In that post that tracks the performance of the asset allocation ETF providers, you’ll find this key table.
Source: Dale/ETF providers. Keep in mind there is no guarantee of returns for any period
We can see that when our time horizon is short we create conservative portfolios with lots of bonds and cash. When we have a longer time horizon of 10 years and more, we can be more aggressive perhaps even holding an all-equity portfolio. But once again, risk tolerance permitting.
I recently discussed risk and common mistakes on the BMO ETF Insights YouTube channel.
In the accumulation stage we might pay attention to this chart if you are saving for a home and plan to buy within the next two years. If would be very risk to hold those home down payment funds in an all equity (XEQT-T) portfolio. Your $100,000 could quickly be turned into $50,000 in a severe bear market.
Sequence of returns risk in retirement
Risk gets flipped in retirement. In the accumulation stage if you have 20 years to go before retirement and we enter a severe bear market, “great”. You can now buy your companies/equities at fire-sale prices. Over time that can generate a boost to your wealth creation. You own more of those great companies. Continue Reading…
As we noted in a blog sent out on Canada Day, Findependence Hub registered users are invited to watch a special webinar on investing in AI stocks produced by TSInetwork.ca and The Successful Investor’s Pat Mckeough, a long-time contributor of blogs to the site.
The markets in 2025 were volatile, largely due to the implementation of U.S. tariffs. Despite this, investors who stayed the course were rewarded as markets finished the year on a stronger footing.
That said, a new challenge emerged in 2025 that carried into this year: Artificial Intelligence stocks.
Markets are once again volatile, and many investors are asking:
Should I invest in AI stocks? If so, which companies make sense? … OR
Is there a risk of an AI bubble that could impact the broader market?
In short: what should Successful Investors do?
In an exclusive webinar created by TSInetwork.ca and The Successful Investor, we’ll address these questions and more next Tuesday, July 7th, at 11:30 am EST.
This is a valuable opportunity for readers of Findependence Hub to hear insights based on Pat McKeough’s investment approach. As regular subscribers will know, Pat has been contributing guest blogs to Findependence Hub since its inception in 2014.
We’ll also leave plenty of time to answer your own questions about AI, current market conditions, and what to expect for the remainder of 2026.
As a thank you for attending, Canadian registrants are also eligible to receive a complimentary wealth management consultation with Bob Wiseman, a member of the Successful Investor Client Onboarding Team.
Please feel free to invite a family member or friend: just forward this blog by email and have them click the “Register Now” button above.
If you want a diversified large-cap Canadian equity fund with the added benefit of earning passive income beyond dividends, our new ETF may just be the one-ticket solution for you.
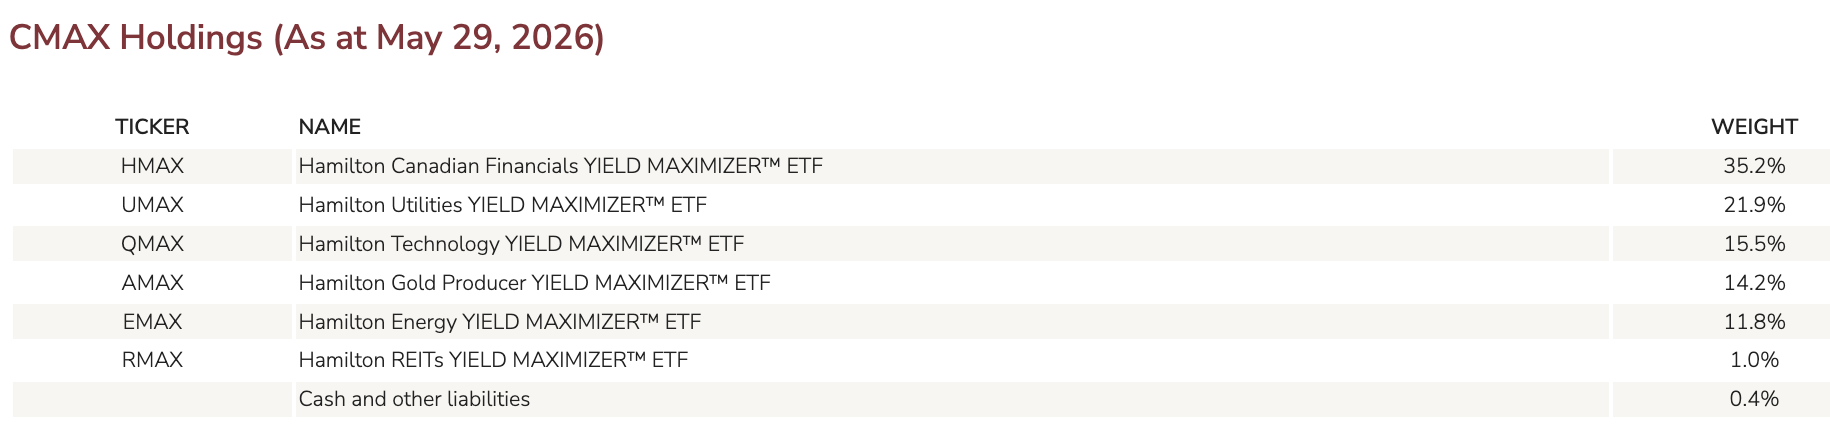
CMAX invests in six of our established sector-focused YIELD MAXIMIZER™ ETFs and is designed to broadly resemble the S&P/TSX 60 index in terms of sector weightings. Each of the underlying funds is managed by our experienced options team, which actively writes at-the-money options on the underlying stock holdings to generate income in the form of premiums.
The result is a diversified Canadian equity portfolio with a heavy focus on Canadian bank and insurance stocks, which have long been core holdings for many Canadian investors. CMAX also has meaningful exposure to utilities, telecoms and gold producer stocks, often considered defensive during periods of market volatility.
While CMAX closely reflects the Canadian large-cap stock market, it also holds select U.S. stocks through its underlying ETFs. Investors may ask why a Canadian-focused ETF includes U.S. equities rather than sticking strictly to Canadian names.
The answer is diversification. While CMAX is designed to provide a sector mix broadly similar to the S&P/TSX 60, it also makes what we believe are some important improvements. The Canadian technology sector, for example, is heavily concentrated, with Constellation Software, Shopify and Celestica representing roughly 75% of the sector[1].
Rather than replicate that concentration, CMAX gets its technology exposure through the Hamilton Technology YIELD MAXIMIZER™ ETF (QMAX). This addition provides exposure to a broader group of technology heavyweights like chipmakers NVIDIA, Intel, AMD and Micron, and the FAANGs, which add some prudent diversification, strength and quality to the portfolio.
More choice for income-seeking investors
With covered call ETFs like CMAX, investors can maintain their equity exposure while earning a higher tax-efficient yield to supplement other sources of income. It depends on your own unique financial position and needs, but if you want a balance of capital growth and income and don’t just want to focus on one sector, CMAX may be the right choice to add to your portfolio.
CMAX is part of our broader equity YIELD MAXIMIZER™ lineup, which also includes SMAX for U.S. equity exposure and IMAX for international equity exposure. Each ETF gives investors a simple way to choose the market exposure they want while accessing our active covered call strategy for monthly income. Continue Reading…
Retirement doesn’t always unfold the way you imagined, and that’s not necessarily a bad thing. While many people envision spending their later years with a long-term partner, life can take unexpected turns. Whether you’ve experienced a gray divorce or simply found yourself entering your golden years on your own, a solo retirement can feel like unfamiliar territory.
Create an Action Plan
Solo retirement has increasingly become a reality, with about 28% of Americans age 65 and older living alone. However, the good news is that retiring solo doesn’t mean sacrificing financial security or personal fulfillment. In fact, it can be an opportunity to refocus your priorities to reflect your unique needs. You just need to take actionable steps to adapt your financial plan to this new reality, which can help you gain peace of mind.
1. Revisit your Financial Numbers
The first step is updating your financial assumptions, as you might experience the extra costs of living alone or single’s tax, as it’s more commonly known. Many retirement plans are built around shared expenses and savings goals and the expectation that two people will contribute to household finances.
As such, start by reviewing your retirement budget and identifying what has changed. Consider expenses like housing, healthcare and insurance. Some costs may be lower when living alone, allowing you to reallocate funds to your top priorities.
This is also a good time to update your income projections and withdrawal strategy, as having an accurate picture of your finances can help you make thoughtful decisions about spending and future planning.
2. Adjust your Investment Strategy
A solo retirement can be an opportunity to take a fresh look at your investments and ensure they support the life you want to build. Rather than focusing solely on what has changed, consider how your portfolio can be adapted to provide both stability and continued growth throughout retirement. Review your asset allocation to ensure it aligns with your current needs and balances growth investments to protect against inflation.
At the same time, avoid making emotional investment decisions during major life transitions. For example, about 36% of adults getting divorced are aged 50 or older. This could lead to emotional investment decisions that later cause uncertainty and instability.
This may also be an ideal time to create or refine a comprehensive retirement income plan. Coordinating sources such as Social Security, pensions and investment withdrawals lets you build a predictable income stream that supports your lifestyle and reduces uncertainty.
3. Build a strong Support Network
One of the greatest advantages of planning for a solo retirement is the opportunity to intentionally create a network that supports both your financial well-being and your quality of life. While retirement planning often focuses on savings and investments, the relationships and resources around you can be just as valuable.
If you’ve experienced gray divorce, laying your grievances to rest can heal your family and make the path forward much simpler. Take time to strengthen connections with the people and communities that enrich your life, as family, friends and neighbors can play meaningful roles in helping you stay engaged and supported.
This is also a great time to organize your legal and financial documents. Review powers of attorney, healthcare directives, and beneficiary designations to ensure your wishes are documented and that trusted individuals are prepared to help. This planning brings peace of mind and confidence in retirement.
4. Rethink your Living Arrangements
An unexpected solo retirement can be the perfect opportunity to create a living situation that better supports the lifestyle you want in the years ahead. While housing is often one of the largest retirement expenses, it can also be one of the most flexible parts of your financial plan. Continue Reading…
Understanding how Exchange Traded Fund (ETF) liquidity works can help investors execute trades more efficiently, avoid common pitfalls and deliver better outcomes. Below, we debunk myths on true liquidity and share best practices:from spreads and execution timing to block trades and price deviations.
By Hilly Cutler, BMO Global Asset Management
(Sponsor Blog)
1.) What actually determines an ETF’s liquidity?
Image courtesy BMO ETFs
Contrary to popular belief, it’s not the number of shares you see on screen.
For ETFs, real liquidity comes from its underlying basket: the stocks, bonds, or commodities inside the ETF.
If the underlying securities are highly liquid, the ETF is typically highly liquid too, even if its on‑screen volume looks small.
2.) So if an ETF trades only a few thousand shares a day, is it illiquid?
No. That’s one of the biggest misconceptions.
Low trading volume only tells you how frequently investors trade it: not how liquid it is.
If the underlying securities trade millions or billions per day, market makers can easily create or redeem ETF units to facilitate any size trade.
Think of the ETF as a doorway to the underlying market: The doorway might look narrow (low volume), but the room behind it (underlying liquidity) could be huge.
3.) What’s the role of a market maker?
We’re responsible for:
Providing continuous two‑sided quotes (bid/ask).
Making sure spreads are fair relative to the underlying securities.
Stepping in to facilitate larger trades.
Creating or redeeming ETF units when supply/demand shifts.
Our job is to make liquid markets for ETFs and keep them trading smoothly, regardless of who’s buying or selling.
4.) Why do ETF spreads widen sometimes?
Spreads move mainly because the underlying market moves.
Common reasons spreads widen:
Opening minutes of the trading day.
Volatility spikes (macro events, economic data flow, central bank announcements).
Underlying markets closed (e.g., ETFs holding international stocks, or U.S. equity ETFs when their market is closed for a holiday and the Canadian market is open).
It’s rarely because “the ETF is broken”: it’s just reflecting what’s happening underneath.
5.) When is the best time of day to trade ETFs?
Generally:
We suggest avoiding trades in the first 10–15 minutes after the market open.
This allows enough time for the underlying securities in the fund to start trading.
We suggest avoiding trades in the last 10 minutes before the market close.
Underlying portfolio movement can be volatile at the end of the day.
Instead, trade during middle-of-the-day hours when underlying markets are fully open and spreads are tightest.
When the underlying market is closed, the underwriter will have to model the price, and will therefore set a slightly wider spread to reflect their increased risk on the trade.
If the ETF holds North American stocks, trade during full Canada and U.S. market hours.
If an ETF holds international stocks, since many European markets generally close around 11:00am (ET), best practice is to trade before then. It should be expected that bid-ask spreads will widen out once European markets close.
6.) Should investors use market or limit orders?
Always use limit orders. Market orders expose you to whatever price the next trade happens to hit: especially risky in thin markets or volatile times.
A limit order doesn’t mean you won’t get filled. It just means you control the price.
That said, if the investor is looking for an immediate fill on the buy, best to enter at the ask. If they are prepared to wait until their price is hit, they can enter a limit order priced at the mid-point of the bid-ask spread.
7.) What causes the ETF price to deviate from NAV?
The ETF often doesn’t “deviate” (or in other words, trade at a large discount or premium to its NAV): it’s actually showing the fair value of the underlying securities.
In Canada, ETF NAVs are calculated once per day, at market close. ETF prices, on the other hand, update every second.
If the ETF holds U.S., European or Asian securities, and those markets are closed, the ETF’s traded price will reflect new information (futures, ADRs, macro data) that the stale NAV cannot. Continue Reading…


 Posted By