All posts by Financial Independence Hub

Why does the Stock Market Rise when the News looks Bad?

Lowrie Financial: Custom Creation with Claude

By Steve Lowrie, CFA

Special to Financial Independence Hub

Short answer: stock prices reflect what investors expect to happen in the future, not what the headlines are reporting today. Markets rise when outcomes turn out better than investors feared, even if conditions still look bad.

By the time a story feels alarming enough to act on, the market has usually already priced it in. That’s why reacting to headlines rarely works, and why discipline tends to beat prediction.

Every market cycle seems to produce the same question. The headlines are negative. Investors are worried. Economists are warning about risks. Yet the stock market keeps climbing a wall of worry. How can both things be true?

It’s one of the most common investing questions I hear, and it usually sounds something like this:

“I don’t understand it. There’s a war in the Middle East. Governments are running massive deficits and have accumulated huge amounts of debt. Economists keep warning about recessions. Every day the news seems filled with uncertainty and risk. So why is the stock market near record highs?”

It’s a fair question, and if you’re asking it, you’re not alone. The answer comes down to one of the most important concepts in investing:

Markets Live in the Future

That may sound like a strange statement at first. After all, investors own businesses that operate in the real world today. Shouldn’t stock prices reflect what’s happening right now?

To a degree, they do. But the value of any business depends far more on the profits it’s expected to earn in the future than on the profits it earned last quarter. Every day, investors around the world are trying to answer the same question: what are those future profits worth today?

To answer it, they evaluate interest rates, inflation, economic growth, corporate earnings, government policy, geopolitical risks, and thousands of other pieces of information. As those expectations change, stock prices change. That’s why stock prices often seem disconnected from the headlines, and it’s where many investors get tripped up.

We naturally assume stock prices should move in response to what’s happening in the economy today. If growth slows, unemployment rises, or geopolitical tensions increase, it seems reasonable to expect stock prices to fall. But there’s an important distinction.

Most financial news and economic data tell us what has already happened. In many cases, that information is weeks or even months old by the time it’s reported. The stock market, on the other hand, is constantly trying to estimate what happens next.

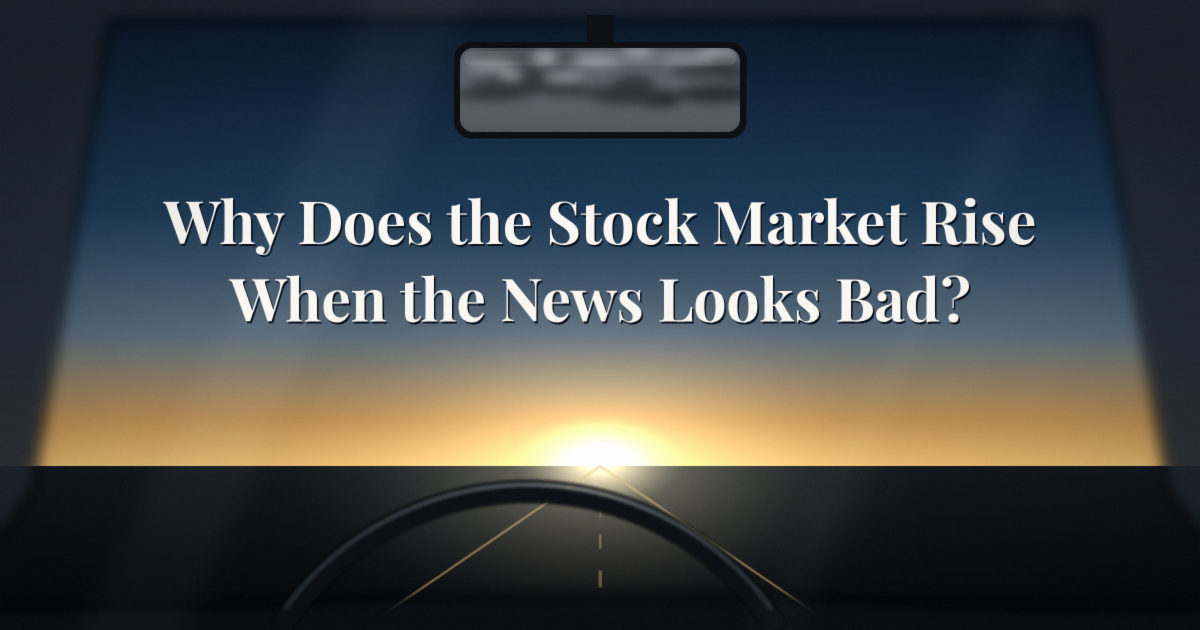
I often think of financial news and economic data as a rearview mirror. They help us understand where we’ve been.

The stock market is the windshield. Investors are looking ahead, trying to estimate what businesses, profits, interest rates, and economic conditions might look like in the future.

Once you understand that difference, it becomes much easier to see why headlines and market performance so often seem disconnected.

Why does the Stock Market Rise when the News Looks Bad?

One of the biggest misconceptions in investing is that markets move based on whether news is good or bad. In reality, markets tend to move based on whether outcomes are better or worse than expected. That may sound like a subtle distinction, but it’s an important one.

Imagine investors become convinced a severe recession is coming. Businesses prepare for it. Economists forecast it. Investors position their portfolios for it. If the economy ultimately experiences only a mild slowdown, stock prices may rise even though conditions look bad. The outcome wasn’t necessarily good; it was simply better than investors feared.

The opposite happens all the time too. A company can report record profits and still see its stock price fall, because investors expected even better results. Markets are constantly comparing reality against expectations.

That may sound abstract, but history gives us a powerful example. During the global financial crisis, stock markets reached their lowest point in March 2009. At the time, the news was still overwhelmingly negative. Unemployment continued rising. The economy remained weak. Many investors were convinced conditions would deteriorate further, yet the market began recovering.

Investors who waited for reassuring headlines missed a significant portion of that recovery, because the market wasn’t waiting for conditions to improve. It was already looking ahead to a future in which they eventually would.

Investors who wait for good news often discover that the stock market has moved higher long before the headlines improved.

That’s what I mean when I say markets live in the future.

What does “It’s Already Priced In” mean in Investing?

This idea also explains one of the most misunderstood phrases in investing. You’ll often hear investors say something is “already priced in.” What they mean is that the market has already incorporated known information into stock prices.

By the time most of us hear a major news story and start wondering what it means for our investments, millions of investors around the world have already evaluated that information and built their views into prices.

That doesn’t mean markets are always right. Far from it. Markets can be overly optimistic. They can be overly pessimistic. Prices can move too far in either direction. But current prices generally reflect the collective expectations of investors based on everything they know today. Put another way, they give the best available estimate of what a company is worth right now.

For prices to move significantly, something usually has to happen that differs from those expectations. That’s why major headlines often have less impact on markets than people expect. Investors aren’t reacting to the news itself. They’re reacting to whether the news is better or worse than anticipated.

Why is Market Timing so Difficult?

Once you understand how markets work, it becomes easier to see why market timing is so challenging. To successfully move in and out of the market, you have to do more than predict what will happen next. You also have to predict what millions of other investors expect to happen and then determine whether reality will turn out better or worse than those expectations. That’s an extraordinarily difficult task.

It’s one of the reasons decades of academic research have found that consistently outperforming the broad stock market is so difficult. Whenever someone tells me they believe the market has it completely wrong, I think it’s worth asking a simple question: who exactly are they betting against?

At any given moment, stock prices reflect the collective judgment of massive pension funds, sovereign wealth funds, hedge funds, insurance companies, analysts, economists, business leaders, professional investors, and millions of individual investors around the world. Could the market be wrong? Of course. But consistently identifying mispricing and systematically profiting from it before everyone else is remarkably difficult. Decades of evidence suggest very few investors do it successfully over long periods.

What is the Practical Lesson for Investors?

The practical lesson isn’t that markets are perfect. It’s that reacting to headlines is usually not a successful investment strategy. By the time a story feels important enough to make you want to change your portfolio, the market has often already processed that information and adjusted accordingly.

This is worth saying clearly, because it’s easy to take the idea too far. “It’s already priced in” is a reason to ignore the daily news cycle. It is not a reason to ignore your own plan. Rebalancing back to your target mix, adjusting your portfolio as your goals and time horizon change, and managing risk, taxes, and costs are all decisions driven by your circumstances, not by the headlines. Discipline doesn’t mean doing nothing. It means acting on your plan rather than on the news.

So this doesn’t mean investors should ignore the news. It means they should be careful about making investment decisions based on it. Successful investing is rarely about predicting the next headline. It’s about building a sensible portfolio, staying disciplined during periods of uncertainty, and focusing on your long-term plan rather than the daily news cycle.

The next time you find yourself wondering why the stock market is rising despite negative headlines, remember that investors aren’t just evaluating what’s happening today. They’re trying to estimate what happens next, and more often than not, the market begins looking ahead long before the rest of us do.

That’s why markets can reach new highs during periods that feel uncertain, uncomfortable, or even frightening. And it’s why some of the best investment decisions are often the ones that feel hardest in the moment: staying disciplined, ignoring the noise, and sticking to a well-thought-out plan when the future feels least certain.
Frequently Asked Questions Continue Reading…

When mega-IPOs meet index investing

Franklin Templeton ETFs

By Dina Ting, CFA, Franklin Templeton ETFs

(Sponsor Blog)

For decades, public markets were where companies grew up. Investors could watch young firms move from small-capitalization (cap) to mid-cap level and, for the rare few, into the ranks of the largest companies in the world. That journey today happens increasingly in private markets. We’re seeing now that by the time some companies list, they can seem to arrive already fully formed.

This shift is testing index construction. The impending listings from the likes of SpaceX, OpenAI and Anthropic have prompted index providers to revisit how quickly very large companies making initial public offerings (IPOs) should enter major benchmarks. Some index providers, including FTSE Russell and Nasdaq, have been racing to ensure benchmarks can capture the next generation of large public listings. Others, including S&P Dow Jones Indices, have preferred to keep established guardrails in place, maintaining a more deliberate approach to eligibility and inclusion.

In our view, this diversity of approaches is healthy. Index providers are trying to balance two important goals: reflecting the investable market as it evolves, while maintaining liquidity, stability and transparent rules. There is no single correct answer. A benchmark that moves too slowly may miss important changes in the economy. A benchmark that moves too quickly may expose investors to companies before trading history, float and fundamentals are well established.

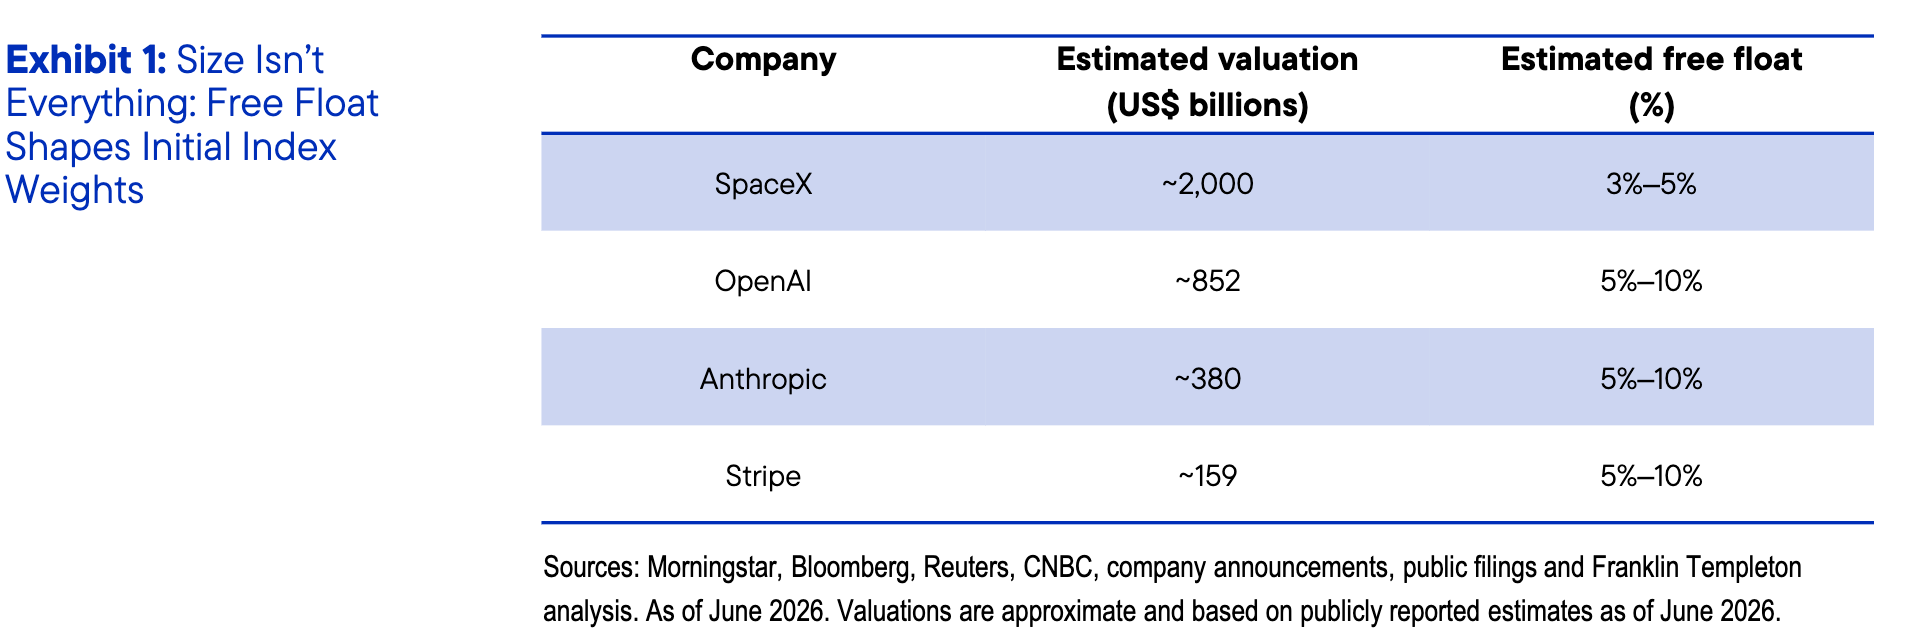
An overlooked aspect of benchmark construction is that headline valuations and index weights are not the same thing. Most major equity indexes rely on free-float-adjusted market capitalization, which means they consider the shares actually available for public trading. FTSE Russell’s own preliminary analysis of SpaceX assumed a total market capitalization of US$1.5 trillion but available market capitalization of about US$70 billion, producing estimated weights of only 0.11% in the Russell 1000 Index and 0.08% in the FTSE GEIS All-World Developed Index.1

A company may dominate headlines yet enter a broad index with a relatively modest initial footprint. Over time, lockup restrictions — which typically prevent founders, employees and early investors from selling shares immediately after an IPO — expire, allowing more shares to enter the public market and potentially increasing the company’s index weight.

Another question investors may not have considered is whether these listings automatically make indexes more growth oriented. At first glance, the answer might seem like a no-brainer. Many of these companies operate in areas such as artificial intelligence (AI), aerospace and cloud infrastructure. Yet index construction is often more nuanced than headlines suggest.

FTSE Russell’s treatment illustrates this. Fast-entry IPOs have generally inherited the style characteristics of their assigned subsector until company fundamentals become available. However, the index provider has also acknowledged that relying solely on industry averages could create what it calls “market misrepresentation,” leaving room for alternative treatment in certain cases. For SpaceX, FTSE’s preliminary classification pointed to telecommunications, where the subsector average was 18% growth and 82% value.2

That may surprise investors who instinctively view anything rocket-fueled as growth. But it is a useful reminder: Index investing is rules-based, not headline-based. Style indexes do not simply ask whether a company feels innovative. They evaluate characteristics such as valuation, earnings, growth metrics and industry classification. As more mature private-market companies list, some may challenge traditional style frameworks.

This is where broader portfolio implications emerge. Broad-market index ETFs remain efficient, tactical tools for gaining diversified equity exposure, and country or style ETFs can help investors express more targeted views. But indexes are not static. New companies enter, sector weights shift, float changes, classifications evolve and concentrations emerge. Index exposure is therefore not necessarily something investors should set and forget. Continue Reading…

Picking up Nickels in front of a Steamroller

Image Pixabay

By Michael J. Wiener

Special to Financial Independence Hub

Suppose a casino offered the following bet.  You roll six fair dice.  If anything but all sixes shows up, you get $20.  But if all sixes show up, you lose a million dollars.

There are a number of practical problems with this game.  The casino would demand a million-dollar deposit in advance, and the odds are way too sensitive to imperfections in the dice and to player skill at not throwing sixes.  But this is a thought experiment designed to shed light on real-world financial events.

Initially, few people would play this game, because losing a million dollars is too scary.  But if you watched someone playing, even all day, you’d likely never see a loss.  You’d just see the player collecting $20 every 10 seconds or so, building up to many thousands of dollars.  The fear of missing out (FOMO) would set in for some and tempt them to play.

Over the long haul, the casino expects to pay out $933,120 for every million dollars it wins.  So playing this game is good for the casino but a bad idea for the player.  However, it’s easy to forget about the losses if you only see everyone winning $20 every play.  Games like this are referred to as “picking up nickels in front of a steamroller.”  The $20 payoffs are the nickels, and the million-dollar losses are when you get flattened by the steamroller.

The yen carry trade

So what does this have to do with real life?  There are many “games” in real life that resemble this hypothetical game more than people would like to admit.  When interest rates were much lower in Japan than they were in the U.S., it seemed profitable to borrow yen at a low interest rate, convert it to U.S. dollars, and collect high interest on U.S. dollar deposits.

This sounds quite profitable, so why did I say it only “seemed profitable?”  Well, all was well as long as interest rates and the exchange rate between yen and U.S. dollars were stable.  However, a rise in the value of the yen and higher Japanese interest rates (the steamroller) could more than wipe out any profits from the interest rate spread (the nickels).

Unlike the hypothetical dice game where the potential loss of a million dollars is prominent, it’s less obvious with the yen carry trade.  You might convince yourself that the value of the yen and Japanese interest rates would change slowly enough that you could exit your positions profitably.  However, many others would be trying to unwind their positions at the same time, each one trying to be among the first to get out.

Excessive leverage

Rather than just invest a fraction of your wages in stock markets, you could borrow extra money to invest more.  The stock markets may gyrate, but they keep rising.  If you can just wait out the gyrations, you’ll be sure to eventually make more money (the nickels) than if you didn’t borrow.

The problem is that if you borrow too much, and your creditors see that you’re in danger of becoming insolvent, they may demand their money back or impose high interest rates that eliminate your profits.  A sudden stock market crash (steamroller) could wipe you out before you get a chance to wait out the market decline.  Modest leverage can be reasonable, but it takes some skill to determine how much you can borrow safely.

The great financial crisis

Many Wall Street firms made apparent profits selling insurance against mortgage defaults in the form of exotic financial instruments like credit default swaps (CDSs) and collateralized debt obligations (CDOs).  In this case, the nickels were the insurance premiums they collected, and the steamroller was the wave of mortgage defaults across the U.S. Continue Reading…

Should you Buy a Business instead of Starting one?

Photo by Amy Hirschi on Unsplash

By Devin Partida

Special to Financial Independence Hub

For entrepreneurs, the path to success often begins with the critical decision of whether to buy a business or start one from scratch. The right choice boils down to a few key preferences, such as the level of risk you’re willing to take and your long-term goal of achieving financial independence. Identifying these factors is key to understanding which option is ideal for you.

The Blank Canvas of a New Business

Building a business from the ground up is the ultimate exercise of creative control. You formulate the business model, create the brand identity and hire the team. For opportunistic professionals, this flexibility allows you to jump on market openings the moment you spot them. The level of operational and strategic autonomy you have when starting a business is far greater than when acquiring one.

However, that creative freedom does come with a unique set of risks. In fact, roughly 50% of new businesses fail within their first five years. This staggering statistic underscores the difficulty of building consistent cash flow and securing a customer base while simultaneously proving your business model.

More likely than not, starting a business means navigating years of financial losses before turning a meaningful profit. If you’re the founder, your personal finances are likely to absorb the initial shocks.

Buying a Business means acquiring Immediate Momentum

Taking over an established business is essentially an investment in momentum. You get instant access to existing cash flow, a customer base and a working business model. The costly trial-and-error phase is completely mitigated, and you have the privilege of building off the previous owners’ inertia.

Yet, acquiring an established business often comes at a considerable cost. Acquisitions require significant seller financing or up-front capital, which often entails complex bank loan arrangements. While it is the less risky option, the initial investment will likely be more costly than building a new business on your own terms.

Additionally, buyers risk inheriting unseen liabilities or a toxic workplace culture. When you buy an existing business, you’re simultaneously purchasing someone else’s success and unaddressed problems.

Key Factors to Consider before making a Decision

Making the right decision requires a meticulous navigation of your preferences and resources, including:

  • Financial resources: Startups can allow you to develop your business at a pace that aligns with your financial reality. However, if you have substantial capital to invest, buying a business can generate far quicker returns, directly accelerating your timeline to Financial Independence.
  • Risk tolerance: Starting a new company is statistically risky, requiring a high tolerance for volatility and economic uncertainty. While taking ownership of a working enterprise is more predictable, approaching it without adequate knowledge brings considerable financial dangers.
  • Industry expertise: Building a successful business requires deep market expertise and an aptitude for strategy. Alternatively, taking over a stable operation allows you to rely on existing teams while you learn.
  • Desired level of control: Founders typically want a blank canvas to execute a specific vision. Buyers must be willing to adapt to existing workflows and culture.

Essential Due Diligence Steps before Finalizing an Acquisition

Before officially acquiring a business, entrepreneurs are advised to conduct a thorough evaluation of the company and develop a strong understanding of its financial and operational standing.

Financial Verification

Even if a company’s overall revenue is healthy, it doesn’t showcase the full financial reality of owning it. Before making a purchase, you must review several years of tax returns and bank statements to understand the business’s financial history. Understanding the Seller’s Discretionary Earnings — which is the calculation of an owner’s entire financial benefit — is also nonnegotiable. Continue Reading…

Rising or Falling Markets? Roll with it!

Image Outcome/Shutterstock


Luck’ll come and then slip away
You’ve gotta move, bring it back to stay
You just roll with it, baby

— Roll with It, by Steve Winwood


By Noah Solomon

Special to Financial Independence Hub

There is never any shortage of pundits opining on what could make markets rise or fall. Tragically, the greatest cheerleading has tended to occur when markets were at their riskiest and the loudest fearmongering has tended to occur when markets have harboured the greatest opportunity. However, this does not change the fact that anything can happen at any time:  markets have and always will continue to periodically present investors with dynamically evolving combinations of risk and reward.

To never suffer losses is an unrealistic objective for those who wish to receive a satisfactory return on their investments. Rather, it is far more efficient (and financially rewarding) to roll with it: which entails adapting to changes to (1) maximize gains when markets offer above-average returns with relatively low risk and (2) to minimize losses when markets offer below average returns with above average risk.

This month, I present a framework for investors to dynamically manage their portfolios to meaningfully participate in rising markets while limiting losses in bear markets.

The Sine Qua Non of Successful Investing

If 100% of your portfolio is sitting in cash, then it is impossible for you to lose money (at least in non-inflation-adjusted terms). However, if markets rise, you will miss the proverbial boat and suffer significant opportunity loss. At the other end of the spectrum, if your portfolio is 100% allocated to equities, while you won’t miss the party if markets advance, you will most certainly suffer substantial losses in the event of a bear market.

The Latin phrase sine qua non means “without which not,” which refers to something that is a necessary or indispensable requirement. The sine qua non of successful long-term investing entails constantly assessing and reassessing the magnitude of potential losses relative to potential gains. When downside risks are elevated and potential gains are muted, you should hold a more conservative portfolio. Conversely, when the risk of loss is eclipsed by potential gains, it is prudent to take more risks with your investments.

Theory, Practice, and Yogi Berra

Baseball legend Yogi Berra stated, “In theory, there is no difference between theory and practice. In practice, there is.”

If you dial up your risk profile when the odds favour doing so and take some chips off the table when the probabilities dictate as such, your long-term performance will inevitably be well above average: so far so good. Unfortunately, accurately assessing and reassessing these probabilities as they ebb and flow over time is no easy feat.

You can’t Predict Behaviour

First the bad news: I don’t believe there is any accurate way to calculate the relative magnitude of upside vs. downside risk over the short term … and by the short term, I mean periods of at least one to two years! One need only to observe markets over the past three decades to appreciate that investors can persist in irrational behaviour for longer periods and with greater voracity than might seem possible.

In hindsight, most investors should have exercised prudence long before tech stocks reached their peak in early 2000 or real estate sung its swan song in 2008” but they didn’t. Similarly, they should have been scooping up bargains en masse either before, during, or not long after markets bottomed in early 2003 and March 2009: but they didn’t.

Excesses and financial aberrations cannot be explained by classic financial theory. Rather, their root lies in human behavioural biases and emotions, which can prove sufficiently powerful to propel asset prices to unrealistically optimistic and pessimistic levels. Greed and fear are impossible to precisely gauge or time and are arguably the largest determinants of prices over the short term. Given these facts, attempting to assess the relative risk of loss vs. opportunity cost over shorter horizons is an exercise in futility.

Valuations are a Proxy for the Margin of Safety

Valuations serve as a proxy for the margin of safety that is embedded in asset prices, and by extension for how vulnerable prices are to delivering subpar or even negative average annualized returns over the next 5-7 years.

Market Responses to Various Environments by Valuation Level

  • When valuations stand near the high end of their historical range, even strong economic and earnings growth may fail to result in higher-than-average annualized returns over the next several years, while anything short of such an environment is more likely to result in anemic performance or even losses.
  • When valuations stand near the middle of their historical range, prices are most likely to track economic conditions and profit growth.
  • When valuations reside near the bottom of their historical range, average or even above-average returns can persist even in the face of subpar economic conditions and/or profit growth, while more favourable or even average conditions are likely to produce strong gains.

Risk and Reward: Probability Distribution by Valuation


As valuations increase, the probability distribution shifts to the left, indicating a lower likelihood of gains and a higher probability of losses. Similarly, a decline in valuations results in a rightward shift in the distribution, portending an increased chance of gains accompanied by a lower risk of losses. At extremes, when markets are priced to perfection, there is almost no amount of good news that can prevent subpar returns over the next five to seven years, and when they are priced for Armageddon, strong returns are likely to ensue over the same timeframe in all but the most cataclysmic circumstances. Continue Reading…