All posts by Financial Independence Hub

Spooked by the stock market? Here’s the answer

By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

Most investors do not like volatility. They do not like looking at their investment account balance observing that they’ve ‘lost money.’

Of course, you have not lost money until you buy an asset at a certain price and then sell at a lower price. You’ve then just realized your losses. You have not lost money when your portfolio value goes down. And in fact, swings in portfolio values are just par for the course. Stocks and bonds and real estate change in price (with wild swings at times) in regular fashion: it’s normal behaviour. If the stock markets have you spooked, there is a simple and timeless plan of action.

With this strategy, you can ‘win’ if stocks go up. You can win if stocks go down. It’s a strategy that worked during the worst period in stock market history: the Great Depression of the 1930s .

The answer of course is adding money on a regular schedule. In the investment world they call it dollar cost averaging; we can abbreviate that to DCA. There is no need to guess about which way the market is going to go today, next week, next month, next year, or even the next five years. We simply expect or hope that the markets will go up over longer periods, as they have throughout history.

Stock market history

U.S. stocks, S&P 500

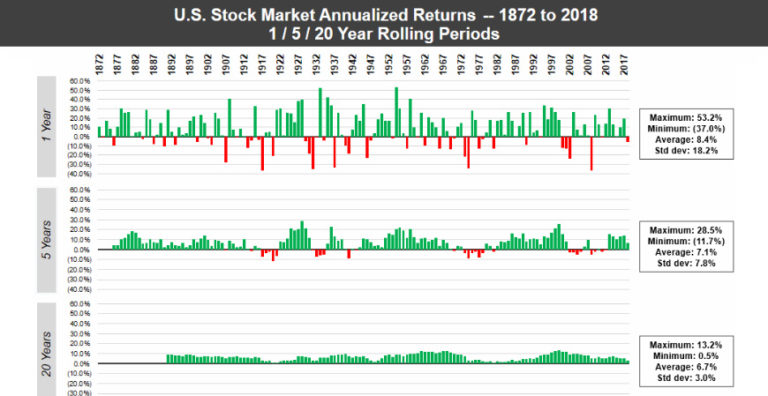
You can see that there is lots of green on the board. Stocks mostly go up. It is those pink years (on the table) that usually trip up many investors

The key to long-term wealth building is being able to invest through those down years. And in fact, adding money in those years is quite beneficial as the stocks go on sale.

But keep in mind that stocks can stay under water for extended periods.

Dollar cost averaging

Now this is a consideration for those who have very little exposure to stocks, or who have been out of the markets for quite some time. That event is not as rare as you might think. Many investors have left the markets, though they recognize that they need to be invested to reach their financial goals and enjoy a prosperous retirement. They also want their wealth protected from inflation.

Here’s the demonstration: investing through the initial stages of the Great Depression.

In the above charts we see equal amounts invested, but the dollar cost averaging strategy still delivered positive returns in a vicious bear market. Buying at those lower prices was very beneficial. Now keep in mind for the above to work, the markets have to go up over time. They have to recover. And historically they have.

Time reduces risk

Here is a wonderful graphic that demonstrates the returns over various periods. Our odds increase as we lengthen the time period that we remain invested.
And a table that frames the probabilities of positive returns.

Charlie Bilello

Spread out that lump sum

If you are sitting on a large sum that you want to get invested you will have to have a plan. Over what time period should you get those monies into the market?

If you start investing and the markets keep going up, great. Mission accomplished. The money you’ve invested has increased in value. You are collecting dividends along the way.

But of course when we enter a stock market correction, your total portfolio value will decline. Though you might get enough of a head start so that your money invested remains in positive territory.

At that point when markets are declining, remember that lower prices are good. The stocks are going on sale. And of course, you do not have to invest in an all-equity portfolio. You can dollar cost average into a balanced portfolio.

I’d suggest that you spread the money out over 2 or 3 years. For example, If you are on the 2-year plan and have $100,000 to invest and you’re investing every month, you’d invest $4,167 per month.

You can’t time the markets

For those who already have substantial assets invested, you can’t move in and out of the markets. We don’t know when the corrections will occur. The most reasonable course of actions is still dollar cost averaging. That said, whenever you have money to invest, stock market history says get it invested. The sooner the better.

From My Own Advisor here ‘s – Dollar cost averaging vs lump sum investing.

Invest within your risk tolerance level

This is key. If you get scared and sell, you might lose money.

You might have to accept a lower-risk portfolio that is likely to earn less over time compared to a more aggressive stock-heavy portfolio or balanced portfolio. It’s also possible that you do not have the risk tolerance to invest (at all), even in a very conservative ETF portfolio. If that is the case you would have to stick with GICs and high-interest savings accounts. You might add to your real estate exposure for growth. In retirement, you might use annuities to boost your income.

For savings we use EQ Bank. 3-and 6-month GIC’s now 2.05%

To help gauge your risk tolerance level and the appropriate level of portfolio risk, please have a read of the core couch potato portfolios on MoneySense. You’ll find a table within that post that breaks it down.

If you are risk averse, you likely need a managed portfolio and advice. You might consider a Canadian Robo Advisor. These investment companies provide lower-fee portfolios at various risk levels. Advice is also included. A few of these firms also offer financial planning.

At Justwealth, you get access to advice and financial planning. In fact, you’ll have your own dedicated advisor.

Justwealth. The Canadian Robo Advisor that knows when to get personal.

They will do a risk evaluation to see if investing is right for you, and then you will be placed in the appropriate portfolio(s). And once again, you’ll be offered the greater financial plan as well.

Start investing
Preet [Banerjee] puts some of the above in video form [YouTube.com]. Preet also goes over how much you might market over various time frames, at different rates of return.

The key is to not be frozen on the sidelines. We might refer to that as ‘paralysis by analysis’.

Build wealth at your own comfort level, at your own pace. You will learn as you go. You can build up your comfort level for risk and volatility. It’s quite possible that you can increase your risk tolerance level over time. We develop risk callouses.

Walk before you run, perhaps.

Robo Advisors are a great training ground for investors.

Thanks for reading. We’ll see you in the comment section. If you’re not sure what to do, feel free to flip me a note.
Dale Roberts is the Chief Disruptor at cutthecrapinvesting.com. A former ad guy and investment advisor, Dale now helps Canadians say goodbye to paying some of the highest investment fees in the world. This blog originally appeared on Dale’s site on Feb. 12, 2022 and is republished on the Hub with his permission.
When did Retirement Income Planning get so complicated?

Photo by Gustavo Fring from Pexels

By Ian Moyer

(Sponsor Content)

Retirement planning used to be easy: you simply applied for your government benefits and your company pension at age 65. So, when did it get so complicated?

Things started to change in 2007 when pension splitting came into effect. While we did have Canada Pension Plan (CPP) sharing before that, not too many people took advantage of it. Then Tax Free Savings Accounts (TFSA) came along in 2009. At first you could only deposit small amounts into your TFSA, but in 2015 the contribution limit went to $10,000 (it’s since been reduced to $6,000 per year). Accounts that had been opened in 2009 were building in value, and the market was rebounding from the 2008 downturn. Registered Retirement Savings Plan (RRSP) dollars were now competing with TFSA dollars and people had to choose where they were going to put their retirement money.

In 2015 or 2016 financial planners suddenly started paying attention to how all of these assets (including income properties) were interconnected. There were articles about downsizing, succession planning, and selling the family cottage. This information got people thinking about their different sources of retirement income and which funds they should draw down first.

Of course, there is more to consider, such as the Old Age Security (OAS) clawback. When, where, and how much could this affect your retirement planning? People selling their business are often surprised that their OAS is clawed back in the year they sell the business, even if they’re eligible for the capital gains exemption. Not to mention what you need to do to leave some money behind for your loved ones. Even with all this planning, the fact that we pay so much tax when we die is never discussed, although the final tax bill always seems to be the elephant in the room. We just ignore it, and hope it’ll go away.

Income Tax doesn’t disappear at 65

Unfortunately, income tax doesn’t disappear at age 65, and you need time to plan ahead so you can reduce the amount of tax you pay in retirement. A good way to do this is to use a specialized software that takes all your sources of income and figures out the best strategy to get the most out of your retirement funds. Continue Reading…

Target Date Retirement ETFs

Image licensed by Evermore from Adobe

By Myron Genyk

Special to the Financial Independence Hub

Over the years, many close friends and family have come to me for guidance on how to become DIY (do-it-yourself) investors, and how to think about investing.

My knowledge and experience lead me to suggest that they manage a portfolio of a few low-fee, index-based ETFs, diversified by asset class and geography.  Some family members were less adept at using a computer, let alone a spreadsheet, and so, after they became available, I would suggest they invest in a low-fee asset allocation ETF.

What would almost always happen several months later is that, as savings accumulated or distributions were paid, these friends and family would ask me how they should invest this new money. We’d look at how geographical weights may have changed, as well as their stock/bond mix, and invest accordingly.  And for those in the asset allocation ETFs, there would inevitably be a discussion about transitioning to a lower risk fund.

DIY investors less comfortable with Asset Allocation

After a few years of doing this, I realized that although most of these friends and family were comfortable with the mechanics of DIY investing (opening a direct investing account, placing trades, etc.) they were much less comfortable with the asset allocation process.  I also realized that, as good a sounding board as I was to help them, there were millions of Canadians who didn’t have easy access to someone like me who they could call at any time.

Clearly, there was a looming issue.  How can someone looking to self-direct their investments, but with little training, be expected to sensibly invest for their retirement?  What would be the consequences to them if they failed to do so?  What would be the consequences for us as a society if thousands or even millions of Canadians failed to properly invest for retirement?  

What are Target Date Funds?

The vast majority of Canadians need to save and invest for retirement.  But most of these investors lack the time, interest, and expertise to construct a well-diversified and efficient portfolio with the appropriate level of risk over their entire life cycle.  Target date funds were created specifically to address this issue: they are one-ticket product solutions that help investors achieve their retirement goals. This is why target date funds are one of the most common solutions implemented in employer sponsored plans, like group RRSPs (Registered Retirement Savings Plans).

Generally, most target date funds invest in some combination of stocks, bonds, and sometimes other asset classes, like gold and other commodities, or even inflation-linked bonds.  Over time, these funds change their asset allocation, decreasing exposure to stocks and adding to bonds.  This gradually changing asset allocation is commonly referred to as a glide path.

Glide paths ideal for Retirement investing

Glide paths are ideal for retirement investing because of two basic principles.  First, in the long run, historically and theoretically in the future, stocks tend to outperform bonds – the so-called equity risk premium – which generally pays long-term equity investors higher returns than long-term bond investors in exchange for accepting greater short-term volatility (the uncertain up and down movements in returns).  Second, precisely because of the greater short-term uncertainty of stock returns relative to bond returns, older investors who are less able to withstand short-term volatility should have less exposure to stocks and more in less risky asset classes like bonds than younger investors. Continue Reading…

How to handle Fear of a Market downturn

Image courtesy Kiplinger/RetireEarlyLifestyle.com

By Billy and Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

On our latest adventure, we were on the beach in Isla Mujeres, Mexico when a lady recognized us from our website RetireEarlyLifestyle.com. After some pleasantries, she asked if we could address the fears of the market declining and how to handle it.

We appreciated that input from one of our Readers.

Previous market declines

Since the surviving the 1987 crash when the Dow Jones Industrial Average fell over 20% in one day, there have been other downturns including the recent ones of 2007-2008 and the Covid meltdown in March of 2021. We have learned from each of them.

They can be trying on one’s patience and confidence, so how is it best to handle them?

Noise, corrections and bears

First, let’s define these meltdowns.

Between a 5-10% decline in the averages is called noise and can happen at any time.

Many individual stocks have these gyrations, which is why we own the Indexes. They are more stable.

Over a 10% drop is called a correction, meaning it is wringing the excesses out of the markets. The markets are constantly being over-extended and under-extended and these 10% moves correct for those times.

If the averages drop 20% or more, it is considered to be a bear market and we tend to have these every 56 months.

On average, bear markets last 289 days or 9.6 months with an average loss of 36.34%. These can be painful for one’s financial health — or an opportunity — depending on where you are in the investment cycle.

A number of events can lead to a bear market: including higher interest rates, rising inflation, a sputtering economy, and a military conflict or geopolitical crisis. Seems we have all of these presently!

If you are in the accumulation phase and buying more shares at cheaper prices, this can be a bonus for you. However, if you are now retired and living off your investments with your account values dropping, that can be difficult to swallow.

How to calm your nerves to prevent panic selling

It’s important to note the difference between trading and investing.

Traders drive the day-to-day activity, booking profits and hopefully taking losses quickly. We investors take a longer view to ride out these cross currents of the markets knowing that — over the long run — we will be fine. Continue Reading…

Retirement Readiness: The investment fee gap can set retirement back four years


By Jillian Kennedy, Mercer Canada

Special to the Financial Independence Hub

If someone said you could have four extra years to enjoy your retirement, you’d probably be thrilled. Now imagine being forced to hold off on retirement for four years longer than you planned. 

As it turns out, a gap in investment management fees can potentially make that a reality for many Canadians – but there is a fix.

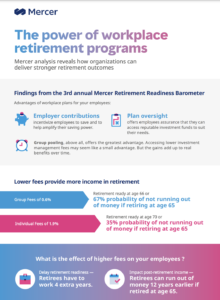
Our newly released 2022 Mercer Retirement Readiness Barometer analyzed the various investment management fees in the market and their impact on retirement readiness. What we found is that someone paying the median level of fees for an individual investment account – 1.9% – would have to wait until age 70 to be retirement ready. Obviously, that’s well past the traditional retirement age target of 65 that many of us have in our sights.


It’s a different story if you consider the benefits of a workplace defined contribution (DC) plan. An individual paying 0.6% in fees – the median for a DC savings plan – would be ready for retirement four years sooner, at age 66. (The analysis assumed individuals are invested in a “balanced” target date portfolio with a 12% combined contribution rate – with 6% coming from the employee and 6% from the employer).

Those who have access to a workplace DC and savings plan can benefit from pooling power and lower fees in a group arrangement. Personal finance experts have commented for years on this fee disparity between group workplace plans and other investment savings vehicles, but this analysis puts that into clear perspective. Consider not only shaving years off your working life but having a better quality of life in the retirement years that follow.

The fee gap’s impact before – and after – retirement

This gap in fees doesn’t only affect the savings phase, but also the period after someone begins to draw from their retirement savings. It’s common to move retirement savings from a workplace plan into an individual account and at that point, higher fees tend to kick in.

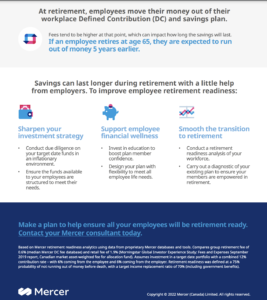
Take, for example, an individual retiring at 65. Our analysis shows that if that person pays the median retail fee (1.9%) when they begin drawing money from their individual retirement savings account, they’ll run out of money five years earlier compared to someone paying the median group fee of 0.6%. 

If someone is paying the median group fee (0.6%) throughout their career, on the other hand, then retires at age 65 and subsequently invests their nest egg in an account paying that same rate, they will have an average of 12 more years of retirement income compared to a similar person paying the median retail fee (1.9%) over the same period.

Group pooling is a powerful tool

Of course, successful retirement income planning takes a comprehensive approach including workplace savings programs, government benefits and personal savings. Higher contribution levels and a smart investment strategy also play an important role, as does money management post-retirement.  Continue Reading…