All posts by Financial Independence Hub

In volatile times, look for Quality

By Paul MacDonald, CIO, Harvest ETFs

(Sponsor Content)

After nearly two years of a global pandemic, capped by surging inflation, the past month has been dominated by Russia’s invasion of Ukraine and a wave of geopolitical uncertainty unleashed by the largest European conflict since 1945.

“What a crazy decade these past two years have been,” is a line making the rounds on social media at the moment.

In the midst of all this volatility, uncertainty, and tension, we believe it’s important to focus on quality investments. We should begin by understanding and defining quality within our unique philosophy at Harvest ETFs. We can then outline some of the strategies at work in our Harvest ETFs that protect against volatile times and how today’s shocks fit in a longer-term macro-outlook.

Be diversified and own quality

To begin, our view remains that you want to be diversified and you want to own quality. How do you measure quality though? At Harvest, we do it through financial metrics like variability of earnings, visibility into earnings, return on invested capital and others. What those metrics tell us is that large-cap companies have the ability to navigate tail risks.

While risks related to geopolitical tension are top of mind now, we should emphasize that supply chain issues, inflation, and interest rate transitions are arguably the biggest volatility risks now. In this uncertain environment, it’s important to prepare for volatility from a wide range of sources. The expectations for how much and how quickly interest rates will rise is also going to be volatile and will likely result in some sectors doing better at different times, more so than what we have seen in recent history. Volatility shouldn’t come as a surprise if we’re adequately prepared for it with an investment approach that focuses on quality & diversity.

Our focus on quality is a core element of the Harvest investment philosophy. That philosophy focuses on leading companies in specific sectors or mega trends as the best place for investors to be if they want long-term capital appreciation prospects and income across market cycles.

Income Generation and Covered Calls

Income generation is another core element of the philosophy at work in Harvest’s equity income ETFs. That is achieved through a covered call strategy, generating a premium by agreeing to sell up to 33% of a holding at a set price. Using an active covered call strategy, Harvest’s team of portfolio managers generate consistent and high yields on their ETFs. As well, the value of call options tends to increase when volatility and uncertainty increase. The premiums generated by the covered call strategy act as some downside protection by the premium received. Continue Reading…

How millennials can find Financial Independence


By Mark Seed
Special to the Financial Independence Hub

New year, same movement. The FIRE (Financial Independence, Retire Early) movement remains a big thing.

How can millennials find financial independence?

Can millennials find FI via leverage?

What questions are millennials asking themselves when it comes to wealth building, saving and investing?

This post explores some answers: how millennials can find financial independence.

What do millennials want? Some millennials want financial independence!

While some age ranges will vary depending on the report you read, the millennial cohort (GenY) was born between 1981 and 1995, which puts millennials in the age range of 27-41 in 2022.

As you well know from my site, and my own journey, I believe your 30s are critical years to define your financial wellbeing. Many important life decisions are made during this period of life, such as career selection, buying a house, potentially getting married, starting a family, and much more.

The lifestyle and consumption decisions you make in your 30s could very well define your 40s and future decades, including how much wealth you can build.

In the succinct and well-written book If You Can – How Millennials Can Get Rich Slowly by William Bernstein, there is a simple five-step formula to help millennial investors realize some financial independence dreams. I encourage any 20- or 30-something reading this site to download and read that FREE e-book from my link above or below. I think it will be impactful.

While some millennials will be the major recipients of some of the largest wealth transfers in history, now underway from a mix of older GenX and Boomer parents, via large financial gifts, I suspect some millennials will not have that luxury to rely on for their financial footing.

This means many millennials will need to do what I have done: make their financial independence dreams happen on their own.

Personally, I’m a huge believer in charting your own financial path and not relying on others to do it for you. Sure, you’ll make money mistakes along the way (I have) but you’ll also learn to think for yourself and hopefully hone some critical thinking skills along the way.

Further Reading: My lessons learned in diversification. 

Millennial investor profile – Liquid from Freedom 35 Blog

For many years now, I’ve been inspired and motivated by financial independence. So have other investors that I’ve had the good fortunate to connect with by running this blog. So, in that light, I’ve also been inspired by their stories and what they do differently.

You can read many of those stories on this dedicated Retirement page here. I’ll link to some others below.

One blogger in particular that has an interesting story and some lessons to share is “Liquid” from Freedom 35 Blog.

Liquid moved out of his parent’s basement when he was 21 and hasn’t looked back – paying off some small student loans and building up his net worth recently (now in his mid-30s) to $1.5 million. His long-term goal was always to be “financially free before his 35th birthday”. That goal is now achieved. He ’got there’ by controlled leverage, value investing, taking advantage of market corrections, swing trading, dividend investing, alternative investing and more.

I thought it would be fun to have Liquid on the site, share a bit of his story, and discuss how he used leverage wisely to realize some financial independence dreams far earlier than most.

Liquid, welcome to the site and thanks for your time!

My pleasure Mark and very happy to spend time with you and your readers!

When it comes to our financial journey in general, I know we’re just ‘not there yet’ and I’ve got a few years on you! We are I believe, on a decent path – saving, investing and killing mortgage debt at the same time. Folks are quite familiar with my plan but maybe not so much about you!

Tell us about yourself? In what field do you work, did you work in?

Thanks Mark. Well, I have been enamored with finance and business since I was 18. But despite my best efforts to get into business school I was rejected because of my poor grades. I ended up taking applied sciences instead. But that was a mistake. The program was so difficult I failed all my classes. I was forced to drop out after the first year.

After flunking college, I found a job at Safeway, making minimum wage. Luckily, I was still living with my parents at the time.

One day in 2007 I noticed a local art school was offering a one-year program in graphic design. I’m clearly not academically gifted. But maybe I can draw. I thought it was worth a shot. So, I enrolled.

I received my diploma the following year at age 21 and began my career as a graphic designer. My starting annual salary was $35,000.

Today I’m a senior designer at a large entertainment firm making $75,000 a year. Although it wasn’t my first choice, I am happy with my career decision and how it turned out. The pay is decent. And I can save money to pursue what I’m truly passionate about – finance and investing.

Great stuff. You have found your passion with investing for sure. How did you get started with investing? When did you start investing? What is your investing approach?

In 2009 I wanted to move out of my parents’ basement. After considering my options I concluded that buying was better than renting. So, I purchased a 2-bedroom apartment in Vancouver for $230,000.

This was my first investment, and my first home. At this time, I had $15,000 in personal savings. Not much. But it was enough to cover the downpayment and closing costs. Then I began to invest in the stock market, and other asset classes.

My investing approach can be broken down into 2 parts.

The first part is to mimic the strategies used by the best investors.

Allan Mecham was a college dropout like me. But he managed a fund that compounded at 30% a year.

Activist investor Bill Ackman produced a 70% investment return in 2020. But his long-term record is more like 20% a year, which is still pretty good. Macro investor George Soros managed a fund that returned 30% a year on average for many decades. And of course, value investors like Mohnish Pabrai and Warren Buffett have outstanding long term track records as well.

These public figures in the investment sphere have written books, appeared in interviews, and spoken on podcasts to discuss their ideas, strategies, and outlooks on the markets. Bill Ackman even has a list of 8 core principles that he uses to screen investments. Whenever he deviates from those principles his performance suffers. Furthermore, it’s easy to find exactly what these investors are buying because they have to submit 13F filings regularly to disclose their holdings publicly.

By understanding what these successful investors are doing with their money, I can essentially copy their methods and buy the same stocks as them. This naturally leads to my portfolio having the same kind of high returns as them.

Often the top performing investors will like the same stocks. But sometimes their strategies diverge so I have to decide which one works the best for my situation.

This brings me to the second part of my investing approach, which is to document my investment transactions and track the results. I like to use a spreadsheet for this. I also like to track my thought process, and the reason for making my decisions. This allows me to go back, review what happened, keep what worked, and throw away what didn’t so I can improve my process for next time. This experience has helped me become a better investor over time.

Copy the best, or at least tailor what the best do for you. Good stuff. So Liquid, like some other millennial bloggers are you a fan of FIRE? Why or why not? Have you achieved FIRE or FI? What is the key difference in your opinion between FIRE / retired early or FI or are they same to you?

As a kid I was constantly being told what to do (or not do) by others, and it was frustrating. Despite all the guidance I still felt a lack of direction. However, once I grew up and started to live on my own terms, I began to discover more purpose in life. I was free to make my own decisions and it was liberating. There was just one problem. I still had to work to put food on the table. That’s when I discovered financial independence.

I deeply value freedom so I made it a priority to become wealthy. I’m a fan of FI, but I don’t know about FIRE. I achieved financial independence in 2020 so I consider myself to be FI right now. I’m turning 35 later this spring. And that’s when I will hand in my letter of resignation and quit my 9 to 5 job permanently. Although I will be retired from full time work, I wouldn’t consider myself to be “retired.” There is no universal consensus on what retirement means anymore as the world embraces Web 3.0 and the gig economy.

You’ve had some interesting investments over the years on your path to FI. Can you highlight some investing successes or mistakes along the way? What did you learn from those lessons to help you move forward that might help other millennials reading this?

I’ve been very fortunate to see high returns investing in exotic assets such as Zimbabwe’s banknotes and Playboy magazines.

(Mark: that’s funny but good!)

But I often learn the most from the investments that didn’t do well.

One of my earlier investing mistakes was buying a leveraged volatility ETF that makes trades in the futures market. I knew this fund was risky, but I didn’t really understand what made it so. I initially wanted to make a quick swing trade. But when the ETF’s price fell, I held on – waiting for a reversal instead of cutting my losses. That was the wrong decision. Eventually a lower VIX and the adverse effects of contango wiped out 99% of my position, and I lost $2,000. From then on, I only invest in things that I actually understand. I learned the importance of knowing what I own. Today I can explain any investment I have to a 4th grader, and I can delineate why I own it. Continue Reading…


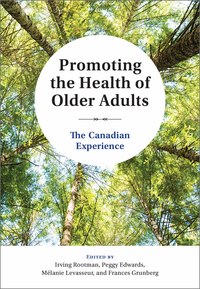
Promoting the Health of Older Adults: a worthy read for all

By Mark Venning, changerangers.com

Special to the Financial Independence Hub

As an everyday person taking a fast read of the title of the new book – Promoting the Health of Older Adults: The Canadian Experience – you wouldn’t exactly get the sense of what to be surprised by or expect what content would be covered within. In the first place, unfortunately, it’s not likely that this book will make it into the hands of everyday people any time soon.

You might ask, what are we promoting, what’s so specific for older adults – eat a nutritional diet of foods, exercise to stay fit, keep your brain active and get your proper sleep? Isn’t that what anyone through their life course should be doing? Yes, maybe. But that’s not at all exactly what you will get here.

Appreciating focus, as the writers in the preface state, the book’s main purpose is for knowledge building on issues related to older adults and their care, primarily for target audiences such as, “undergraduate and graduate students in gerontology and aging, health promotion… and other fields….” and the five groups identified include, educators, learners, policy makers, researchers and practitioners and leaders working with older adults in civic society organizations.

While that may sound too academic, after reading this book my belief is that the general public of everyday people, older adults and others younger, will also benefit greatly from an education presented here on this important subject. If you do flip through this 600-plus page tome, you might think of it at first as “insider dialogue” on health promotion; but not so fast, don’t put the book down.

Serving to heighten knowledge & awareness to engage in social health dialogue.

Choose as many words as you want; for me, Promoting the Health of Older Adults is a social health dialogue, inclusive for all Canadians – interconnected subject areas, holistic, comprehensive, diverse. The arrival of this book is timely, to promote conversation with friends and family, considering our collective journey through the COVID world to date has heightened our awareness of the workings of our own health and our social and healthcare systems.

Briefly, on the structure of this book; it certainly is more of a study text book on over thirty topic areas in seven well laid out parts. However nothing I’ve read talks over the heads of readers, and if facilitated well in a real time group discussion format, there is a set of critical thinking questions at the end of each chapter that would further serve to heighten knowledge and awareness of readers, enough to make you want to be a more engaged in this social health dialogue. Continue Reading…

Dealers putting Clients’ Retirements in Jeopardy

By Nick Barisheff

Special to the Findependence Hub

Over time, most investment dealers have implemented misguided policies that will negatively affect their clients’ investment portfolios and their ability to achieve a secure retirement.

There are two main policies that have negative impacts on investors’ portfolios. One is restricting investments to a client’s original Risk Tolerance in the Know Your Client application form (KYC). When opening an account, the client will advise the dealer of their Risk Tolerance.  Most clients will indicate that they are medium risk. On March 8, 2017, the Ontario Securities Commission (OSC) implemented risk rating rules that require all mutual funds to rate their fund according to 10-year standard deviation. In 2018, I published an article entitled New Mandatory Risk Rating is Misleading Canadian investors.

Prior to the OSC’s implementation of the risk rating rules, on December 13, 2013, the OSC issued CSA Notice 81-324 and Request to Comment – Proposed CSA Mutual Fund Risk Classification Methodology for Use in Fund Facts. My comments on this policy were submitted to the OSC on March 12, 2014, along with comments from 50 other industry experts.  

I presented a paper to the OSC that argued that Standard Deviation is not an appropriate measure of risk, since the best-performing mutual fund and the worst-performing mutual fund in Canada had the same Standard Deviation.  The measure of Standard Deviation of an investment does not reduce the risk of incurring losses.

A better, more accurate methodology would have used downside standard deviation or the Sharpe or Sortino ratios which measure risk adjusted returns. Nevertheless, the OSC implemented risk rating rules requiring all mutual funds to rate the risk of their funds according to 10 year standard deviation.

As a result, if investments in a client’s portfolio exceeded the risk tolerance as indicated in the original KYC, the client was forced to redeem those investments, by the advisor’s compliance department. A number of BMG’s clients were forced to redeem their positions since our funds had a medium-high risk rating according to the OSC formula, and the clients’ KYC indicated medium-risk tolerance. A number of clients wanted to change the KYC in order to allow them to maintain ownership of our funds but were advised that, unless there was a significant change in their financial circumstances, they could not change their KYC. Continue Reading…

6 Expenses that First-time Homeowners should plan for

Image Source: Unsplash (https://unsplash.com/photos/cqAX2wlK-Yw)

By Beau Peters

Special to the Financial Independence Hub

Becoming a first-time homeowner is an exciting prospect. It’s a chance to have a place you can call your own, where you can make memories for years to come.

With that said, proper planning is necessary, or your dream can become a financial nightmare. The fact is that there are many unavoidable and potential expenses that could occur over time, and if you don’t understand the realities or you don’t save appropriately, then you could be in for some hard times.

To help you out, we have compiled a list of common expenses that most first-time homeowners will experience and how to prepare accordingly.

1. Closing Costs

As you are looking at potential homes and comparing your financial situation, you will want to keep in mind that there are some upfront expenses that you will want to consider, especially closing costs, which may amount to 3-6% of the total loan value. It is important that you have those funds fluid and ready to go when you sign your new mortgage.

If you are short on funds, then consider creating an agreement with the seller to share these costs or look into government programs if you are short.

2. HVAC Issues

No matter where you live, yyour HVAC (Heating, Ventilation, and Air Conditioning) units will likely need to be repaired either soon or down the road. While most units can last 10 to 15 years, if you run your heat or AC all day, every day, then you could be looking at a repair sooner than later, especially if you bought a home with an existing unit.

When preparing for the expenses associated with a damaged air conditioner, you will need to decide if you can have your unit repaired or if it will need to be completely replaced. The first thing you should do is get a quote from a professional to see if the cost to repair is almost as much as the cost to replace. If it is, consider getting a brand new unit because you know it will last a long time and work at high efficiency. Also, consider the fact that if your AC had to be repaired once, it will probably require maintenance again. Include these considerations in your final decision.

3. Appliance Lifetimes

Whether you are moving into a home with existing appliances or you are buying them brand new, you must realize that all appliances have their expiration date. For instance, refrigerators often last about 10 years, and even if they are still usable after that time, their efficiency will begin to dwindle. As far as other appliances:

  • Washers and dryers typically last about 10-13 years.
  • Dishwashers have about 10 years.
  • Microwaves typically last around seven years.

Knowing these dates is important so you can begin to budget accordingly to pay for a replacement.

As a new homeowner, an expense that you may want to incur is the cost of a home warranty. Many of these programs cover a portion of the price of the service calls necessary to fix your appliances, and your annual fee will also help with the cost of a new unit. As soon as you move into your home, look for home warranty programs and find one that suits your needs and financial situation.

4. Roof Damage

The roof is arguably one of the most important aspects of your home, and if it is damaged by weather or general wear and tear, then you will want to have it inspected and repaired immediately. Typical roofs built with asphalt shingles will last about 20 years, so if you have a new home, you may be good for a while, but if you bought a used home, then you will want to see how much time is left. Continue Reading…