All posts by Financial Independence Hub

U.S. Growth stocks: You’d better be Seabiscuit

This is Part 2 of a two-part blog series on the prospects for Growth and Value Stocks.

Read Part 1 Growth Stocks: Where’s the Beef?
By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

When your starting point is a 1.4% dividend yield,1as is the case with the S&P 500 Growth Index, the group of stocks that make up the basket need to have long-term dividend growth that performs like Seabiscuit, the super horse. No tripping out of the gate or getting bumped in the stretch.

Latching on to the concepts in my white paper, Dividend Growth’s Drivers: Picking Apart Quality, we present figure 1, which shows the interrelationship between the percentage of earnings that are retained (as opposed to paid out as dividends) and the return on equity (ROE), which is net income as a percentage of shareholders’ equity.

This relationship is thedriver of dividend growth, and as the years go on, concepts like figure 1 have become core tenets of second-decade WisdomTree.

Figure 1: The Critical Equation

The Critical Equation

Figure 2 uses the critical equation to calculate long-term dividend growth at prevailing profitability levels.

As it stands, the S&P 500 Growth Index’s 23.2% ROE implies long-term dividend growth of 16.8%. That could happen, yes. Anything canhappen. But here’s a better idea: expect downward revisions instead.

Figure 2: Implied Dividend Growth Estimate 

Implied Dividend Growth Estimate

After all, look at the historic record in figure 3. There isn’t a single five-year period that had growth stocks’ earnings running forward at a 16.8% clip, not even in the roaring 1990s. In contrast, value stocks’ implied dividend growth is on planet Earth. 

Figure 3: Dividend Growth Rate, 5-Year Periods, 1995–Present 

Dividend Growth Rate 5Year Periods 1995Present

Does anything jump out in figure 3? Look at the dividend growth experience of growth and value from 2010 to 2015 and from 2015 to the present.

Those growth stocks start to look less like Seabiscuit and more like also-rans if recent years are any indication. Granted, value indexes are dominated by banks, and the period from 2010 to 2018 was characterized by the benefit of their reinstated dividends. Nevertheless, if growth stocks were only able to increase their dividends at a high single-digit rate during this period of irrepressible economic expansion, what happens if recession hits? Let someone else pay 22 times earnings to find out. 

Slow and Boring? Better than Growing Out of 1%

The S&P 500 Value Index has a dividend yield that is about double that of the S&P 500 Growth Index (2.7% vs. 1.4%). This kind of gap makes it nearly impossible for the latter index to ever grow out of its valuation.

If U.S. growth could not differentiate its … ahem … dividend growth relative to value from 2010 to 2018, what makes anyone think the next several years will be different? For growth stock skeptics, the WisdomTree Fund that hits value is the WisdomTree U.S. High Dividend Index ETF (HID/HID.B). 

It retains 38% of its earnings, pays out the other 62% as dividends and has an ROE of 13.5%. That ROE is satisfactory enough. Using the “critical equation,” it has long-term implied dividend growth of 5.1%, which is less than the levels of the S&P 500 Growth Index. But when the starting point is a 1.4% forward dividend yield, companies that populate indexes like the S&P 500 Growth Index would have to run up their dividends at a 15% or 20% annual pace for a long time before the math even thinks about shifting in their favour.2

For investors who do not want to commit to value because they keep getting burned, a fund like the WisdomTree U.S. Quality Dividend Growth Index ETF (DGR/DGR.B), which tracks the WisdomTree U.S. Quality Dividend Growth Index CAD, seeks to target companies that rank well on our ROE x earnings retention framework. 

Critically, its dividend weighting methodology also checks valuations at the door. That gives it a starting dividend yield of 2.7%, about 130 bps more than the S&P 500 Growth Index. It also has an explicit screen for ROE and return on assets (ROA). Its 15.8x forward earnings multiple is 3.3 multiple points below the S&P 500 Growth Index.

Over the next 5 or 10 years, we’ll take DGR.B or HID.B over S&P 500 Growth Index. This is where the rubber meets the road, when the cap-weighted U.S. large-cap growth indexes start to be priced like they’re Seabiscuit, when in reality they’re an underlay.

1Sources: WisdomTree, Bloomberg, as of 11/15/18.

2Sources: WisdomTree, Bloomberg. Unless otherwise stated, all data in this blog as of 11/15/18.    

Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.

U.S. Growth stocks: where’s the beef?

This is Part 1 of a two-part blog post series on the market’s current expectations for U.S. growth and value stocks.

Figure 1: S&P 500 Growth Total Return Index Relative to S&P 500 Value Index

S&P 500 Growth Total Return Index Relative to S&P 500 Value Index

By Jeff Weniger, CFA WisdomTree Investments

Special to the Financial Independence Hub

At the risk of making a 34-year-old pop culture reference, growth stock fundamentals beg the question first posed by Wendy’s: “Where’s the beef?”

As was the case in 1984, when war was declared on McDonald’s and Burger King, there appears to be a lot of “bun” in U.S. growth stocks but not a lot of “meat.”

Face it:  the magnitude and duration of the multi-year clobbering of value strategies by growth stocks in the current cycle is second only to the legendary 1994–2000 “New Economy” years. That epic mania for growth as an investing style began about a year before the 1995 Netscape IPO,1 at which point the tech boom began to rage. That furious less-than-six-year rally in the second half of the 1990s took the S&P 500 Growth Index 400.7% higher (31.2% annualized), trouncing the S&P 500 Value Index’s gain of only 198% (20.2% per year).2 When the rug was ripped out in the 2000–2002 crash, value stocks picked up thousands of basis points of outperformance.

Today, the cumulative gap between the two indexes, which has been stretching out since 2006, is once again in triple digits. From July 31, 2006 to October 31, 2018 — more than 12 years — the S&P 500 Growth Index returned 296% (or 11.9% annually), about doubling the 152% appreciation of the S&P 500 Value Index (7.8% annually).

That’s 144 percentage points.

Before we begin searching for The Beef, consider the striking picture painted by figure 1 (at the top of this blog). As a reminder, the NASDAQ, about as “growthy” an index as can be constructed, started its crash in March 2000. The S&P 500 Index topped out later that summer. When they did, the rotation to value stocks was a flood.

Piggybacking on WisdomTree’s Prior Dividend Growth Work

We received positive feedback on our white paper, Dividend Growth’s Drivers: Picking Apart Quality, and this analysis builds on many of those concepts for the growth/value debate. In that piece, we looked at our Quality Dividend Growth suite, diving into the interaction of return on equity (ROE) with earnings retention and dividend payout ratios to determine the long-term drivers of shareholder wealth. The interrelationship between profitability and dividend policy is critical, and the more research we do on it, the more these concepts are becoming core parts of second-decade WisdomTree.

Figure 2 shows profitability and growth metrics for the S&P 500 Growth, S&P 500 and S&P 500 Value Indexes.

Figure 2: S&P 500 Growth, Core and Value Metrics

S&P 500 Growth Core and Value Metrics

The Critical Equation

Dividend Growth’s Drivers: Picking Apart Quality identified profitability (ROE) as the driver of dividend growth, presenting the critical equation recreated in figure 3.

Figure 3: The Critical Equation

The Critical Equation

Figure 4 uses the critical equation to calculate “long-term” dividend growth for the three indexes. We added quotation marks to “long-term” because, frankly, looking into the future involves a lot more art than science.

Figure 4: Implied Dividend Growth Estimate

Implied Dividend Growth Estimate

Can the S&P 500 Growth Index achieve long-term dividend growth of 16.8%? And how long is long-term? No one knows, including us.  But we can engage the numbers to get a feel for whether we want to pay nearly 22x forward earnings for growth stocks when value stocks are on offer for 15x earnings.

In Part 2 of the blog post, we consider the possibility of multi-year 17% growth in dividends, and whether it even makes sense. Spoiler alert: it doesn’t.

Stay tuned for our suggestions for growth investing: namely ideas like the WisdomTree U.S. Quality Dividend Growth Index ETF (DGR.B), which tracks the WisdomTree U.S. Quality Dividend Growth Index CAD, and the WisdomTree U.S. Quality Dividend Growth Variably Hedged Index ETF™ (DQD), which tracks the WisdomTree U.S. Quality Dividend Growth Index Variably CAD-Hedged. For investors that want more of a switch in the direction of value stocks, one of our better yielders in broad U.S. equities is the WisdomTree U.S. High Dividend Index CAD, tracked by the WisdomTree U.S. High Dividend Index ETF (HID.B). The quality dividend growth indexes yield 2.7%, while the high dividend index has a yield north of 4%, putting them handily above the dividend yield on offer for the S&P 500 Growth Index.3 

1The famed 1995 Netscape IPO is widely regarded as one of the first newsworthy events of the dot.com boom.
2Sources: Bloomberg, WisdomTree, 04/29/1994–03/31/2000. Unless otherwise stated, all returns in this blog in CAD.
3Sources: WisdomTree, Bloomberg, as of 11/15/18.

Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.

Tracking your financial health in Retirement

Sailing in Boracay, Philipplnes

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

No matter what stage of life you are in, it is important to know your financial health. This is not something you do just around income tax time but throughout the year. It’s good to check in at least monthly or, as we do, daily. The same as any successful business must know their income and liabilities, so should you.

Today there are plenty of free online tools that can help you, but we are old school and prefer to be able to check and edit our data anywhere in the world and at any time regardless of an internet connection. We have done this since we retired in 1991. Back then we used a paper notebook and pen, but today we created a spreadsheet using an Excel program that is on most computers sold today.

How it works

Throughout the day as we spend money we keep a mental note of the cost. Then, usually in the evening while winding down, we enter the data into our spreadsheet. We created categories such as housing, food, dining, transportation, donations, healthcare, and so on. Each of those entries then gets automatically added giving us a total for the day. That number is added to all of the previous entries and then divided by the day number in the year, 1 through 365, giving us a daily average.

Utilizing this system we can adjust the entries using local currencies, therefore knowing what we are spending in Mexican Pesos, Thai Baht, Vietnamese Dong, Guatemalan Quetzales or the money of any place where we are traveling. While this figure can easily be converted to dollars if we want, we prefer to think of our costs in the currency of our host country. This keeps our spending at the perspective of the natives instead of distorting it by thinking in Dollars.

This information is important

Once you know how much you are spending per day you can utilize this information to adjust spending accordingly if necessary. You are in control of your outflow at this point, and you can make changes in real time.

Net worth: What is it?

Another important tool for understanding your financial health is calculating your net worth. This number is derived by adding up all of your assets minus your liabilities. Do you own a house or rentals? Figure out what they are worth, then subtract out what you owe and this equates to the equity you have. It is important to use realistic numbers knowing that if you sold today, there would be fees and expenses involved as well as taxes to be paid. Do you have cars? Even though they are a depreciating asset, meaning they lose money over time, you still have some value there. How about retirement accounts? IRAs or RRSPs, 401(k)s or Defined Contribution pensions, regular banking and brokerage accounts, credit-card and student loan debt: all need to be factored into the equation.

This information is a powerful retirement tool

Now that you know your net worth and what you are spending per day, you can take further control of your future by figuring out what percentage of your net worth you are spending. Continue Reading…

The grim possibilities of deferring OAS benefits

By Aaron Hector, RFP

Special to the Financial Independence Hub

Before July 1, 2013, Canadians had to begin their OAS pension at age 65. After that date, they were given the option of delaying it for up to five years in exchange for a deferral premium. The deferral premium is 0.6% for each month you wait to start your OAS pension after age 65. The maximum enhancement is 36% if OAS was postponed for the full five years (0.6% x 60 months = 36%). If you are over 70, there is zero advantage to postponing your OAS further – so you should apply now!

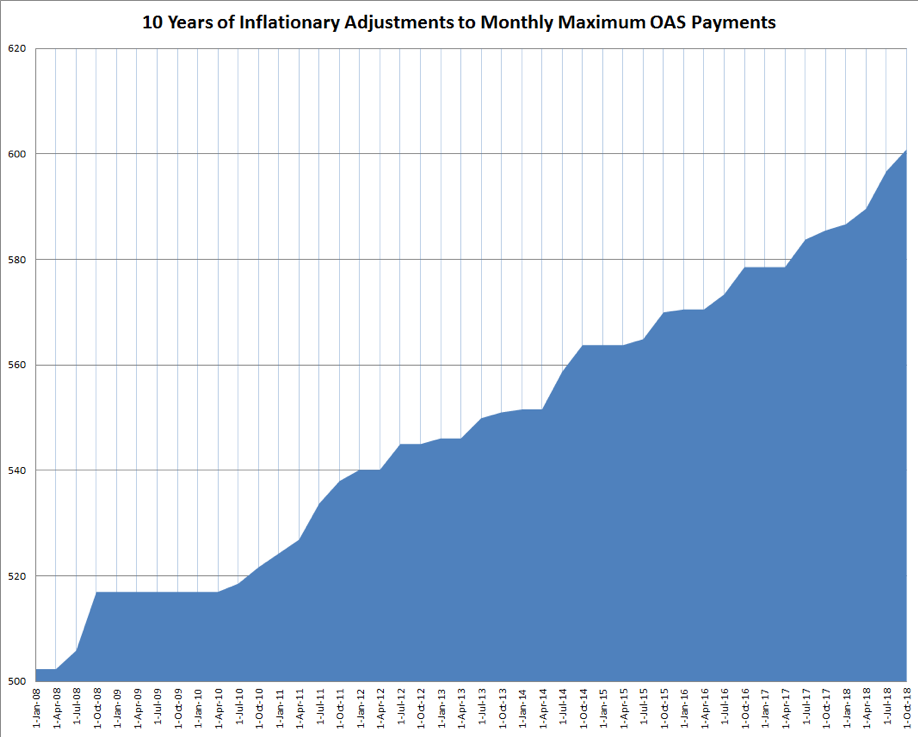
Five years have passed since this change in policy, so those who turned 65 on or after July 1, 2013 and chose to postpone their OAS until age 70 are now finally starting to receive their enhanced pensions. As of December 2018, the ‘typical’ maximum monthly OAS pension  is $600.85, or $7,210.20  per year. For those with a 36% enhancement, theirmaximum payments would be $817.16 per month, or $9,805.87 per year. These payment amounts are reviewed quarterly and are adjusted with inflationary increases over time.

The decision to postpone OAS is both personal and financial, but I would argue that the primary reason for postponing OAS is that it covers off longevity risk. In other words, if you live a very long life, you would be better off delaying OAS and then receiving the larger, more robust pension, for a longer period. For those people with financial assets that they can use to bridge their lifestyle between ages 65 and 70, postponement is something to consider. 

So long as you have the financial resources to make it work, postponing OAS looks like the way to go, so why do so few people take this option? For many, it comes down to uncertainty about life expectancy. What happens if you plan for the long life, but life doesn’t end up being as long as you’d hoped?  Let’s explore a couple of unfortunate scenarios as it relates to OAS postponement.

When Mr. Smith was age 65, he talked with his financial planner and together they agreed on a financial plan which incorporated a life expectancy for him of age 95. Both of his parents were still alive and doing well, and his extended family all had excellent longevity. In his plan, it was determined that he would postpone his OAS to age 70, reaping the rewards of this decision throughout his planned life expectancy. 

Unfortunately, on Mr. Smith’s 67th birthday he was diagnosed with a medical condition and his doctor advised that he’d have a shortened lifespan as a result. 

What can be done?

If you postpone your OAS and later decide that you should have started it earlier, you can apply and request an effective start date that predates the application date. Service Canada will allow you to reach back 12 months (11 months plus the month you apply) and they will send you a lump sum for the retroactive payment. In the case of Mr. Smith, if he applied for his OAS on his 67thbirthday, then he could opt to use an effective date of up to one year earlier, when he would have just turned 66. He would then be paid a retroactive lump sum payment for the one year and receive monthly payments from that point onward. Because his effective start date would be age 66, he could expect an enhancement of 7.2% (12 months x 0.6% per month) on all his OAS payments.

Now, let’s change our scenario. What if instead of being diagnosed with a medical condition at age 67, Mr. Smith falls victim to a sudden and unexpected accident and dies at age 67. The proverbial bus. He had never received a single dollar of OAS pension income. This is a sad situation but, unfortunately, it does occur time and time again. 

Is there anything that can be done in this circumstance? Mr. Smith is no longer around to even apply for his OAS. Are all entitlements simply lost forever?

Something canbe done. The rules are technical, and as such, I will simply quote the Old Age Security Act.

Application for pension by estate, etc.

  • 29 (1) Despite anything in this Act, an application for a pension that would have been payable to a deceased person who, before their death, would have been entitled, on approval of an application, to payment of that pension under this Act may be made within one year after the person’s death by the estate or succession, by the liquidator, executor or administrator of the estate or succession or heir of that person or by any person that may be prescribed by regulation.
  • Pension payable to estate or other persons

(2) If an application is made under subsection (1), the pension that would have been payable to a deceased person referred to in that subsection shall be paid to the estate or succession or to any person that may be prescribed by regulation.

  • Application deemed to have been received on date of death

(3) Any application made under subsection (1) is deemed to have been received on the date of the death of the person who, before their death, would have been entitled to payment of the pension.

http://laws-lois.justice.gc.ca/eng/acts/O-9/page-11.html#h-30

The final paragraph quoted above (subsection 3) is important from a planning perspective because it indicates that a retroactive lump sum OAS payment would qualify to file these amounts on a “Rights or Things” tax return. This is an optional tax return that can be filed to include amounts that had not yet been paid to the deceased person at the time of their death, but would have been included in their income when received. 

When the optional Rights or Things tax return is prepared, it would include items that are “receivable” at death. Common examples of receivable income would be OAS or CPP payments that are scheduled to be paid in the month of death, but are received after the specific date of death. Other examples would be dividends that have been declared and recorded but not yet paid to shareholders, and wages that have been earned by an employee but not yet paid by the employer. 

However, in this situation, we are considering an entire year of retroactive OAS payments being eligible for entry on a Rights or Things return. This is important because in the year of death, deceased individuals (and particularly those without a surviving spouse) will often have large amounts of taxable income in their final tax return from the deemed realization of capital property and the deemed disposition of RRSP or RRIF plans. Under normal circumstances, this high tax base may result in the OAS pension being either partially or fully clawed back. However, because the income is usually minimal on a Rights or Things tax return, it’s likely that in this unique situation the entire OAS lump sum amount could be preserved. This would be a rare tax win in an otherwise unfortunate situation.

At only five years in, and with just one five-year postponement cycle complete, the OAS deferral program is still relatively new. As a result, cases such as these have not yet occurred that often – nor have they gained much media attention. But make no mistake; the scenarios considered here will become an unfortunate reality for many Canadians. So, if you’re planning to postpone your OAS, you should include some precautionary measures in your financial plan.

One solution to consider would be to instruct your executor to make a post-death OAS application and subsequent Rights or Things tax filing. This instruction could possibly be made within your Will, but it would likely be better suited within a Memorandum of Wishes or in an estate administration guide. You could consult with your estate lawyer for their recommendation on the matter.

Similar situations could result from someone postponing their Canada Pension Plan (CPP) payments, which can be taken as early as age 60 at a reduced amount, at age 65 for the baseline amount, or as late as age 70 with an enhanced amount. The difference here is that under CPP legislation an application for retroactive payments can only be made when the deceased passed away at age 70 or older. 

There is absolutely no incremental benefit for waiting beyond age 70 to begin taking CPP (or OAS) payments. So, it seems highly unlikely (though not impossible) that someone would be over the age of 70 and not have already applied for their CPP benefits. With OAS, on the other hand, it’s easy to think of common situations where someone could be older than 65 without having applied yet.

If you or a loved one is postponing OAS payments, it’s important to know about the different planning options you can consider in case life doesn’t play out as expected. A qualified financial planner can lay those options out for you.


Aaron Hector has been a consultant at Doherty & Bryant Financial Strategists, a subsidiary of T.E. Wealth, for over a decade. He provides comprehensive financial planning to high-net-worth individuals and families in Western Canada, and has extensive experience in executive compensation plans, retirement planning, and income tax reduction strategies. 

This blog originally appeared on his site on Dec. 10 and is reproduced on the Hub with permission. 

See also the Financial Post column that ran Dec. 20, 2018 by Jonathan Chevreau that was based on this blog.