All posts by Financial Independence Hub

Make Investing great again …. one day? Part 1

By Aman Raina, Investment Coach, Sage Investors

Special to the Financial Independence Hub

My motivation in starting my own practice to teach and engage people on investing revolved around financial literacy. I thought that if I could improve someone’s financial literacy, they will have a better chance at becoming a successful investor. I was always a big supporter of financial literacy programs, especially in schools. It made sense and I thought it was the right thing to do.

The reality is over the years I’ve learned and witnessed first-hand that while noble and done with good intentions, financial literacy programs just don’t work. A revolving door of programs, a lot of them government and industry sponsored have been rolled out over the years, starting out with enthusiasm and then just petering away in obscurity.

Here in Canada, we even have a Financial Literacy Commissioner , which acts and cheers Canadians into becoming more financially literate but to no avail. We even have a Financial Literacy Month late every year: So much effort, again all with good intentions, will be put into improving financial literacy but it just doesn’t seem to stick. 

Millennials scared of investing

So queue the latest attempt at cracking the financial literacy daVinci Code. A 42-page report commissioned by the Ontario Securities Commission, prepared by a dream team of consultants and personal finance thought leaders. The report attempts to answer why people, specifically Millennials, are not investing and what financial institutions can do to get them to invest. 

The report does a good job of capturing the pain points of why Millennials are not investing. They’re scared of investing. They feel overwhelmed by the process. They often freeze when trying to make a decision. They don’t know how to start and take that first step. I hear these thoughts very often from people I’ve worked with, and not just Millennials. 

The report outlines some broad solutions and strategies that financial institutions could adopt to better engage the Millennial cohort. The problem is the solutions are drowned out in consulting jargon and don’t effectively address those pain points that people are consistently complaining about. Often I’ve seen many programs rolled out that don’t articulate a clear, consistent message that speaks to the pain points. Here’s what OSC report came up with:

Make Investing a Priority

This is an attempt to address the pain point of establishing the first step into investing. The report believes that the first natural step to expose people to financial concepts is in the classroom. Teach the concepts early on, maybe high school and it plants a seed that will carry them into adulthood.

It seems like common sense. Ontario high schools have just started rolling out a financial literacy curriculum. The problem is it’s been done and it doesn’t work. A study published in the journal Management Science by John Lynch, a consumer psychologist at the University of Colorado’s Leeds School, compiled the results of more than 200 studies of financial literacy programs, adjusting for subjects’ family background and personality traits that had been ignored in the previous research. The study found that studying financial literacy has a “negligible” impact on future behavior and that within 20 months almost everyone who has taken a financial literacy class has forgotten what they learned.

Students don’t retain the information. The reality is the information during that period in our lives goes through one ear and out the other. It’s just not a priority…at that time. The report cites an excellent example by one of the participants, who said “at 15 years I’m thinking only 3 months ahead and when I got to 22 years, I was thinking years ahead”. Teaching financial literacy in high schools intuitively makes sense, but at that age, we’re not thinking about the future. The future for me at that age was thinking about what I was doing after school on Friday with my friends. I’m not a psychologist but I think Teenagers aren’t wired for it. Their brain is still developing. It’s only when people experience adversity (i.e. living on their own, managing their paycheque for now and the future) that motivations for improving their financial knowledge crystalize. 

Validation by Social Circle

The report suggests getting out to where Millennials are hanging out and engaging them about the importance of investing. The thinking is Millennials are more likely to follow what Continue Reading…
How small business owners can survive a security breach


By Gloria Martinez

Special to the Financial Independence Hub

Photo by Markus Spiske on Unsplash

There are myriad reasons why a malevolent actor would want to breach your small business’ data and info and/or attempt to defraud your company. Money (holding business info or operations ransom) is a big one, but your business also holds plenty of useful, sensitive data on customers, clients, business partners, trade secrets, and finances. Whatever the reason, data breaches are becoming the norm — not the exception — for small businesses around the world, and the cost can be substantial. Here’s what to do if you’ve been hit.

Plug the leak and and figure out what happened

If you are a network security pro or have your own in-house team that can perform this task, that’s great. However, the majority of small business owners feel lost and adrift following a security breach. The smart first step is to hire digital forensic specialists. These experts can do most of the technical work for you, from plugging up the initial breach point, tracking down the responsible parties (which is key for any sort of legal action), and finally doing the necessary legwork to shore up your defenses (so it won’t happen again).

This is also the time to contact your service providers. It’s highly unlikely that your breach exists in a vacuum. We’re talking your point-of-sale software company, internet provider, credit card processor, and accounting firm, so it’s wise to take the appropriate actions.

Boost security and consider Legal Representation

Your next step is to do what you can on your end to improve your data security. Employ the obvious, FTC-recommended actions like changing company passwords, security codes, and physical locks (yes, data breaches can occur when unauthorized people have actual, physical access to your workspace). Then, as the FTC suggests, “you may consider hiring outside legal counsel with privacy and data security expertise. They can advise you on federal and state laws that may be implicated by a breach.” Legal representation is vital for two major avenues — either taking action against those responsible or defending your business from liability (compromised personal data can put you in a serious legal pickle).

Make changes to prevent future breaches

A few solid ways to protect your small business from future security issues include separating personal and business accounts, beefing up your security and data permissions, and retraining employees about proper security protocols. The sad fact is that many security breaches are due to employees — whether malicious or unintentional. That’s why it’s absolutely critical that you take the time to carefully screen your hires to make sure they are reliable and trustworthy. This means holding quality job interviews where you ask the right questions to get an accurate sense of the candidates you’re vetting.

Notify those affected

Legal considerations aside (notification of a data breach may be forced based on state laws), being honest and upfront with your customers, clients, and business partners is always a good idea. It builds trust, for one. It also allows them to shore up things on their end, as security breaches are rarely just limited to the primary target.

Small businesses are generally easy targets for malicious actors for a variety of reasons. For one, they simply do not believe they are big enough to be hacked or breached. They also don’t have the time, money, or resources to devote to major cybersecurity. Knowing that you are vulnerable is half the battle, and the other half is staying calm but decisive when something does happen. Take these steps so you can recover and move on from a security breach.

Gloria Martinez loves sharing her business expertise and hopes to inspire other women to start their own businesses. Her brainchild is Womenled.org. Gloria’s vision is to help all women advance in the workplace and celebrate their achievements.

The Investing Year in Review: 2018 was not Financial Armageddon

By Dale Roberts

Special to the Financial Independence Hub

cramerpic
Mad Money with Jim Cramer – Wikipedia

Everybody relax. Chill out, or you can Chillax. Is that a word that is still in use?

For all of the noise and hysteria, 2018 was not all that bad a year for Canadian and U.S. investors. But if you listened to the financial press and were unfortunate enough to watch too much BNN or perhaps the more frenetic and desperate U.S’ investment shows that look more like a Football halftime show, you might think the world had ended for  Investorkind.

Seriously, turn this stuff OFF. Unless you’re able to watch and laugh, then carry on. As I like to write, all of this financial and investment fluffery is for entertainment purposes only. 

2018 was not that bad: all normal and expected market behaviour

When I looked at my accounts at the end of 2018, I saw that my personal RSP account was down just slightly at about 3%. My wife’s personal RSP and spousal RSP accounts were both positive to the tune of about 2-3%.

Hardly Armageddon.

Here’s one of my wife’s accounts. It’s a one-year chart so it shows the slow start to 2019. The purple line is my wife’s account (that I manage), the dotted blue line is the Canadian stock market – the TSX composite.

joan's account

That does not look like panic time. More like snooze time with not much going on.

The account uses the basic building blocks also largely followed by the Canadian Robo Advisors,and mostly by those who create a well-balanced ETF portfolio. You can find some basic models on my ETF Model Portfolio page.

AssetAllocationSnip

For my wife’s accounts, and for all of our accounts, I use Canadian stocks, U.S. stocks and Canadian bonds. I mostly do not use International stocks. Core indexers might say that is a ‘mistake’, you might be best served to stick to the script. I will certainly be back with articles on International Diversification for Canadian investors.

Not including international stocks added a slight boost to our portfolios in 2018.

International Developed Markets (iShares XEF) was down 6.6%.

US Total Markets (iShares XUU) delivered a positive 2.9%in 2018 thanks to the strong US Dollar. Canadian investors see that currency boost.

The Canadian Market (iShares XIU) was down 7.7%.

The Canadian Bond Market (iShares XBB) was up 1.3%.

Put it all together in a Balanced Portfolio 

We can see that two of the assets were in positive territory, two of the assets were in negative territory. Typically your asset mix will largely determine your returns. A good benchmark is the new Vanguard all-in, one-ticket portfolio solutions. For more on those wonderful funds please have a read of Jonathan Chevreau’s  Continue Reading…

Here’s what home buyers can expect in 2019

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

2018 has certainly been a tumultuous year for Canadian real estate: tougher mortgage rules, rising interest rates, and sky-high rent prices have squeezed buyers and tenants in markets across the country. Will next year be one of stabilization sales and prices, or will 2019 usher in more uncertainty for those aspiring to be homeowners?

Let’s take a look at four scenarios that are likely to materialize in the new year.

1.) Count on slower sales

New build and resale activity for condos and houses for salehave slowed across Canada this year, and have impacted various markets for a variety of reasons; in Ontario, buyers continue to grapple with the effects of the Fair Housing Plan, a package of policies introduced last March, while Vancouver is dealing with price fatigue and new taxes that target investor and foreign buyers. Smaller western markets, such as Calgary, are slogging through a supply imbalance, which puts downward pressure on prices.

However, all housing markets have been reeling from the effects of the federal mortgage stress test, which was put into effect on January 1 (a year ago). Combined with rising interest rates, it has taken the steam out of real estate activity and reduced buyers’ purchasing power as they must prove they can qualify for a mortgage roughly 2% higher than the rate they’ll actually get from their bank.

According to recent analysis from the Canadian Real Estate Association, it won’t be a cheerier picture in 2019: sales are actually expected to hit a nine-year low, softening 0.5% from 2018, which has already absorbed an 11.2% decline at 548,200 homes sold.

“In 2019, home sales activity and prices are expected to be held in check by recent policy changes from different levels of government, in addition to additional interest rate increases,” CREA states in its November release.

2.) A temporary hold on rate hikes

Good news for borrowers, but not so much for the economy – despite strong expectation that there would be multiple Bank of Canada (BoC) rate hikes this year and next, recent economic events have effectively derailed the central bank’s upward tear, meaning variable-rate mortgage holders and new applicants will get a temporary reprieve on their cost of borrowing.

The BoC, which controls inflation and the cost of lender borrowing by increasing or decreasing its trend-setting Overnight Lending Rate, opted to leave it untouched in its December announcement, despite hiking in October to 1.75%, as a new U.S. – China trade skirmish and domestic oil price plunge have raised doubts on economic stability. 

It has been said throughout the year, in response to early strong inflation growth, that the BoC intended to eventually raise rates to a “neutral” range, between 2.5 – 3.5% by 2019. It is unclear at this time if it still plans to do so over the coming year.

3.) Rents to keep on rising

Sorry, tenants – there isn’t any sign of relief in store for you. 

The price of rent, especially in Canada’s largest urban centres, has been a central theme in 2018; rental MLS listings in Torontofor one-bedroom units rose 9.5% this year to an average of $2,163, according to the Toronto Real Estate Board. A CMHC rental report also reveals that, across the nation, rents have increased 3.5%, with the largest hikes in Vancouver (+55%), and Toronto (+5.2%). Rental vacancies also shrunk in most major markets; Toronto and Vancouver both have roughly 1% of rental stock available, while the Quebec market saw its rate plunge from 3.4% to 2.3% in the span of a year.

And they’re expected to keep on rising by an average of 6% next year, according to the National Rent Report released by Bullpen Research and Consulting, partnered with Rentals.ca, as employment, migration, and desirability factors continue to fuel demand for units.

4.) How can buyers prepare for 2019?

For those sitting on the fence regarding their home purchase, the time to act is now; connect with a mortgage professional to lock in a pre-approved rate before the BoC resumes its hiking mandate. Be prepared to encounter fewer listings in the new year, as many sellers may not feel the climate is the right one to list their home. However, with the pace of price growth expected to soften in many markets, it could be an advantageous time to get onto the property ladder at a lower price point than before. It’s a great idea to work closely with an agent when the market is slightly down, to determine if it’s the best time for you to make a move.

Penelope Graham is the Managing Editor of Zoocasa.com, a leading real estate resource that uses full brokerage service and online tools to empower Canadians to buy or sell their home faster, easier, and more successfully.

The Benefits of Travel

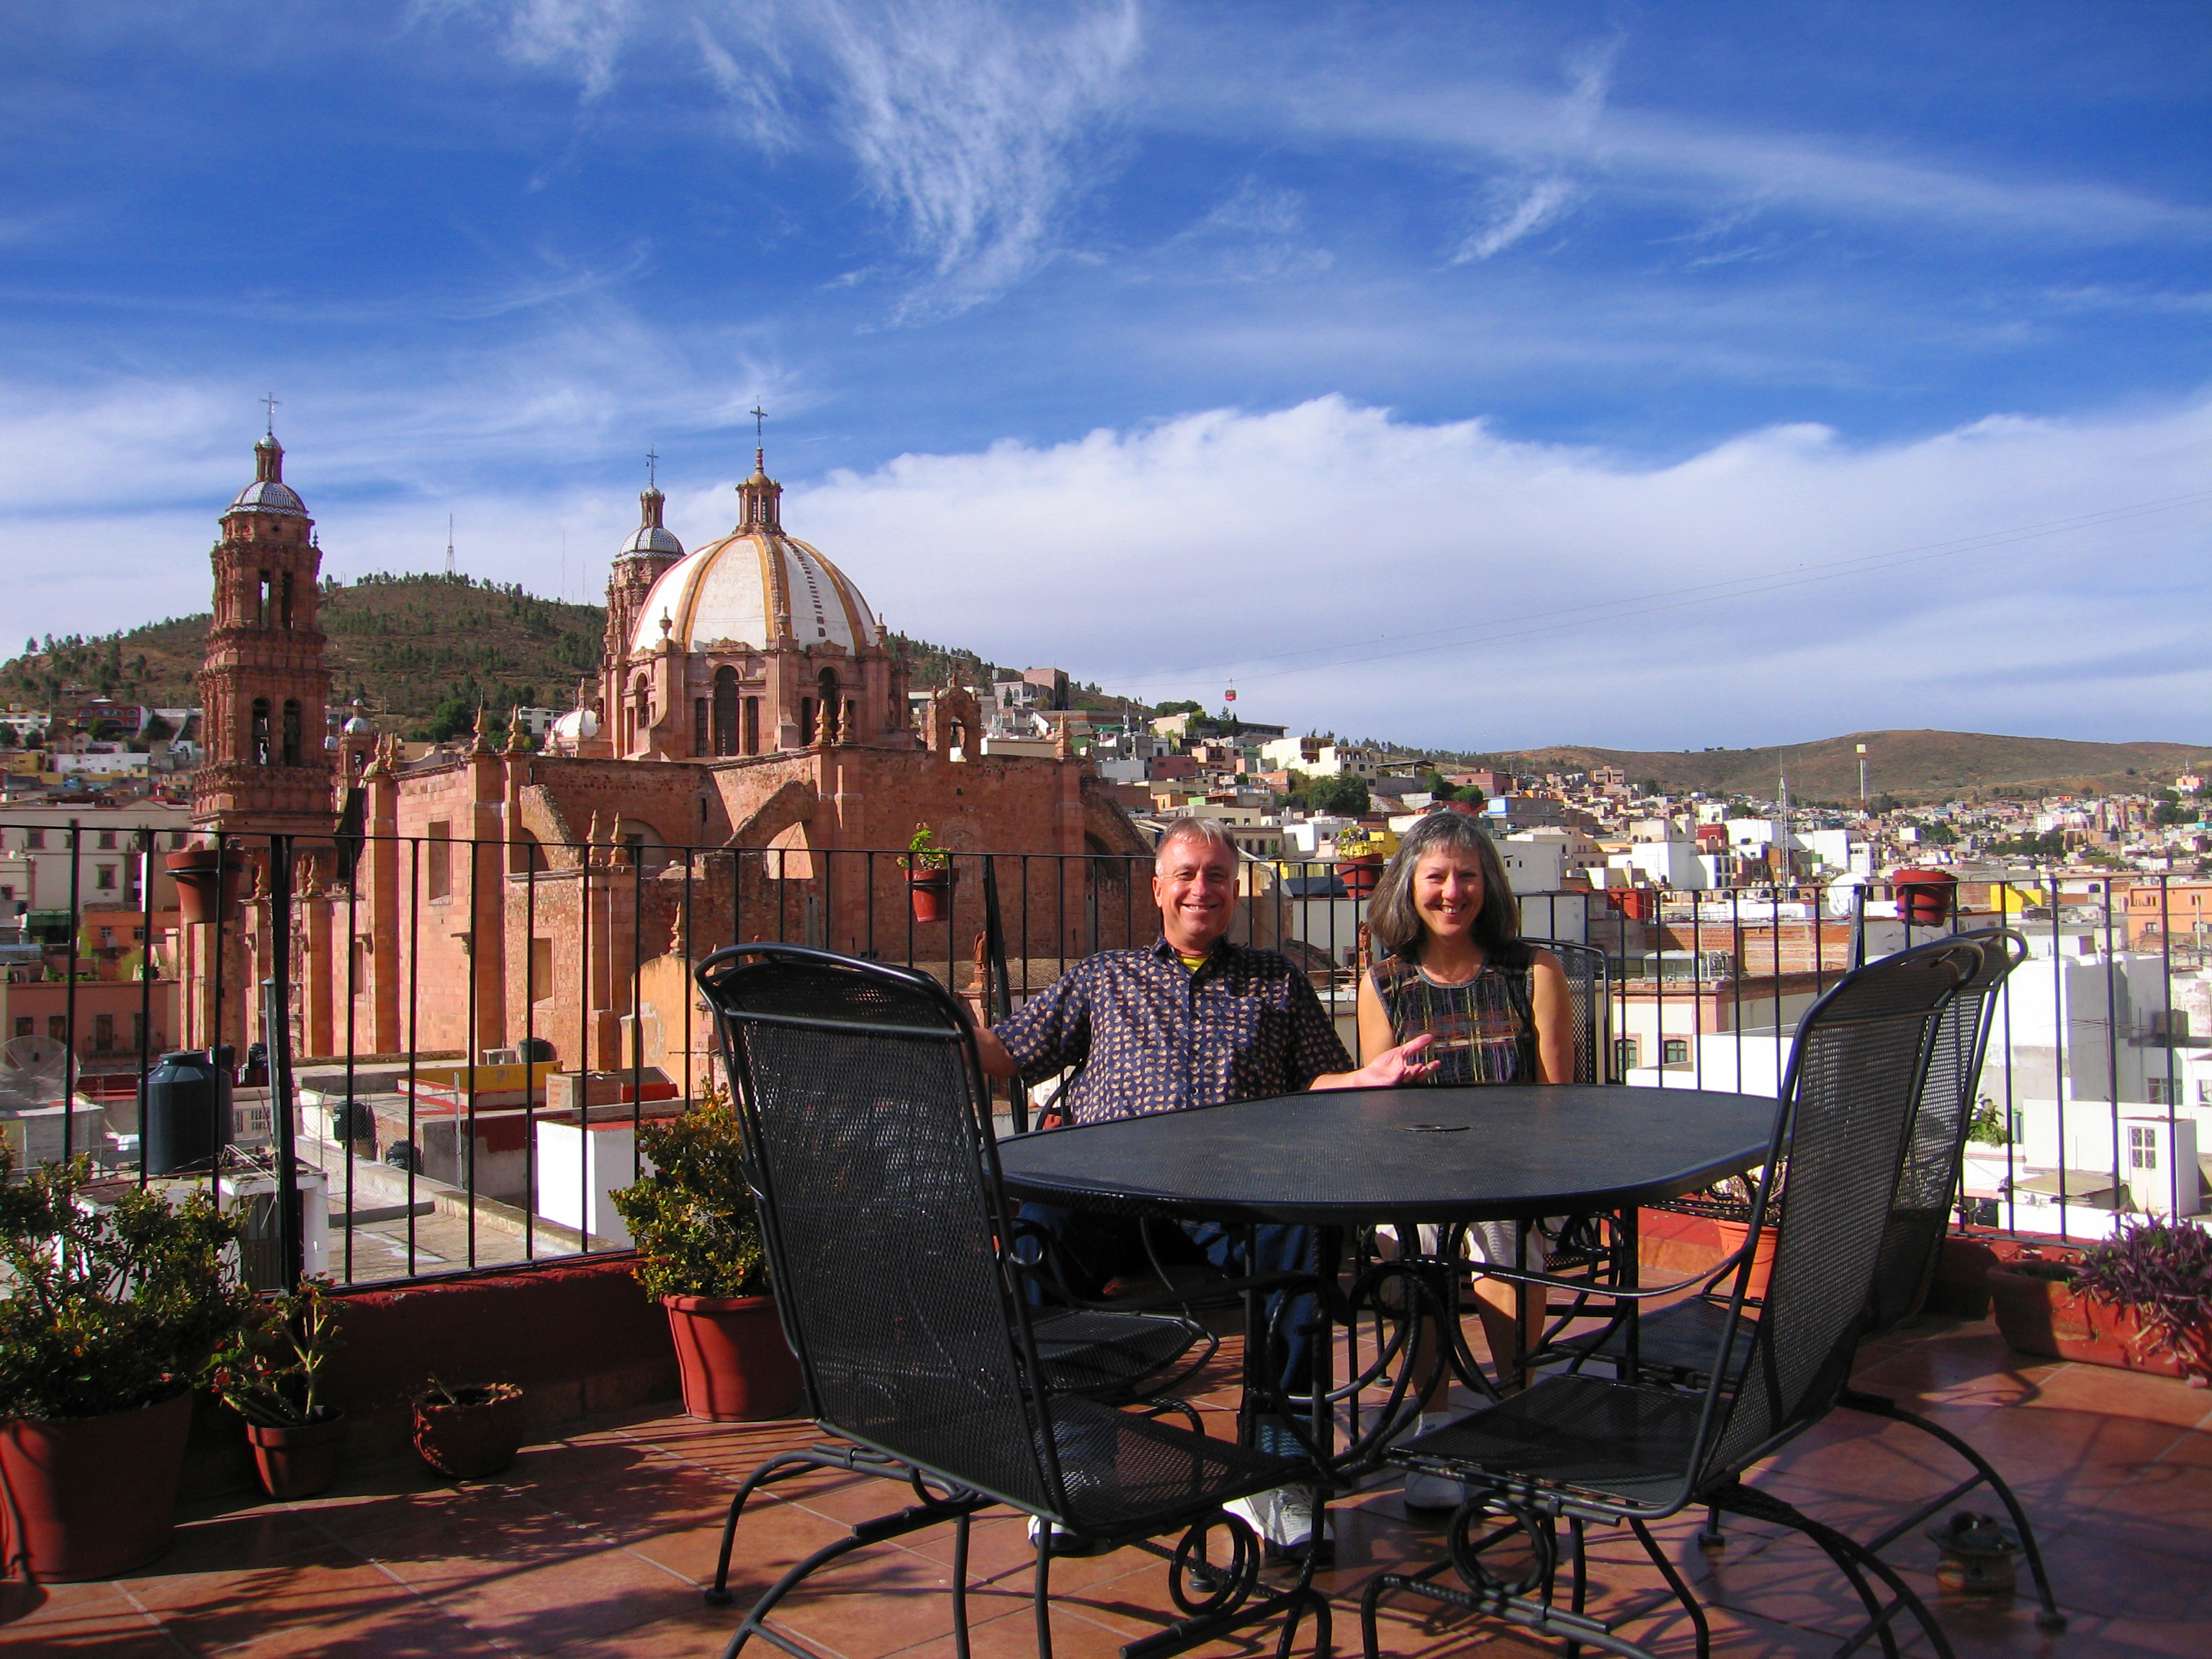
Billy and Akaisha take in the view from their hostel in Zacatecas, Mexico

By Akaisha Kaderli

Special to the Financial Independence Hub

We understand that not everyone likes to travel. No doubt it can be challenging, but there are significant benefits if you choose to enliven your routine with a little excursion.

Traveling makes you smarter

From the beginning of choosing a location, packing your suitcases and figuring out the logistics of who will water your plants or sit with your pet, traveling takes you out of your routine. Anything new and different like this that engages your brain causes new neurological pathways to grow.

Learning a new language, taking a cooking or painting class while on your trip and meeting new people all place you in unique situations, and your brain strengthens.

Traveling is healthy for you!

Traveling makes you strong

For some people, all these new patterns outside the everyday routine can be perceived as a hassle. Yes, and that’s good! We learn flexibility, creativity and self-reliance. Those are great attributes to have and they are useful to daily living.

Flexibility of mind, finding new solutions to new challenges and our sense of who we are and how we cope all get stronger.

Traveling helps you become an interesting story teller

When things don’t go according to plan, those seemingly challenging circumstances make for the best stories!

If everything goes perfectly on your trip or vacation, and people ask “How did you enjoy yourselves? How was your trip?” then all you can say is “Great!” Continue Reading…