All posts by Financial Independence Hub

Retiring early: the hardest part is waiting for your spouse

P1130132

By Dale Roberts

Special to the Financial Independence Hub

Just over 6 months ago I left a job that I truly enjoyed and moved to what I like to call a new life-work stage. I’m not retired; let’s call it a stage of semi-retirement. My RSP and TFSA portfolio was not retirement ready; it’s only halfway there. The acronym FIRE has become very popular over the last few years:  Financial Independence Retire Early. I guess I would fit that definition to some degree, but I don’t have that financial part down yet.

I still need to make half a living, and that’s by design. 

Many will attempt to sprint to the finish line of retirement. That is, they will work hard and as much as they can so that when they reach that magic age and that magic number (considerable retirement portfolio or pension) they can stop and rest and enjoy that financial freedom. That sounds wonderful, but perhaps troublesome for many. We hear of too many stories of retirees falling ill or passing away within the first few months or years of retirement. There are many physical and biological and psychological reasons for that unfortunate reality. I’ll cover that in a separate article.

Many will take the halfway-to-retirement route and instead of a sprint to the finish line, they’ll stroll to the finish line. That’s me, strolling. The thing is I am walking this walk alone; my wife still works and she wants to work for another 4 or 5 years. She’s ‘not ready to retire.’ And that’s good, we do need her income for now, until I can start to earn half a living. For us to fully retire we would need to downsize from our accidental investment: our Toronto home. Next year we’ll have our 2 kids in University and we want to keep our home as a base and a familiar comfort zone. This is not the time to take off to the beach.

First 6 months of semi-retirement. 

Out of the gate the new work-life stage was nothing short of incredible. Last June I packed up the laptop and set up shop in Prince Edward Island. My first home office was a little beach cottage in Stanhope. It was my ‘workcation’. I launched my site from the wonky Wifi of Lyon’s Cottages. The property manager Ken did everything he could to keep that Wifi signal chugging along for 3 weeks.

It was an incredible period, being able to hang out with my daughter who is just finishing up her undergrad work ‘on the island.’ My wife and son joined us for a week of family vacation. That’s a whirlwind of new activities and emotions. Leaving your career and co-worker friends, starting a new business and taking off to Canada’s most lovely beaches. There was a lot of ‘new and exciting’ all rolled into a few weeks.

That said, I got a good taste of that ‘waiting.’ And as Tom Petty (RIP) sang, ‘The Waiting Is The Hardest Part.’ While I have a very generous amount of loner in me I was surprised at how uncomfortable a feeling that was – that working alone and being alone for many hours on end. I couldn’t wait for my daughter to finish work and head up to the cottage for dinner and a walk along the beach.

I couldn’t wait for the rest of the family to join us for that week of family vacation.

I was offered a very quick introduction to the ‘feeling of retirement.’ And I can tell you that is feels a lot different when you are doing that retirement thing – alone. It’s well-known that we have to have a solid plan when we retire. To run to that retirement finish line and then wonder what the heck you are going to do is at the very least misguided. Your time will not magically fill itself with wonderful and fulfilling activities.

When we are working our week is filled with tasks that need to get done on time. We usually know how to fill that time and we often wish there were more hours in the day or more days in the week. Retirement is not much different. We have to fill our days and weeks with tasks and chores and accomplishments. We need some structure. You likely will not be on vacation most weeks or months. Vacation is the easy part, and that may not feel all that different to the vacations that you took in your working life.

That said, I would guess that we can start to take our vacations for granted when those vacations are a regular event. We humans can get used to (and bored with) just about anything. I love to travel with family, that might be my most cherished time. But I think I could get somewhat bored of endless travel, or at least the trips could lose some of the magic. Vacations feel great in our working years because there is anticipation and there is an end date.

Retirement has to have meaning and purpose. 

The concept of purpose might be the most important consideration. That word gets used a lot by those who study retirement and retirees. When we lose our purpose that can send a lot of negative signals to our brain and our body. And certainly that purpose can take many shapes and forms. A retiree might look after the grandkids on regular basis, take care of older parents, volunteer, work on a side job that includes a useful mission.

If you are retiring alone for a few years, waiting for your partner, you’d best have a very good plan built around that purpose. And you might want to fill your 9-5 Mondays to Fridays with enough contact with others – engaging human contact. Free time to do ‘nothing’ loses its appeal real quick. It’s not all that special when free time is followed by more free time.

Make the most of your time when you are waiting for your spouse to retire. I’d suggest that the real retirement starts when you are both retired. But you can make the waiting years very enjoyable and fruitful and meaningful.

Retirees who are doing it right. 

Fritz Gilbert at Retirement Manifesto retired the same month, June of 2018. He offers a wonderful blog that details his and his wife’s FIRE journey. Here’s 6 Lessons From The First 6 Months of Retirement.

You’ll find their retirement consists of a lot of structure and a lot of purpose. There’s regular exercise. There are Grandkids and dogs to take care of. It’s busy enough. There’s lots of room for vacations. As much as one can try to prepare, Fritz is also surprised by the new venture known as retirement.

Fritz Retirement

I’m Lucky

I semi-retired with a purpose, my blogand other writings that help Canadians with their own search for FIRE and other financial goals. That’s all very exciting and interesting  and rewarding. But I know I need more. I need to get ‘out there’ more to promote the blog and mission and to reach Canadians face to face. I will also add some volunteer work for more tasks and greater purpose.

My first 6 months of semi retirement reinforced what is well-known, that being financially prepared is only half of the prep work that is required for a successful and happy retirement. Retirees need a plan. A newlife plan for your newlife.

Money + Plan =  FIRE-AH.

Financial Independence Retire Early – And Happy.

Kindly hit those share buttons for Twitter, Facebook and Linkedin at the bottom on this article. And for my 6 month anniversary present, kindly click Follow Cut The Crap Investing at the very bottom of this page.
Dale Roberts is the Chief Disruptor at cutthecrapinvesting.com. A former ad guy and investment advisor, Dale now helps Canadians say goodbye to paying some of the highest investment fees in the world. This blog originally appeared on Dec. 11, 2018 and is reproduced here with his permission.

Home financing options for credit scores

By Michael Plambeck 

(Sponsored Content)

It’s important to go over all your options in regard to home financing to ensure you know what your options are and what’s available to you. This is especially crucial if you are a first-time buyer. Though this can seem like an overwhelming process, knowing what your options are based on your credit score, what types of help are available, and how you can improve your credit score if it’s poor or bad, is the best way to figure out what to do.

How to check your credit score

There are many ways to check your credit score to figure out where you are currently at. You can use a number of institutions and resources to check what your credit score currently is, such as using FICO,or Equifax.

It’s never a bad idea to regularly check all of your credit reports in order to be completely sure that the information is both complete and as accurate as possible. This will help you to know where you need to make improvements, how you can do it, and what your situation is at that point in time. 

Low credit scores and what your options are

Having a low credit score sends red flags to lenders and deems you a credit risk. In short, this will make it very difficult to get a proper credit loan. 

Here is a quick list detailing the range of credit scores and what they mean:

  • 300 – 499: Bad credit
  • 500 – 579: Poor credit
  • 580 – 619: Low credit
  • 620 – 679: Average credit
  • 680 – 699: Good credit
  • 700 – 850: Excellent credit

Having a high credit score means you should have no problem getting a loan from your bank or your credit union. Having a middle credit score, which is a credit score from average to good, you have a wide variety of options available other than your bank or credit union if they deny your application, such as quick loans or by going online.

If you have bad to poor credit, getting credit is going to be very difficult. The fees and interest rates will more than likely be higher than what you can afford, but that’s only if you can get approved at all.

You can do your best to go through the Federal Housing Administration  in order to get a mortgage loan, but they only grant loans through FHA-approved lenders, which may pose a problem. They have a list of requirements that must be met in order to get an FHA mortgage loan, which are listed below for you:

  • A FICO score between 500 to 579, which equals a 10% down payment
  • A FICO score of 580 at the very least, which equals a 3.5% down payment
  • Debt-to-income ratio of under 43%
  • Mortgage Insurance Premium (MIP)
  • The home in question being the primary residence of the borrower
  • Proof of employment and a steady stream of income

However, there are options you can go through in order to get the approval you need for a home loan if you’ve exhausted all your other options, which include going for an FHA mortgage loan. Homeloansforall.com, for example, will help you get approved even if you have bad credit and find the resources you need based on your city and state.

No matter what your credit score may be, the financing options you have in front of you, and what the future may bring, once you are approved for any type of loan, it’s important to keep up with your payments in order to keep the home. 

To help keep up with your mortgage payments and be clear of the debt, check out how to pay off your mortgage in 10 years.

Michael Plambeck, founder and owner of Home Loans For All, bridges the gap between its content team and industry team by being an expert in both areas. Michael is a home loan expert who has worked closely with loan officers and realtors for over four years, and who is engaged in constant continuing education to make sure he’s up-to-date on all real estate laws and regulations.

Suze Orman and the FIRE movement

Photo by QuinceMedia on Pixabay

By Aaron Burdick

Special to the Financial Independence Hub

In a recent interview, Suze Orman provided her opinion about the FIRE (Financially Independent, Retire Early) movement. However, in doing the social media interview, her words were probably taken out of context, and triggered a viral reaction. Everything from Orman being a “shill for the financial industry” to “she doesn’t really want people to be financially independent at all” was thrown around. No surprise, Orman had to step out quickly and put clarity into her words.

First off, Suze Orman makes a point that she’s been advising people to be financially solvent and independent for decades, so she has no outright gut opposition to the idea. Period. But she does add that there should be a balance between spending and saving as well, which is an entirely different idea. Frankly, it’s more about balancing our satisfaction interests versus what we really need to survive and live comfortably. But where the heartburn really kicks in for Orman is on the topic of retiring early. For her, it’s a bit like quitting your job early but having no idea how to pay for health insurance until you reach the age to get Medicare, avoidable and dumb.

What is the Definition of Retirement?

So, it comes down to definitions first. If we are talking about true retirement, for Orman that means stopping working for income altogether. There is no odd job, or a part-time job, or a different job operating a lathe machine; it’s just not working at all for any profit. Second, retirement under the FIRE definition could be 55, but it could be as early as 30 or 40 as well. For the financial planner that Suze is, mathematically, that was pretty much impossible unless one was a millionaire or won the lottery. Mainly, the problem has to do with the fact that people are living really long, and that translates to tens of thousands of dollars needed annually to survive on. Quitting work at 40 or even 50 is just ludicrous.

FIRE’s Definition of Retirement

As it turns out, however, FIRE’s definition of retirement isn’t a complete cessation of retirement. Instead, it involves switching from what you have to do for a paycheck to what you want to do and still earn an income doing it. No surprise, without that clarification, Orman’s original response was not just “no,” but “hell no!” And that caused a kerfuffle on the Internet. In fact, the revised definition is entirely inline with Suze Orman’s general advice direction, pushing people to find what they love doing, but still, earn an income doing it. Some call it FIRE, and Orman calls it Living on Your Own Terms.

So there is commonality with the clarified version of FIRE and Orman’s advice categories. The detail then comes into the “how,” the method used to get from what you have to do for a paycheck to what you want to do. FIRE doesn’t necessarily detail these steps; that’s left up to the user to figure out. This is where Orman finds a gap in the philosophy.

Orman’s Take on Retirement

For Orman, retirement and individual financial independence aren’t about making enough money to quit a job. It’s about keeping stable while finding a life direction more in line with your interests, goals, wants, and happiness. Just getting to retire early with a lump of money isn’t going to translate to happiness per se. And, going back to her financial math, it’s a high risk for even more problems and unhappiness. So, Orman’s not against FIRE per se; but she has an issue with its lack of detail and in that respect, being misleading.


Aaron Burdick is a blogger and personal finance enthusiast with slight “addiction” of planning and organizing whether it’s budget, business or just life in general. Finances, real estate, budgeting and new technological solutions are not the only talking points, that he has his heart set on. Passionate about life. he studies and writes about environmental changes, human rights and quality of life. He is also the proud owner of a Golden Retriever. When he’s not writing articles he’s with his best friend playing fetch or cycling around the streets of Louisville. 

Is your neighbourhood in a Sellers’ Market for homes?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

Deciding whether or not to get into the real estate market? While budget, location, and home type will be among your top considerations, there’s another metric that can help inform your move: the buyers’ conditions in your desired neighbourhood.

Understanding whether you’ll be dealing with a sellers’, buyers’, or balanced market is key to crafting your offer or listing strategy. Those trying to buy a home amid tight sellers’ conditions will need to be ready to participate in bidding wars, for example, make aggressive bids, and be prepared to drop offer conditions to be competitive. Entering a buyers’ market indicates more real estate inventory and choice for buyers, and often the room to negotiate.

Sellers are also wise to take these conditions into account as listing during a relaxed market may mean adjusting pricing expectations; it could be a better idea to wait for the market to firm up before trying to sell your home.

What is a Sellers’ Market?

But what actually classifies a market as buyers’, sellers’, or balanced? A common misconception is price. However, while prolonged conditions will eventually influence home values, a buyers’ market doesn’t also indicate better affordability, and vice versa. Rather, these conditions are determined by a metric called the sales-to-new-listings ratio (SNLR).

The SNLR is calculated by dividing the number of sales by the number of new listings within a specific housing market over a period of time. It reveals how many of the homes listed for sale are selling within that time frame, and sheds insight into how competitive the market is for buyers and sellers. According to the Canadian Real Estate Association (CREA), an SNLR between 40  to 60% is considered a balanced market, with below and above that threshold indicating buyers’ and sellers’ conditions, respectively.

Getting the Bigger Picture

A great thing about looking at SNLR is you can get as local as you need to with your market assessment; a buyer or seller can understand what’s happening at the neighbourhood level, whether they’re looking for condos for sale in downtown Toronto, or Etobicoke homes for sale.

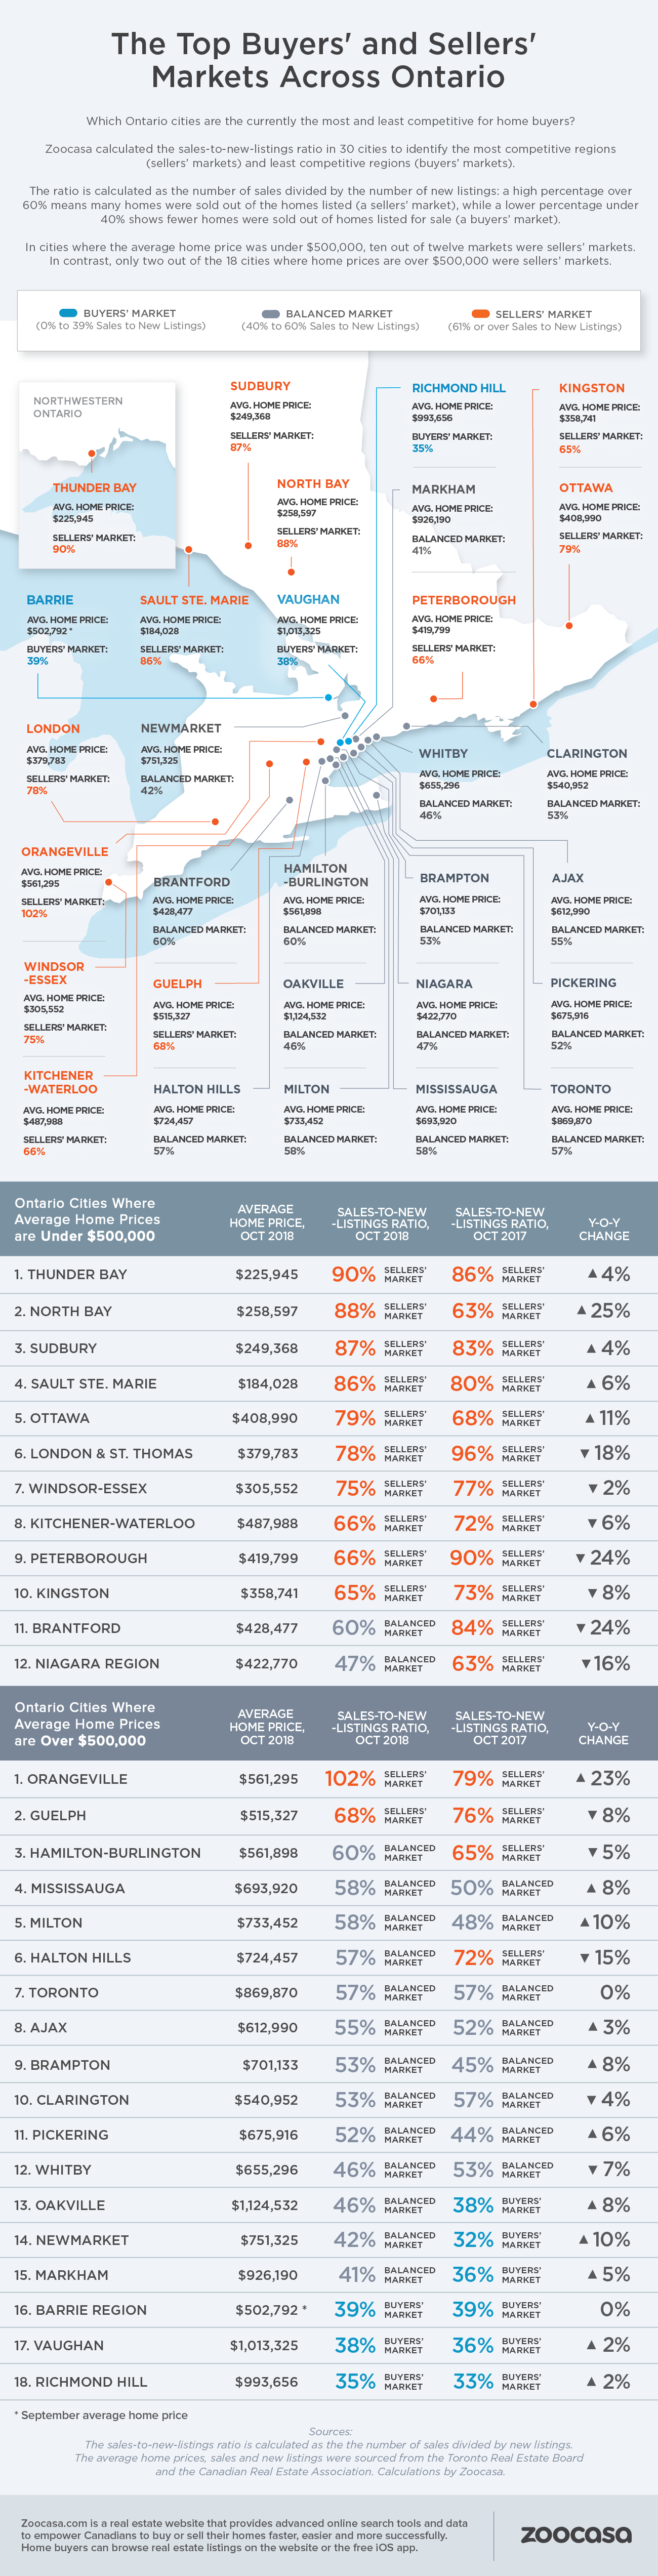
The SNLR can also be used to measure activity over larger geographic areas. At a provincial level, Ontario’s housing market remains in balanced territory, with an SNLR of 56%. However, this ranges quite widely throughout the province with some surprising results, according to recent data compiled by Zoocasa; a look at October sales and new listings numbers reveals Ontario’s most affordable markets are actually among the tightest in terms of sellers’ conditions.

Sellers’ conditions in Ontario’s most affordable markets

In markets where homes sell for less than $500,000, 10 of 12 municipalities could be considered sellers’ markets. Continue Reading…

Major credit-card mistakes to avoid over the holidays


By Hyder Owainati

Special to the Financial Independence Hub

The holiday season is now in full swing, and for most Canadians, that means ramped up spending and a large end-of-the-month credit card bill. While not inherently bad – as a credit card that’s paid off in full and on time can offer valuable cash back or travel points – there is a delicate line that must be tread. 

Here are some of the major credit card mistakes you’ll want to avoid making over the busy holiday shopping season to ensure your card is working for you (and not the other way around).

Not following a budget and carrying a balance

Without a holiday budget in place, you’re more likely to spend beyond your means and carry a balance on your credit card. You always want to avoid a situation where you don’t have enough money in the bank to pay off your monthly credit card statement, as carrying a balance will lead to costly interest charges on top of the money you already owe.

When setting a holiday budget, make sure you set a maximum dollar amount you can spend, list out how many people you plan to buy gifts for, and factor in other costs that are likely to spike during the holidays, such as travel, gas and food for social gatherings. 

Taking out a cash advance

Using a credit card at the ATM for a cash advance is almost always a bad idea and should only be accessed in cases of real emergencies when paper money is a necessity – not holiday “shopping emergencies.” 

Cash advances are short-term loans that are accompanied with high fees, and unlike other purchases made on a credit card, may charge interest that accrues immediately with no grace period. So, stick to paying with cash that’s already in your wallet or charging your credit card at the sales counter over cash advances.

Using a high interest credit card

Several Canadians are starkly self-aware of that fact that they will overspend during the holidays. According a survey conducted by Ratehub.ca, 1 in 3 people anticipate they will carry a post-holiday credit card balance while a separate survey from CIBC found 52% of Canadians expect to go over budget during the busy shopping season. Yet, rewards credit cards that have high interest fees continue be the payment method of choice for many.

If you’re among the shoppers who foresee that your holiday spending will lead you to carry a balance, opt for cash or a low interest credit card. In the case of the former, you’ll be more inclined to limit your spending and avoid any interest, while in the latter, you can stretch your budget while paying up to 50% less in interest fees compared to what most other credit cards charge.

Signing up for a store credit card without thinking it through

A number of retailers may try to lure you into signing up for their store credit cards during the holidays, often providing steep discounts on everything in your shopping cart if you apply on the spot. You’ll want to think twice before signing on the dotted line however. 

Most store credit cards have low credit limits, high interest charges in the instance you carry a balance and lacklustre rewards: particularly when compared to what Canada’s best travel credit cards or cash-back cards have to offer. While in some instances applying for a store credit card can be worth it, (if you frequent the same store for all your shopping runs for example), you’ll still want to do some research and avoid being swayed by a one-time discount. 

Not shopping from your loyalty program’s e-store

From the airmilesshops to the Aeroplan eStore, numerous credit card loyalty programs have online shopping portals that offer bonus points on your purchases. So instead of automatically visiting a retailer’s official website or Amazon to hunt for online holiday bargains, tap into your loyalty program’s e-store to potentially walk away with up to double the amount of points your card typically offers.

Not reading the terms of your card’s welcome offer

If you picked up a new credit card with a lucrative welcome offer just in time for the holidays, you’ll want to get familiar with the offer’s terms and conditions. A number of welcome offers don’t come into effect immediately and may require you to hit a minimum spend of $1,000 in order to get your bonus points or wait up to 3 months before you can access your cash back savings. 

Many card offers also stipulate your account needs to be in good standing for you to be eligible to receive an offer. So, if you missed a series of payments on your card, you may lose out.  In such instances however, it’s always recommended you contact your bank or card issuer as they may offer to maintain your eligibility. 

Paying extra fees while travelling

If you plan on escaping Canada’s blistering-cold winter for a beach getaway or are travelling to visit family abroad during the holidays, you’ll want to read up on what your card charges for foreign purchases. The huge majority of credit cards charge a foreign transaction fee (usually around 2.5%) on every purchase you make on your credit card in a non-Canadian currency. With that being said, there are a number of no foreign transaction fees credit cardsthat Canadians can use abroad that waive this fee and can help you save big on purchases you make outside of the border.

Not taking any action after accruing credit card debt

If, after the holidays have come and gone, you’ve racked up debt on your credit card, it’s critical you take steps to address it. Limit your spending on nice-to-haves and focus on paying off your balance, avoid racking up additional debt by using cash or debit to cover purchases instead of plastic, and consider transferring your balance to a new card with a lower interest rate (known as a balance transfer).

Hyder Owainati is a Content Marketing Specialist at Ratehub.ca, a website that compares credit cards in Canada, as well as mortgage rates, high-interest savings accounts, chequing accounts, and insurance, with the goal to empower Canadians to search smarter and save money.