All posts by Financial Independence Hub

Bank of Canada: As expected, Poloz still the Number Two hawk


By Jeff Weniger, WisdomTree Investments

Special to the Financial Independence Hub

There was little surprise in the October 24 decision by the Bank of Canada (BoC ) to raise its overnight interest rate a quarter point to 1.75%. There hadn’t been a sell-side strategist on Bay Street prognosticating anything but that action. BoC governor Stephen Poloz’s stop-start hiking program reinforces what we have been saying for some time: even with this tepid pace of interest rate increases, Canada is still Number Two in the “hawkishness” rankings of developed market central banks.

More important than the actual rate move is Poloz’s signaling, especially given NAFTA’s recent reconfiguration into the U.S.-Mexico-Canada Agreement (USMCA) and October’s generalized stock market malaise.

With the NAFTA overhang quasi-resolved, and the realization out west that shipping LNG to East Asia is not only politically palpable but a matter of national security, Poloz and the Canadian public finally have some good economic news in what has been a tough year for the country.

For an idea of the BoC’s relative position, consider the actions taken (or not taken) by several other major central banks of late. After hiking to 0.75% in August, the Bank of England appears to have its hands tied. It is hard to see how the Brits can make any moves between now and March 2019, the deadline for the to-be-determined “soft” or “hard” Brexit. Even if Brexit goes well, the BoE would seemingly need to take a cautious approach next spring and summer, meaning GBP rates will likely be a full 100 bps or more south of CAD’s throughout 2019.

The European Central Bank is also in no hurry to do much regarding interest rates. Given the VIX’s recent spike to 231amid China slowdown fears and Italian budget risk, any forecasts of a one-off rate hike by the ECB next year must be called into question. That is truer now than at any time in the last year or so, as Italian bonds maturing in 10 years have gapped up to 3.60%, a striking 320 bps spread over 10-year German bunds (0.40%).

The fear in southern Europe is of a “doom loop.” In this scenario, Italian banks, which are heavy owners of Italy’s sovereign debt, see the country’s yields rise, which weakens the banks’ capital base. That, in turn, sends government bond rates higher. A dog chasing its tail.

Of interest to the BoC, the Toronto housing market has somehow managed to pull off the sweet-spot slowdown, at least for now. This has surprised us, given the rarity of asymptotic price surges giving way to post-peak gentle, sideways slopes. The Teranet National Home Price Index for Toronto has managed to curve ever so slightly downward since summer 2017, witnessing total price depreciation of just 3.8% from the peak to September 2018.

If Street consensus is correct, the BoC will bring the policy rate to 2.25% or 2.50% at the end of 2019. There are some observers out there with calls for 2.75% or 2.00% on both sides of the bell curve. In order to have the confidence to hike three or four times, Poloz will want to see GTA home prices continue to click sideways with each of the Toronto Real Estate Board’s monthly reports. And that means no big swoons in activity like in Vancouver, where buyers and sellers are engaged in a staring contest that is becoming disconcerting.

Aggressive BoC rhetoric

In the Monetary Policy Report, the central bank went heavy on USMCA references, opening with the trade deal and then coming back to it again just a couple of paragraphs later. They were keen to make mention of British Columbia’s natural gas pipeline announcement as a one-two punch for justifying a confident onslaught of 2% on the overnight rate.

We are focusing less on the BoC’s forecast of around 2% CPI inflation from now to 2020 and more on the bank’s assertion that the economy is operating “at capacity.” This is critical. The U.S. still has some room to challenge its capacity utilization precedent, set just short of 80 on the eve of the 2015–2016 China scare. But for all intents and purposes, American capacity utilization at 78 is a rounding error compared to its limit (the 80 area).

If Poloz believes Canada is “at capacity,” and it looks to us like the U.S. is there too, then this is the stuff of inflation scares. Of the forecasting outliers (those penciling in 2.0% or 2.75% for year-end 2019), we think the latter camp has a better chance of being proven correct, on account of our thesis that the global trade war concept is overblown and “priced in.”

Items to watch, next 6 to 12 months

While we would be foolish to not focus on “classic” central banking metrics such as inflation and employment a few other idiosyncratic issues are also critical:
Continue Reading…
How (not) to trade US midterm elections: you can’t Trump staying the course

Investors should avoid making major portfolio changes in advance of the US midterm elections, says former advisor Dale Roberts

By Dale Roberts

Special to the Financial Independence Hub

When I was an advisor at Tangerine Investments I would have many more-than-interesting conversations with clients about short-term economic and political events; especially over Donald Trump. For those of you who do not live under a rock, Donald Trump is the more than controversial President of The United States. Mr. Trump went from real estate magnate and reality TV show host to the most important chair in the world. Many will write and say that the President who resides over the world’s largest and most influential economy and the world’s most powerful armed forces (by many times over) is the most ‘powerful person’ in the world.

So as investors, and for those who manage money, we should pay attention to what the most powerful person on earth does and says, right?

Nope.

As investors, we don’t invest in Presidents or Prime Ministers, we invest in economies and the companies that help drive those economies. With respect to investing in the U.S. the world’s greatest investor, Warren Buffett, often writes …

Never bet against America.

And heading into the Presidential elections of 2016 Mr. Buffett (a vocal Democrat and Hillary Clinton supporter) offered in a Nasdaq interview …

“America works … I’ve said this before, it’ll work wonderfully under Hillary Clinton, and I think it’ll work fine under Donald Trump … For 240 years it’s been a terrible mistake to bet against America, and now is no time to start.”

Ahhh, and there’s the very powerful and destructive key phrase tucked into that sentience; the two words “bet against.” If you make a short-term move, make a guess on a short term event, you’ve just turned investing into betting/gambling. You’ve turned investing into trading. As the saying goes, on the list of the world’s most successful investors you won’t find any traders.

Successful investors have a long-term outlook and a long-term holding period. Boring works. Excitement is for the casino. When asked what is his favourite holding period for a stock or investment Mr. Buffett will reply “forever.”

So don’t listen to me, but you might listen to the word’s greatest investor: who often states that he has never invested based on a short-term economic event or economic prediction or political event or political commentary.

An investor with a well-balanced portfolio will likely invest in US and International markets. When we invest in America we often own market-leading companies such as Apple, Microsoft, Johnson & Johnson, Walmart, Home Depot, McDonald’s, Coke and Pepsico, Costco, Amazon, Google, Netflix, AT &T, Exxon Mobil, Clorox, Facebook, Colgate-Palmolive, Goldman Sachs, and even Mr. Buffett’s conglomerate Berkshire Hathaway.

You’re not investing in Donald Trump, you’re investing in McDonald’s.

Investors can ignore the midterm elections

If you now understand that you don’t need to pay attention to the current President of the United States, you also do not need to pay attention to the next President of the United States, nor do you need to pay attention to the next group of Congresswomen and Congressmen and Senators who will fill the seats of The House of Representatives. You can ignore the midterm elections on Tuesday November 6th, 2018. You can ignore the Presidential election that will follow two years later. Continue Reading…

TFSA room may jump to $6,000 in 2019 but is the TFSA right for you?

By David Miller, CFP, RFP

Special to the Financial Independence Hub

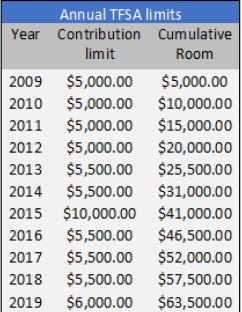
2019 TFSA limits will likely see an increase to $6,000 for 2019, up $500 from $5,500 in 2018. But is taking advantage of the TFSA the right choice for you?

The big story

Most Canadians still don’t understand the TFSA or know if it’s the right type of account for them. More room is great but according to the CRA in 2015, only 10% of Canadians are currently maximizing their TFSA limits1.  Also, the CRA has looked to collect over $75 million in past audit penalties over improper use of the TFSA2.

The history

Starting in January 2019, annual TFSA room of $6,000 will be provided to each Canadian resident over the age of 18. Since 2009, Canadian residents have been able to contribute a small portion of their after-tax savings into this tax-free account. If you still are paying taxes on interest, dividends or capital gains on your investments in a non-registered account, it’s time to review the TFSA. If no contributions had been previously made, your TFSA room accumulates over time and a full $63,500 contribution could be made January 1, 2019.

The contribution you make today can grow without any tax implications in the future. If you over contribute, the CRA will penalize you 1% per month on any amount over the approved threshold. A best practice is to check first with the CRA to determine your personal TFSA limit for the calendar year.

Improper use

If you accidently, or purposefully, over-contribute to your TFSA, the CRA will impose a 1% per month penalty on the overage. This may be overstating the obvious, but over-contributing is a bad idea. You would have to reasonably expect your investments to grow higher than 12%/year (assuming simple math with a January 1stcontribution) to break even. Having TFSAs at two or more institutions may be a way you lose track of your contribution room. Ensure you check with the CRA to understand your annual TFSA contribution limit.

Another example of improper use could be frequently trading stocks within the TFSA, aka ‘day trading.’This may be considered a  ‘business activity,’ as perceived by the CRA and you could be taxed personally on all the income, dividends and capital gains.

Spousal successor

An important but often overlooked benefit to utilizing a TFSA is as an estate planning feature: the spousal successor declaration. Continue Reading…

You’ll need to earn more than average to own a home in Ontario

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

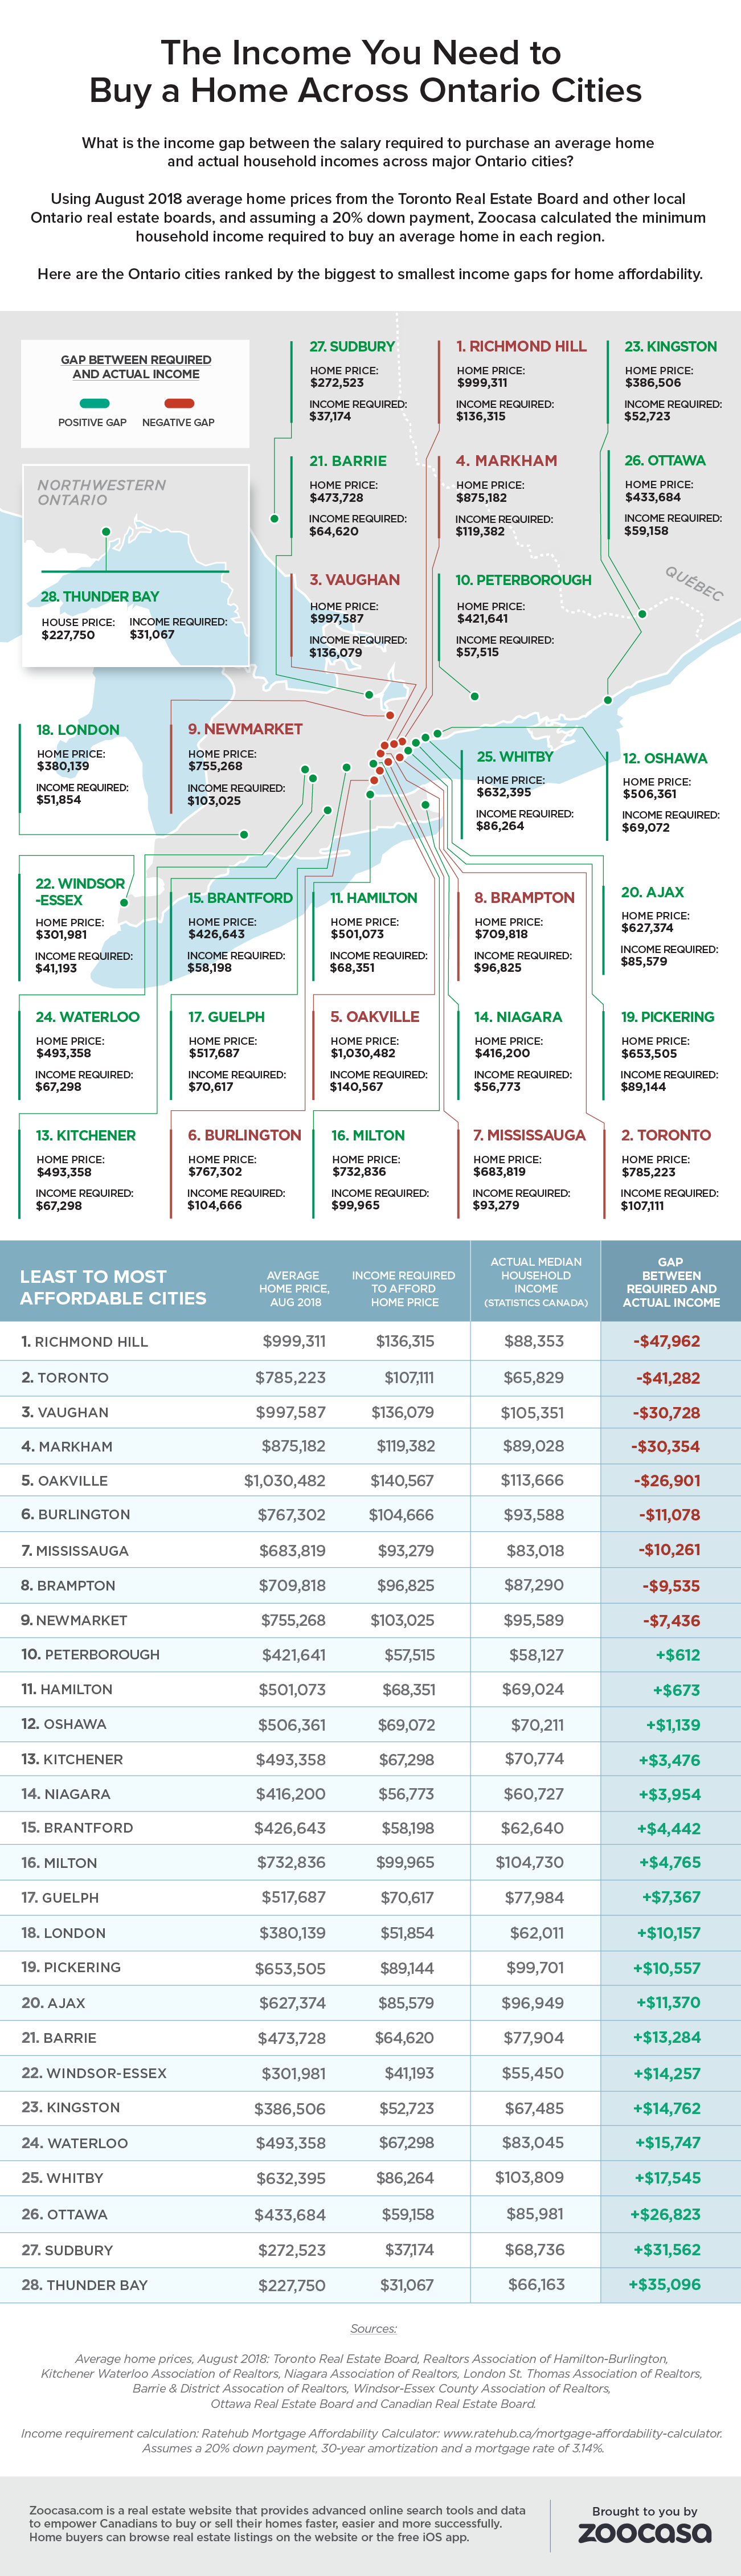
Where in Ontario are buyers most out of pocket when trying to purchase a home? Toronto invariably comes to mind as the province’s least affordable market – but new numbers reveal a pricey GTA suburb actually takes top spot.

New income and price data compiled by online brokerage Zoocasa finds that, when it comes to unaffordable housing, half of Richmond Hill buyers would find themselves a whopping $47,962 short on a home priced at the city’s average. That’s because the median income earned in the municipality clocks in at $88,535, when a total of $136,315 would be required to purchase and carry a property priced at $999,311.

Toronto comes in at a close second, with half of buyers falling $41,282 short of affording the average home price of $785,223.

Incomes must support housing prices

To determine the extent of affordability, Zoocasa collected the average August home price in each of Ontario’s 23 major markets, as reported by their local real estate boards, and calculated the minimum household income required to actually afford such a property (assuming a 30-year mortgage at a rate of 3.14 per cent). This amount was then compared to the actual median incomes earned in each municipality, as reported by Statistics Canada.

Whether or not a market falls within the realm of affordability for buyers depends on a few factors. For example, among the top five least affordable markets (Richmond Hill, Toronto, Vaughan, Markham, and Oakville, each had an average home price of at least $700,000 and, with the exception of Toronto, had pricier detached houses make up the majority of their August sales.

Northern Ontario takes top affordability spot

In contrast, the most affordable markets (Thunder Bay, Sudbury, Ottawa, Whitby, and Waterloo) were each supported by unique resource or service-based economies and higher median wages, with an average home price under $500,000.

For example, a prospective home buyer perusing Ottawa real estate or London, Ontario real estate would enjoy greater purchasing power in relation to their household income, compared to a household in Mississauga who would incur a $10,000-gap in their budget. Meanwhile, those making the move to Hamilton in search of relative affordability will find it, as the local median income of $67,298 remains perfectly in line with the average home price of $501,073. Continue Reading…

Closed-end funds vs. actively managed ETFs

Zagreb, capital of Croatia, HQ for closed-end fund manager OTP Bank.

By Tony Porcheron

Special to the Financial Independence Hub

The current popular conversation in investments is about Exchange Traded Funds (ETF) versus normal mutual funds. The conversation is always about low fees vs high fees. The one version that never seems to come up is about Closed-end Funds, which are the granddaddy of all managed money.

The brief history of the modern managed money industry — which included mutual fund, hedge fund, and exchange-traded fund (ETF) industries — started formally with The Investment Company Act of 1940.

It clearly defines the responsibilities and requirements of investment companies as well as the requirements for publicly traded investment product offerings including open-end mutual funds, closed-end mutual funds and unit investment trusts. It primarily targets publicly traded retail investment products.

The next major development was the first index fund. This was a Wells Fargo fund formed in 1971. In 1974, the first mutual fund index shares were offered to retail investors.

Finally, exchange-traded funds came along in 1993 with the invention of TIPs (Toronto Index Participation Units) on the TSX.

The ETF is now growing tremendously globally with investors looking for lower fees during strong market cycles.

You can now get ETFs in a variety of investment focuses, types, industries, countries, security selection bias, etc.

The majority of ETFs are passive, where the manager simply follows the direction of the fund outline with no or extremely little input from the manager. These ETFs are usually with the smallest fees down to less than 0.1% on large US Indexes or Fixed Income Funds. As the funds are very large and need little management input, they can still be very profitable for the fund companies to manage.

Actively managed ETFs

There are also ETFs that have an active management approach. The manager then has some or a tremendous amount of involvement in stock selection and management of the fund. Active ETFs are usually in sectors where it is difficult to get an index return or average. These would be in situations such as emerging markets, small or microcap stocks or sub investor grade fixed income. Continue Reading…