All posts by Financial Independence Hub

Why and how Financial Independence is achievable

By Jade Anderson

Special to the Financial Independence Hub

Financial independence can mean different things to different people, but the widespread definition is to be financially secure and on the right track to a safe retirement.

Sometimes people will still need to work in order to maintain their financial independence (aka “Findependence”), but the main idea is that you are free from any debt or outside help from financial institutions. This may seem like something that is unachievable for anyone outside of retirement age, who isn’t well established; however, because of the different types of financial independence, it may not be so difficult after all. Adjusting your spending habits, creating a budget for your self and several other things can lead you towards Findependence, if you know the right things you need to consider.

Reduce unnecessary expenses

Setting up a budget for the long term is extremely important if you’re wanting to become financially independent. If you can cut down on any unnecessary expenses (such as extra food, clothing, and entertainment) in your weekly spending, then you’ll find it will be a lot easier to save. If you are not used to saving money, starting small is important because it will help you establish a pattern of saving properly, and it will be easier for you when you move up to saving more of your average income.

Plan your savings and spending

Planning not only your savings, but also your spending is crucial for ensuring your financial independence. If you have a few debts, and you can make plans to pay off certain amounts by certain dates, you’ll find that the overall debt is easier to pay off, than if you paid it off in a lump sum. Using one of the financial calculators like those on Brighter Finance can help you calculate your budget and repayment periods for your loans, so you can keep track of your money more easily.

Continue Reading…

What does it really take to move overseas?

Overseas life is adventuresome

By Akaisha Kaderli

Special to the Financial Independence Hub

In preparing for a retirement overseas, we would wager that most people occupy themselves with the practical concerns of residential visas, banking, owning property, finding a doctor they like, medical care that they can afford and dealing with any language barriers. These are pragmatic matters with realistic solutions, and we say that these areas are almost the easiest part of making this lifestyle change. While the above mentioned topics are important and must be solved, we want to share with you what it really takes to move overseas.

It may surprise you, but what we have seen take people down, destroying their retirement dreams and sometimes even their marriages, are the emotional and psychological challenges one faces in adjusting to their new lifestyle overseas.

How do you prepare for these obstacles ahead of time? We hope the following tips and insight will shed some light on the topic.

Just like home, only cheaper

You could save a bundle moving overseas

Many people trip themselves up with their giddiness over the fantastic cost of living in their new location. They often come into a new country talking themselves into believing that living in their new destination is just like home, only cheaper. We want to tell you that no place overseas is just like home. Customs, foods, weather cycles, housing codes, the treatment of pets, the laws, the language, cobblestone streets and workmanship quality are all different.

We have seen folks love the quaintness of their new town but then fall apart because they can’t find parking near to markets where they shop. Their charming town might not have one-stop-shoping with a parking lot tying several stores together so they find that market day involves stopping in six locations, perhaps fighting traffic in between. Instead of taking their time to enjoy their enchanting town, they find this situation to be annoying and they carry the frustration with them all day.

 Culture and customs

Animals are treated as animals in developing nations and not as family members. Street dogs are common and if your heart is easily broken, then this might pose a problem for you. Continue Reading…

Accidental Death Insurance: What you must know before buying it

By Lorne Marr, CFP
Special to the Financial Independence Hub

Some insurance products are quite straight-forward (e.g. term life insurance), but others were created when insurance companies saw an opportunity in the market to increase their sales while reducing their own risk of needing to pay the claims. Accidental death insurance (often called accidental death and dismemberment) is one of these products.

Think of this product this way:

“If you look for a simple explanation, imagine all life insurance products to be cars. Your accidental death insurance is a car that you can drive only 30 minutes a day and only in one particular neighbourhood …”

Now, let’s understand this product better …

What is accidental death insurance?

Accidental death insurance is a life insurance policy (or an addition to an existing policy) that pays a claim only in particular cases: when the cause of death is an accident. In other cases, this insurance will pay nothing.

An important statistic to know is that only ~5 per cent of all deaths in Canada originate from accidents. That means that, in 95 per cent of cases, the policyholder will not be paid.

What is accidental death and dismemberment insurance?

Accidental death and dismemberment insurance is an insurance policy that pays a claim only if a death or a dismemberment (such as the loss of a particular body part, like a leg, hand, finger, etc.) occurred due to an accident. Typically, an accidental death and dismemberment insurance contract will define what amount will be paid in case of death and certain different types of dismemberment. Claim coverages associated with heavier dismemberments (e.g. a lost leg) are normally higher than claim coverages associated with smaller dismemberments (e.g. loss of a finger).

Is accidental death insurance worth it?

The quick answer is that, in most cases, it is not worth it. Continue Reading…

When $70 Crude Oil doesn’t feel Like $70 Crude Oil

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

“Judging by the oil market in the pre-OPEC era, a ‘normal’ market price might now be in the $5-10 range  … Last week Algeria’s energy minister declared, with only slight exaggeration, that prices might conceivably tumble ‘to $2 or $3 a barrel.’”

—The Economist, March 4, 1999

That quote feels like it was from a million years ago. A decade later, straight-faced economists would be talking about US$200 or US$300 per barrel. Times change.

With oil two years along in a bull rally that has witnessed its price triple from  lows in the first quarter of 2016, it may be just a matter of time before the purported list of stock market obstacles starts to include retail gasoline pain. With West Texas Intermediate (WTI) crude oil changing hands at US$67.44 and Brent crude at US$73.26, it’s hard not to be scared off by our collective ups and downs at the gas station.1

After regular unleaded challenged US$4 a gallon — $3.695, to be precise2 — in the summer of 2014, many strategists began to fear the worst. Gasoline would once again deal the death blow to the American middle and lower classes, as it had a half-decade prior.

But 2014 marked the worst of it, at least for now. WTI crude oil collapsed from triple digits to less than $30 in early 2016. Retail gas followed along, to levels south of $1.80.

But it has quietly chipped back, closing the first quarter at $2.57, and $3 looms in the American psyche. Unlike in Canada, where expensive fossil fuel prices tend to benefit the federal budget, Alberta employment and so forth, Americans historically have had no similar solace outside of petroleum-rich Texas and Alaska, perhaps. It’s just a different economy. People remember the first time they saw a gas station post a price of $1, then $2, then $3. And at $4, that memory strikes the gut: the insolvency years.

Regular Canadians feel pain from expensive gasoline, for sure, but not quite like the pain that hits Americans.

Tie the threat of a national average of $3 per gallon south of the border, maybe during the Labor Day road trip, with the possibility that U.S. Fed Chairman Jay Powell may bring two or three more rate hikes of 25 basis points by this year’s close, and it is not much of a leap to be sympathetic to a thesis of a gasoline-induced blow to American consumer confidence. But be careful, because that thesis is flawed.

Whispers

The “whisper number” on Saudi aspirations for Brent crude is $80 to $100 per barrel. But Donald Trump was already tweeting angrily at $70 per barrel, so it is reasonable to assume that another $20 to $30 would unwind much progress on recently fruitful U.S.-Saudi relations. But suppose ROPEC — Russia plus OPEC — marks oil up to $100 anyway. Gasoline could be closer to $4 than $3 in that circumstance. Does that break the American consumer? A half-generation or a generation ago, yes — certainly. But psychological anchoring on round numbers like $100 or $3.00 deceives. Consider our analysis below.

Our 2018 Reality

Figure 1 places unleaded gasoline costs in context. The U.S. population of some 322 million people consists of 126 million households driving more than 3 trillion miles per year. But because millennials do not drive as much as their predecessors, the number of auto miles driven per household has fallen to less than 25,000 from a peak of 26,413 in 2004.

Additionally, today’s cars are essentially computers on wheels, and fuel efficiency is notably higher than it was in prior years.

Twenty years ago, the American new car fleet got 23.4 miles to the gallon.3 By 2008, it was virtually unchanged, at 24.3. But the U.S. got burned on triple-digit oil, making it somewhat politically palpable when the Obama administration pushed forward with mandated 54.5 mpg fuel economy targets for model year 2025. In pursuit of such efficiency, the new car fleet’s efficiency rose to 30.0 mpg for the 2017 crop. Continue Reading…


Why starting your own business is better than getting a job

By Savannah Wardle

Special to the Financial Independence Hub

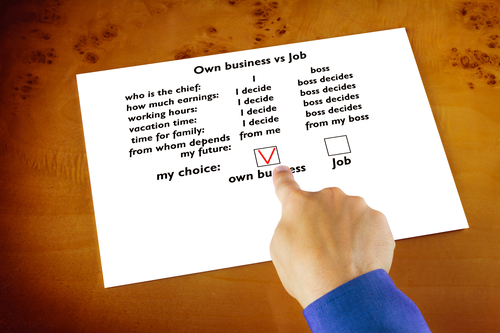
Instead of getting a job, make a job. You can take a large vacant place where a business should have been and fill it with everything you’ve ever dreamed of. If you’re on the verge of a major career change, you have the unique ability to customize that change to your needs. It might be time for you to branch out on your own and do things for yourself: you can wind up better off for having done it.

It’s easier than it used to be

The internet revolutionized the way that people run businesses. It used to be that people were confined to working for someone else because they didn’t have the resources they needed to become fully independent. Now, almost everything you can’t do yourself can easily be outsourced to software, apps, or freelancers who know how to get things done the right way. It doesn’t matter if you need to hire a Twitter expert, have a catering website built, or find specialty garage door software. The internet has it, and you can use it to build your own empire.

You’re free to explore Innovation and Creativity

Think about all the aspects of your old job that were holding you back. Did you have bold new ideas that you were dissuaded from pursuing because they didn’t adhere to the company’s “play it safe” motto? You don’t have to worry about that anymore. You’re the one calling the shots, and if you know you have the potential to shake up your industry, no one is stopping you. You can try and try and try, even if you fail, and you don’t need to worry about the powers that be restricting you from exploration.

You can live the way you want  

If you used to work long hours and weekends, you probably felt like you were missing out on life. If you run your own business, you can be open from 9 to 5 on weekdays. Close up shop for dinner and the weekends and live your life. A lot of people cite work/life balance as being one of the reasons they opt for a career change, and if you’re one of those people, you can easily find the exact balance you want by becoming an entrepreneur or an independent contractor.

You get to build your dream team Continue Reading…