All posts by Financial Independence Hub

5 tax tips for the Family Business: Keep more money in your wallet

By Mahyar K. Hansotia

Special to the Financial Independence Hub

 In Canada, as many as 80 per cent of small businesses are family enterprises. Whether it’s a start-up or a third-generation company, there’s often plenty of hard work that’s been invested, not to mention financial risk. So it goes without saying that business owners are keen to utilize any tax-saving strategies available to help them maximize take-home profits.  Here are five ways family business owners can keep more of their hard-earned dollars.

1.) Pay your family a salary

Don’t miss an opportunity to pay your spouse, common-law partner or children for any work done to help the business. This commonly known income splitting technique allows you to shift some of the income to family members who may be in a lower tax bracket. This can significantly reduce the overall tax bill by moving some of your income out of a higher tax bracket. Examples of work can include filing, answering phones, making deliveries and creative or technical assistance with the business website. Canada Revenue Agency (CRA) allows you to pay family members, as long as you meet two key conditions:

  • You must be able to prove that your family members actually did the work
  • The wages must be “reasonable under the circumstances”

In addition, this strategy allows family members to increase their CPP contribution, as well as create RRSP contribution room. Both items can benefit the family member in future years; CPP contributions will result in a higher retirement income, and the increased RRSP contribution room can be used in the future to bring down the family member’s taxable income should they be in a higher tax bracket.

2.) Pay a bonus directly to RRSP

There are some tax benefits for the family members as well. As an employee, they can consider contributing a bonus directly into their RRSPs. You’ll avoid tax withholding and the full amount can be used as a deduction, provided the family member has reached the CPP/EI threshold. Continue Reading…
Top secret tax saving tips for shrewd investors

By David J. Rotfleisch

Special to the Financial Independence Hub

While the most common tax savings tips such as contributing to an RRSP are well publicized, there are tricks that are not well known except by tax professionals.

So, here are obscure ways that we, as long-time Canadian tax lawyers, recommend for you, or people you know, to save on your taxes. After all, you have to make it to spend it.

Reduce Source Deduction Amounts

If you have income tax deductions that result in a large tax refund when you file your 2016 income tax return, then you can submit a form TD-1 form early in 2017 to reduce the amount of source deductions withheld by your employer from each subsequent paycheque.

This will mean money in your pocket every week instead of in 2018 when you file your 2017 tax return.

First Time Donor Tax Credit

2017 is the last year that you can benefit from an additional 25% tax credit for charitable donations made by a Canadian taxpayer who has never claimed a charitable donation in the past. So, if you’ve never made a charitable donation this is your chance to top it off at CRA’s expense.

Medical Expense claims for Spouse or Dependent

You can claim all medical expenses paid not only for yourself but also for your spouse and dependents, even if they have their own income and file their own tax returns.

Continue Reading…

How to add value in the Great Migration from mutual funds to ETFs


By Luciano Siracusano III, Chief Investment Strategist, WisdomTree

and Christopher Carrano, Investment Analyst


Over the past few years, as hundreds of billions of dollars has flowed out of equity mutual funds and into exchange-traded funds (ETFs), a great migration of assets has been under way in the asset management business. This is occurring because of the changing business models of advisors and brokers-dealers and because of the unique benefits that ETFs can bring to investors, including relatively lower fees1, transparency of holdings, intraday liquidity and the potential for greater tax efficiency.

In many cases, “low-cost beta” ETFs, which track broad indexes, have outperformed the vast majority of active managers over time.2 This has made the decision to move assets from actively managed mutual funds into ETFs not just a decision based on cost, but also one based on performance.

But investors making this migration today have a choice that goes beyond just low-cost beta. For the past 10 years, WisdomTree has been showing investors ways to generate “low-cost alpha” in the form of fundamentally weighted ETFs that provide broad market exposure but that rebalance equity markets based on income, not market value. In recent years, other ETF managers have followed similar paths, creating narrower exposures that seek to tap into return premiums such as value, size, quality, momentum or low volatility—all of which have been associated with generating excess returns versus the market over time.

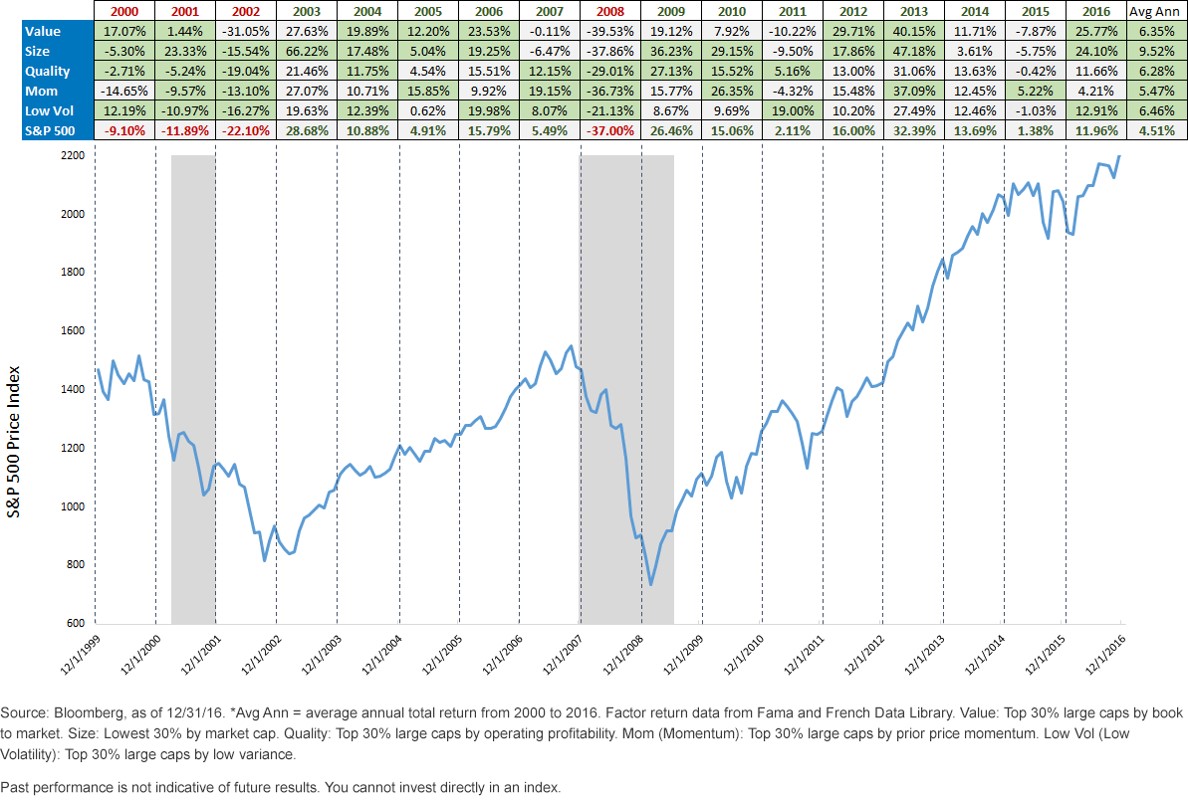
In the table above, we show how portfolios targeting value, size, quality, momentum and low volatility have performed compared to the S&P 500 Index in each calendar year since 2000. The last column on the right shows the annualized returns of these factor-based baskets over the 16-year period. Note that in each and every case, the annualized returns exceeded those of the broader market over the entire holding period.

Factors’ long-run performance

Yet, it is important to note that, despite all five of these factors outperforming the S&P 500 since 2000, they did not do so in each and every year. Factors are subject to the ebbs and flows of the business cycle, much like the sectors of the S&P. But, unlike factors, it is impossible for every sector of the S&P 500 to individually and collectively outperform the entire S&P 500 Index over time. The appeal of factor-based investing is that these major return premiums, based on decades of data, appear not to be subject to this same constraint.

Continue Reading…

The Pros and Cons of Universal Life Insurance

By Lorne Marr, LSM Insurance

Special to the Financial Independence Hub

Universal Life Insurance gives you flexible, cost-effective coverage that lasts a lifetime. It can be personalized to suit your changing needs and has a combined tax-advantage investment component that you can manage according to your risk tolerance and financial goals. Universal Life Insurance was invented by the recently deceased George R. Dinney in 1962. He explains the concept in his authorship of “Life Insurance as a Game.”

Universal Life Insurance allows you to adjust your premium payments (reasonable limits apply) as your needs or situation change. It is the ideal choice for people interested in flexible coverage. Unlike term insurance, which covers for a set number of years, universal coverage protects your family for life, as long as you keep up with the premium payments.

The policy has an investment component that gives you the opportunity to grow your wealth, so you have the option of using your life insurance while you are still alive. This means you can fund financial goals or leave more to your beneficiaries.

All the premium payments you make go into a policy fund. This fund pays for the cost of your coverage plus investments. The balance remaining after coverage costs are invested on a tax-advantaged basis. There are a variety of investment options for you to choose from, based on your risk tolerance and financial objectives.

How much your investment will grow depends on the performance of your investments and the amount of your premiums. The money in the investment portion of your account is yours. You can use it to make premium payments or a source of savings. You can use it as collateral for a loan, withdraw it outright or just let it grow for financial security for your loved ones. Don’t forget that borrowing or withdrawing funds from your policy reduces its cash value.

Pros of Universal Life Insurance

Universal Life Insurance provides many benefits, such as: Continue Reading…

Dispelling 3 myths of Tax Preparation

By Gennaro De Luca

Special to the Financial Independence Hub

Most people pay a lot of attention to how they invest in order to build a portfolio and maximize their returns. But when it comes to doing their tax returns, things tend to be different. Many of us – entrepreneurs, business owners and managers – keep doing it the same old way. We hand over all our pertinent documents to an accountant or tax-preparation service and fork over hundreds or thousands of dollars in fees. Well, May 1st, 2017 is the tax deadline this year.

Today, 80 per cent of the 14 million plus tax returns filed every year in Canada are processed digitally and that figure is increasing. This means accountants and other professionals file digital returns on behalf of their clients or, what is also happening with more frequency, people opt for DIY (Do it Yourself) tax software and do it on their own.

As a long-time wealth-management advisor and Certified Financial Planner, I know that a few myths persist about tax returns. Here are three:

MYTH 1: If you’re self-employed or own your own business, you need an accountant to do your tax returns.

MYTH 2: Preparing tax returns is expensive, especially if you have a small business or are self-employed.

MYTH 3: DIY tax software is easy enough to use for even very complicated tax returns.

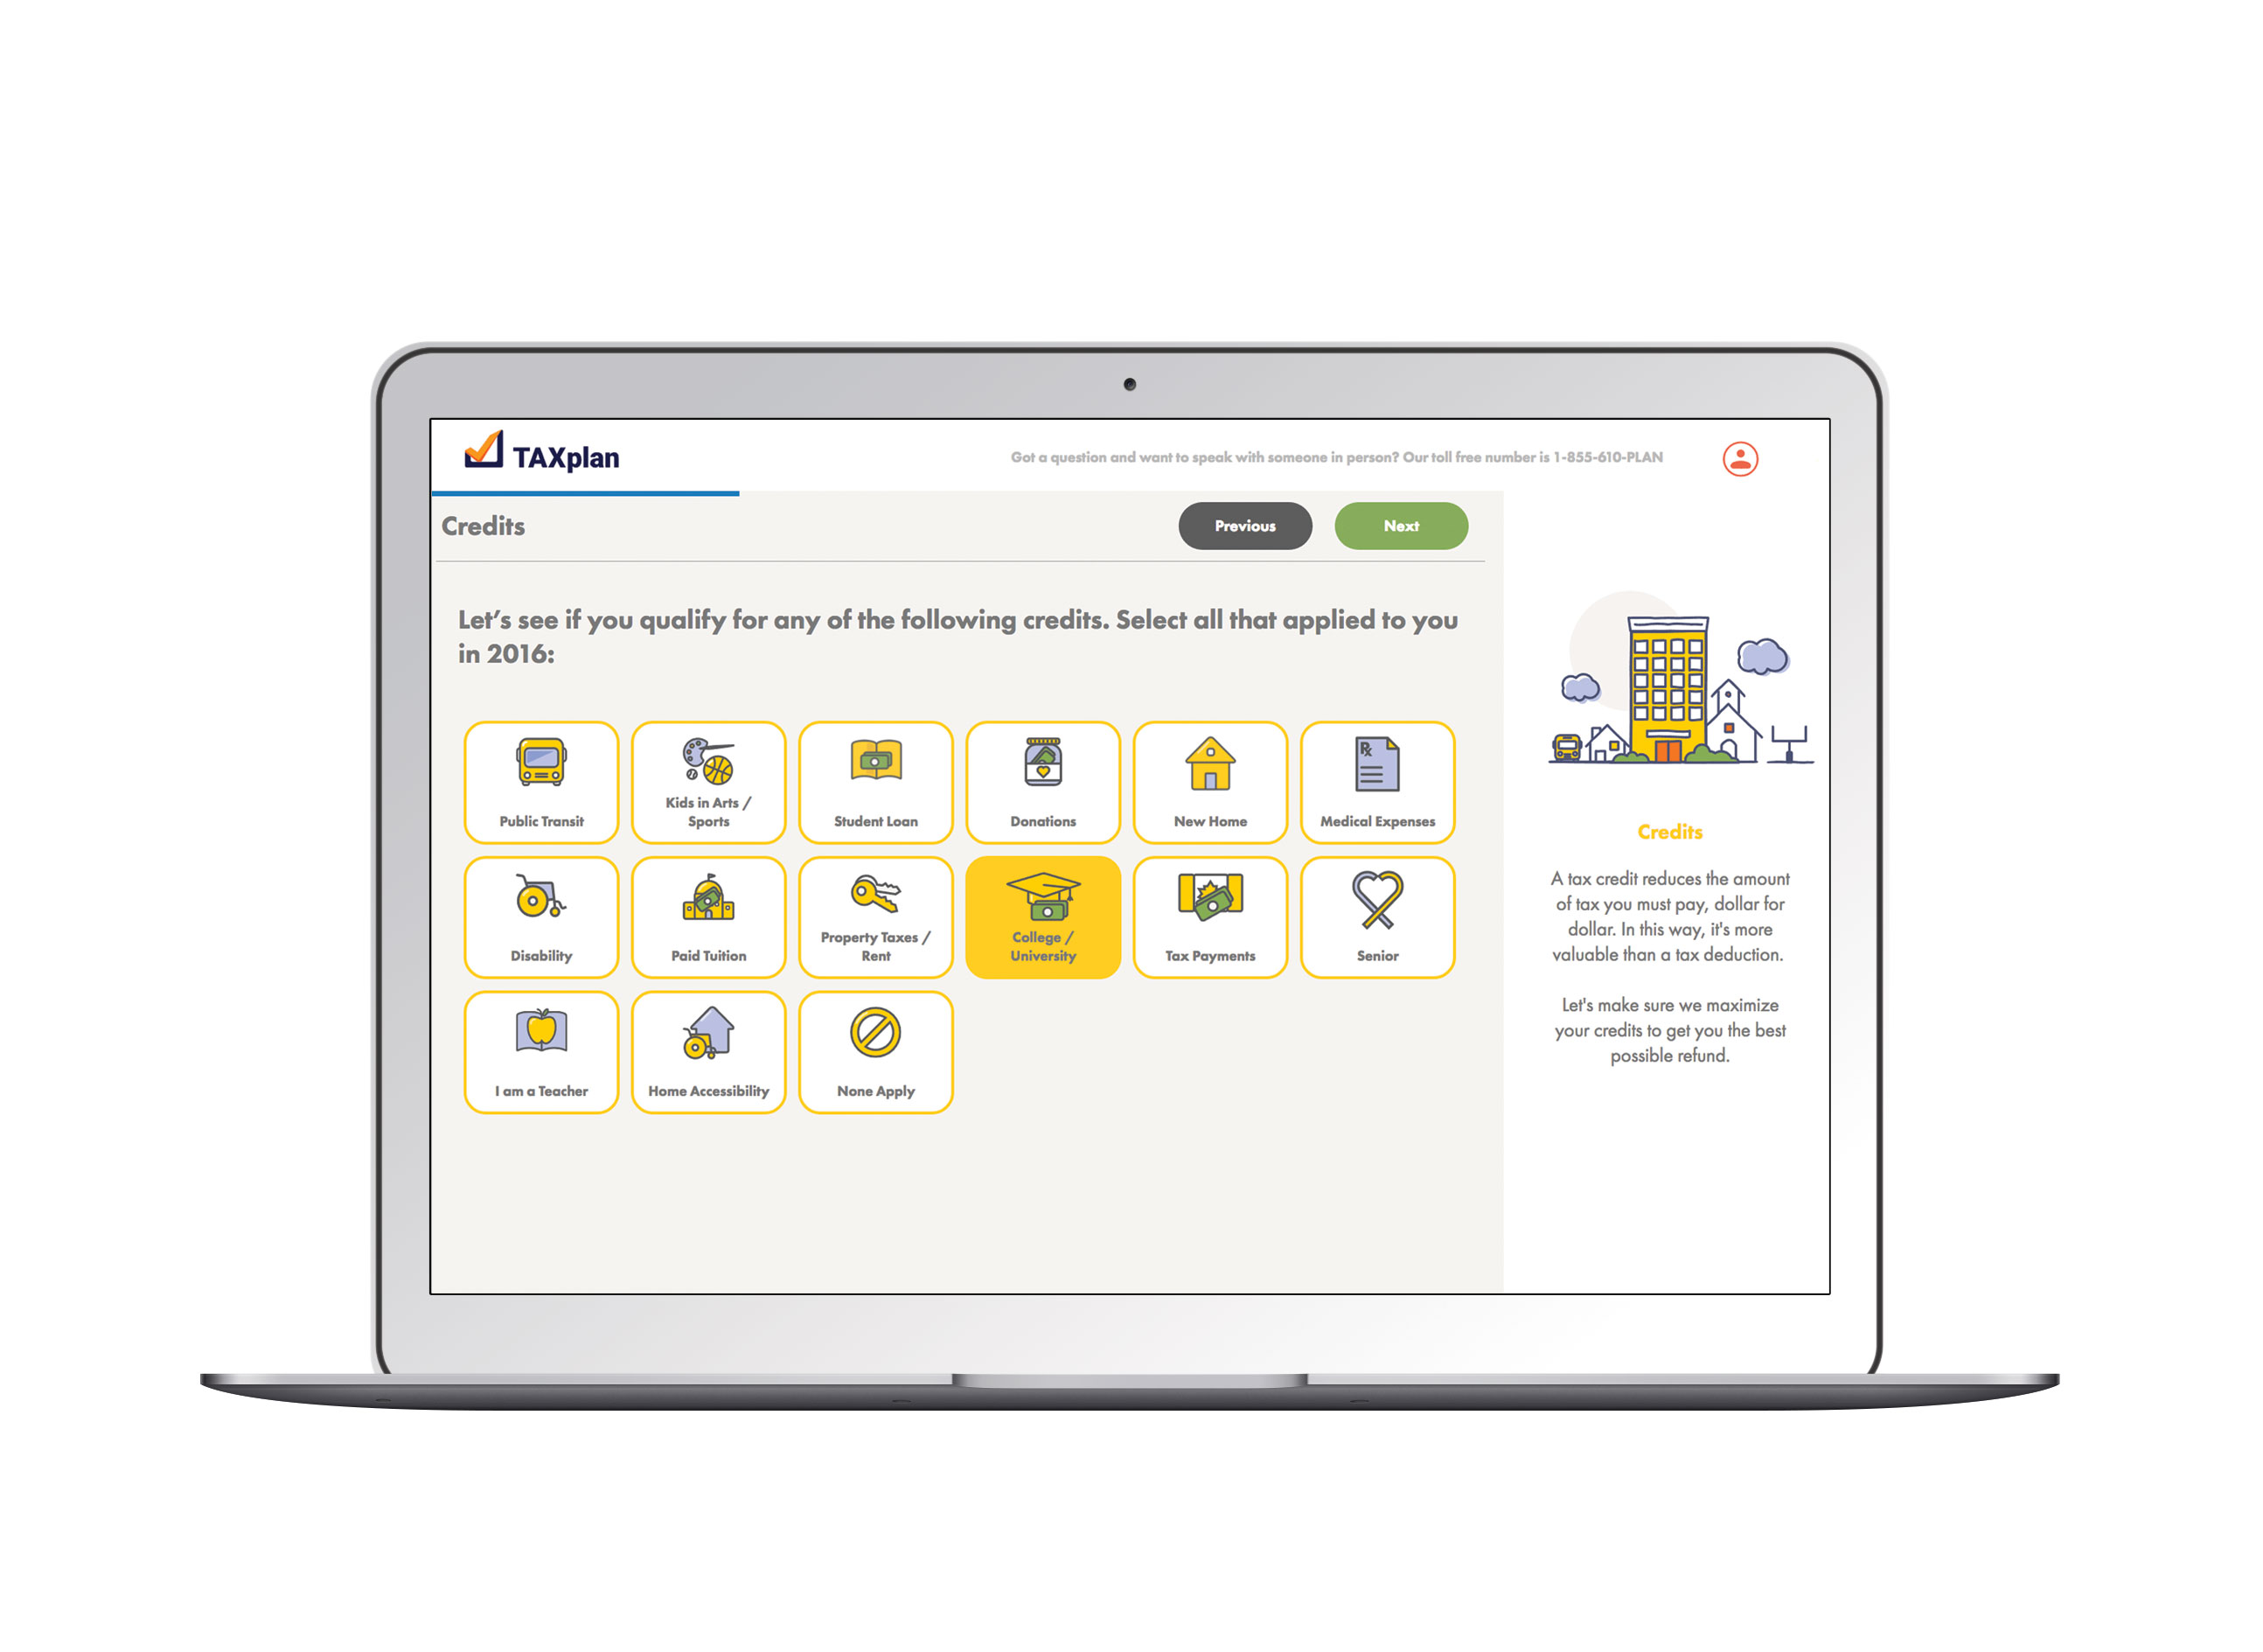
The answer is a digital return combined with the services of a tax professional. That’s what we do at TAXplan Canada and we just added a new feature that takes tax returns into the modern age. You can download our new app Sidekick to your mobile device. It allows you to take photos of all your documents and then you send them in. The tax professional does the rest. There is no other service like this in Canada. Continue Reading…