All posts by Financial Independence Hub

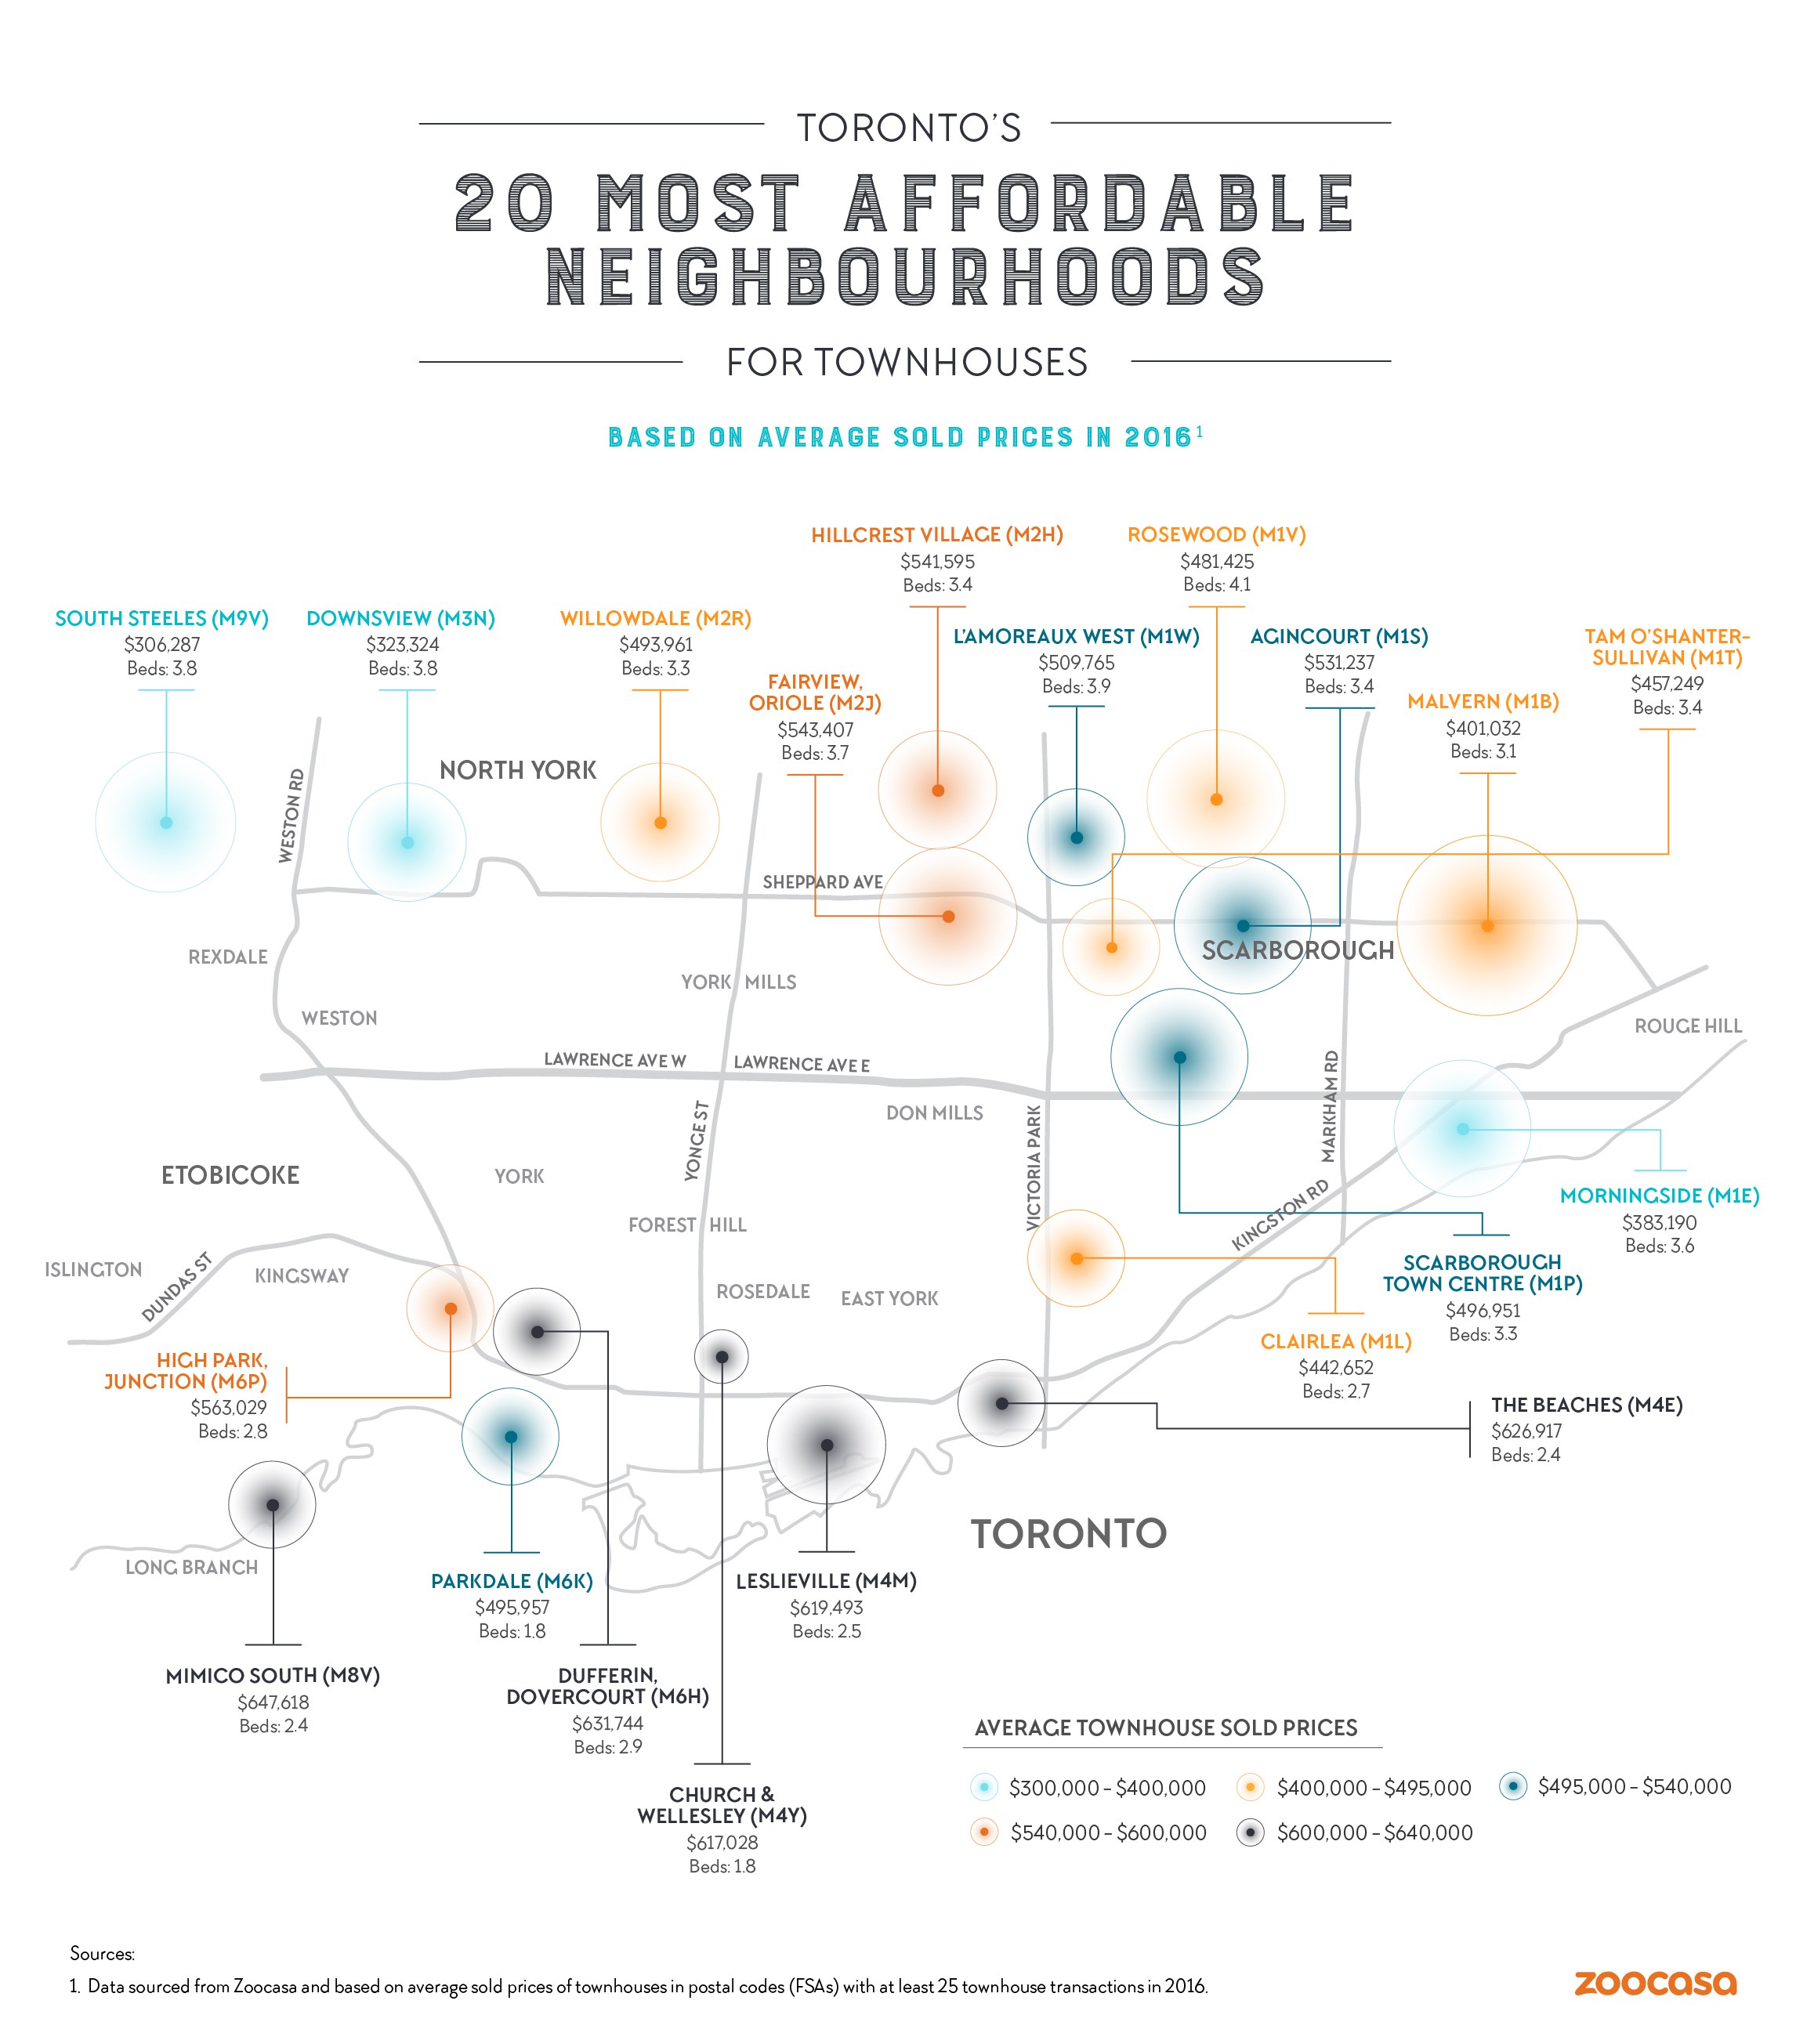
The Missing Middle: are Townhouses the answer?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

Shelling out a million for a home is no longer just an issue for downtown dwellers: it now costs that much on average to purchase a detached house in the ‘burbs, according to several new reports.

The February numbers from the Toronto Real Estate Board reveal regional home prices have surpassed two pricey milestones; average detached home prices in the city proper have hit the $1,500,000 mark, and $1,106,201 in the surrounding GTA. That’s tough news for those planning to trade a lengthy commute for affordable housing, as the competitive factors from the hot Toronto real estate market now stretch as far as the Niagara Region.

Too few houses to go around

The latest narrative around GTA housing is the scant supply of listings, with just 793 detached houses changing hands last month. “The listing supply crunch we are experiencing in the GTA has undoubtedly led to the double-digit home price increases we are now experiencing on a sustained basis, both in the low-rise and high-rise market segments,” said Jason Mercer, TREB’s director of market analysis. “Until we see a marked increase in the number of homes available for sale, expect very strong annual rates of price growth to continue.”

And it’s not just the resale market that’s too hot to handle. January numbers from the Building Industry and Land Development Association (BILD) report newly-built low-rise housing –- whether it be detached, semi-detached, or freehold row houses –- also exceed the average million mark, as fresh stock is immediately snatched up. Continue Reading…
Pack your bags, not your stress this March Break

By Brigitte Gougeon

Special to the Financial Independence Hub 

Taking a vacation is supposed to be a time to relax and enjoy a week away from the stresses of work and daily commitments. But with two in five Canadians planning to travel during March Break, there will be many people worrying about some aspect of their trip.

A recent TD Insurance survey found that for nearly half (49%) of Canadians planning to travel, the potential of falling ill while away was one of the top three causes of stress. Other top travel stress factors were losing a wallet or travel documents (58%) and other personal items such as a camera or mobile phone (41%).

Even though Canadian travellers are worried about the prospect of needing medical care while they’re away, only four in ten (39%) report regularly buying travel insurance. Canadians who don’t regularly buy travel insurance list a variety of reasons for not doing so, including it not being top of mind, thinking they don’t need it or thinking it’s not worth the cost.

Those planning to travel over March Break should take care to make travel insurance part of their broader travel-planning checklist. The cost of not buying travel insurance can have a devastating financial impact. Covering unexpected medical costs out of your own pocket can be financially ruining as, on average, government provincial health insurance will only cover a small portion of medical expenses. And even then, that coverage is capped.

Travel insurance has to be bought BEFORE your trip

Even when taking a short trip across the border –- which many Canadians take for granted –- you never know if something unexpected will crop up, like a fall or accident that requires medical attention. To safeguard you and your family, it’s important you ensure you have the right coverage that fits your unique needs and situation. And remember, you have to get insurance before your trip starts; it won’t protect you if you get the insurance after an accident happens or your trip is cancelled.

Additional travel tips for cutting down on stressors: Continue Reading…

Life Planning Basics: The Importance of an Emergency Fund

Photo Credit: Pexels.com

by Jackie Waters

Special to the Financial Independence Hub

When setting up your financial life plan, it’s important to understand the absolute necessity of an emergency fund. Before you can start saving for what you want in your future, you have to save some for all the stuff you don’t want or expect to happen.

The main purpose of an emergency fund is to protect against life’s many contingencies. This includes, but is in no way limited to; job loss, medical co-pays, car troubles, home repairs, child expenses, and unexpected travel needs. Without an emergency fund, you’re forced to turn to other means to pay for things you simply can’t ignore. Many turn to credit cards, which increases personal debt and leaves people in insurmountable holes. It’s nearly impossible to invest in your future when you’re sitting under a pile of debt.

How much should be in your emergency fund?

Continue Reading…

5 mistakes to avoid when buying your first Home

By Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

You’re about to make one of the biggest decisions of your life by purchasing a home. And it will likely be your biggest and most complicated financial commitment. So you should make a plan that captures everything you need to do to avoid costly mistakes.

Here’s a list of five mistakes you shouldn’t make when purchasing your first home.

1.) Failing to get pre-approved for a mortgage

It’s vital you know how much you can spend before you start looking for your first home. To figure out how large of a mortgage you can afford, use a mortgage affordability calculator. This will help estimate how much you will be pre-qualified for by a lender, who will conduct a credit check and review your finances. You can arrange for your pre-approved mortgage rate to be held for a period of about 90 to 120 days while you search for the right property.

2.) Not researching mortgage rates

Your first instinct will be to approach your current bank to obtain a mortgage, but you should do some research first to find the best mortgage rates. Continue Reading…

R.I.P. Traditional Retirement

By Brandon Hill

Special to the Financial Independence Hub

Does the notion of grinding it out day in and day out for the next 40 years to experience the freedom of retirement scare you? Wouldn’t you rather strive to enjoy the journey along the way?

The good news is that the traditional concept of retirement is slowly dying.

With the elimination of most employer pension plans and the fact that humans are living longer than ever, we are forced to come up with a different take on how our parents/grandparents view retirement.

Today I’ll show you two different concepts that rethink our traditional retirement model and are gaining popularity amongst the next generation of workers.

Findependence

What’s Findependence? It’s a term coined by Jon Chevreau: author, former editor-in-chief of MoneySense Magazine and founder of the Findependence Hub, an online platform and community for curated content focusing on achieving Financial Independence. “Findependence” is simply a contraction of the phrase “Financial Independence.”

Financial Independence is the point at which you work because you want to, not because you have to. It’s the tipping point where you have the right level of savings and investments working for you to provide the income you need to live your ideal life.

Think about that. It sounds very similar to our definition of retirement and at the same time totally reframes the perception of what retirement should entail. Rather than focusing on when you can stop work forever, you now shift your mindset to creating enough passive income through investing so that you can pursue anything you want.

Continue Reading…