All posts by Financial Independence Hub

The 6 steps to Financial Independence

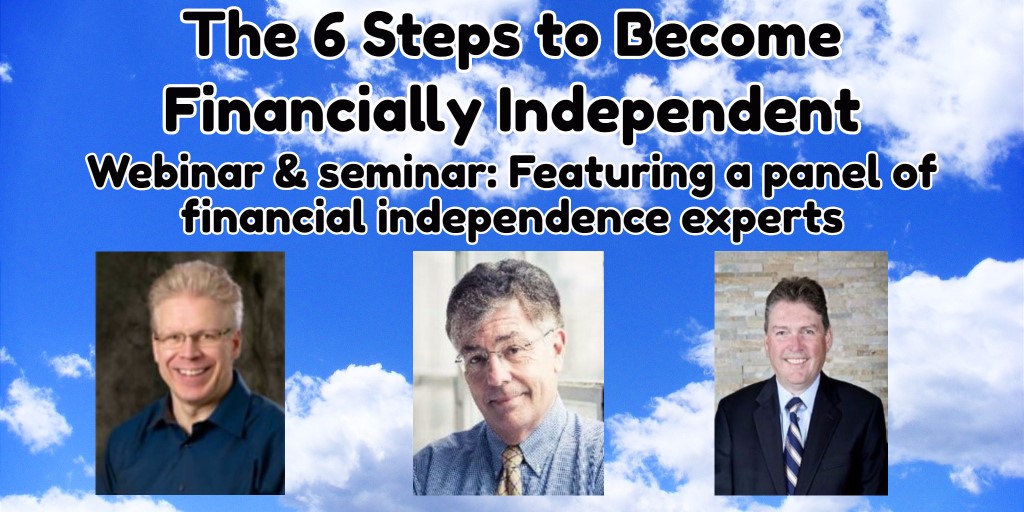
L to R: Ed Rempel, Jon Chevreau, Mike Drak

By Ed Rempel, CFP, CMA

Special to the Financial Independence Hub 

What is financial independence? How do you get there?

Financial independence means work is optional. You have enough money to live the way you want without having to earn money.

When you get there, life changes. You have freedom. You can do only what you enjoy or find meaningful.

If you don’t like your job or your boss, just quit. Your life is full of options. You can make the most of your own life.

When you get there, you can have a quiet confidence. You are financially secure.

Your plan should start with understanding your inner motivation and defining specifically the lifestyle you want to have once you are financially independent. It is your opportunity to determine your future.

Becoming financially independent requires planning and effort, but it is worthwhile to live a more fulfilling life. “It’s not about the money. It’s about your life.”

“Real freedom is financial freedom.” When is your Findependence Day?

Achieving financial independence is a very broad topic. Writing nearly 1,000 comprehensive, professional financial plans specifically for real Canadians has given me a deep insight into what really works.

Seminar in Toronto this Wednesday evening
Continue Reading…

The evolution of Robo advice

By Josh Miszk, CFA, CFP

Special to the Financial Independence Hub

Alongside the rapid growth of the online wealth management space is the speed with which firms are evolving to investors’ demands.

Some of the first online investment managers in Canada have evolved their initial investing models to include services like financial planning, advisory firm partnerships, and now, a platform offering portfolios from multiple management firms.

One of the challenges in evaluating cost, performance, and reputation across multiple “robo-advice” platforms is looking at their similarities and differences to get a real sense of how each portfolio compares. In addition, many firms are relatively new and, while investors like the experience of working with an online advisor, they’re restricted to portfolios designed solely by the same firm they feel provides that great experience.

A simple way of choosing the right portfolio

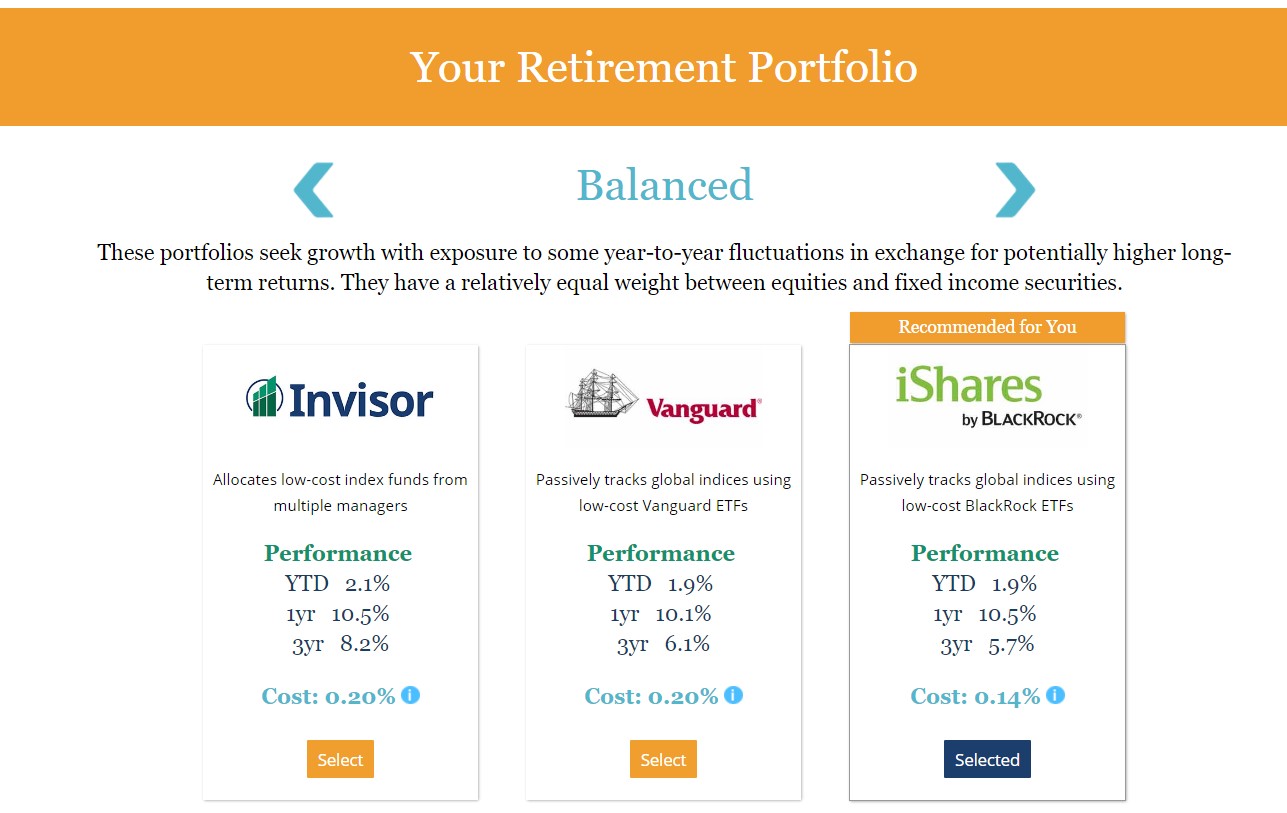
In response to the demand for greater choice, we’ve created a platform that offers clients multiple portfolio options created by two of the largest and most reputable institutional money managers in the industry; BlackRock and Vanguard. In working with these two firms, we are not only leveraging the quality of their investment products, but also their expertise in providing great portfolio solutions.

This addition will allow potential clients to compare and select portfolios based on our recommendations for them, as well as the elements of a portfolio they value most, like performance, asset allocation, and cost.

Continue Reading…

Be the first line of defense: top tips to prevent financial fraud

T

By Brent Reynolds, Capital One

Special to the Financial Independence Hub

As social media becomes ever prevalent in our lives, we have become increasingly accustomed to sharing personal details with friends, family and coworkers. While there’s certainly no harm in sharing vacation details or family photos with your network, this culture of sharing can lead to troubling consequences when it extends to personal financial information.

In the spirit of Fraud Prevention Month – an educational campaign each March that encourages Canadians to recognize and reject fraud – I’d like to offer a few tips to help empower Canadians to be their own first line of defense.

Protect your personal details

Our recent fraud prevention study found 47% of Canadians have shared their credit card number over the phone, via email or through the mail. One in five Canadians (22%) also admit to sharing their banking information via email, where the risk of phishing is high.

When it comes to sharing your personal information, always be cautious. Whether it’s over the phone, in person, through the mail or on the Internet, always know who you are sharing your personal or financial information with and why. If a call or email seems questionable, end the communication and visit the company’s secure website to contact them directly.

Select a strong PIN and protect it

While it may seem harmless to share your PIN with family members (in fact, 40% of Canadians admit to doing it), a PIN should never be shared with anyone. Select a secure and difficult-to-guess PIN that isn’t based on personal information like a birthday, address, SIN number or telephone number. Make sure you choose a unique PIN for each card. And, when accessing an ATM or paying with your card, be aware of who is around you and cover the keypad when you enter your PIN. Finally, if you’re going to store your PIN somewhere, make sure you choose a secure location and never write it on or store it near your card.

Take advantage of any features your card issuer offers

Continue Reading…

Is it worth it to skip a Mortgage payment?

By Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

Skipping a mortgage payment can seem like a good option, especially in an emergency if you don’t have a rainy day fund or savings to dip into. If you lose your job, your car breaks down, or you have any other type of unexpected expense, the option to skip a mortgage payment may look enticing. But is it worth it?

Some mortgage lenders allow you to skip a payment. Here’s what you need to know before deciding whether or not you should choose that option.

What does skipping really mean?

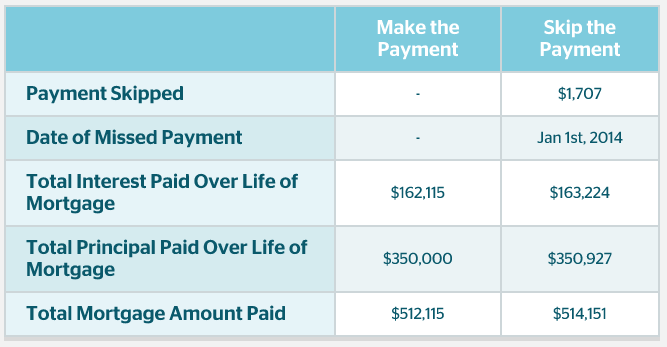
Sounds like a simple fix on a month when everything’s gone south, right? Not so fast. When you skip a payment, you’re not just pushing the expense back a month, you’re still racking up interest.

On a day-to-day basis, it looks like a simple monthly payment. But your mortgage payment actually has two component parts: The principal (the actual payment of the debt itself) and the interest. You don’t pay the principal, but your mortgage lender still charges you interest.

By skipping a month, you lose the chance to pay down the principal and you add on that month’s interest, which gets added to the total amount left on your mortgage.

You wind up with a higher mortgage rather than the number staying the same. The skip doesn’t freeze time. Any scenario where you add more interest should be looked at as borrowing more money.

Looking years down the line, the interest you pay after skipping will be even higher since your loan itself becomes larger. The increase won’t be huge, but if you just took on a mortgage with a 25-year amortization period, the additional interest will add up over time. If you’re close to paying off your mortgage, the interest costs won’t be as high.

Am I allowed to skip?

Continue Reading…

Duking it out: The RRSP vs TFSA

By Brandon Hill, CFP

Special to the Financial Independence Hub

I’ll never forget when I was growing up hearing my parents talking about “buying RSPs” (I got excited about saving money. I know… I’m a weirdo).

In my mind, they were this magical investment that people bought so they could multiply their money to one day retire. This term, “buying RSPs” is still used today; however, I think it adds to the confusion of what a RRSP really is.

I’m here to explain in plain English the difference between the RRSP (Registered Retirement Savings Plan) and the TFSA (Tax Free Savings Account).

What are they?

The best way to think of an RRSP or a TFSA is simply as an account that has special tax benefits. Just like your chequing account, you are able to deposit and withdraw money into a RRSP or TFSA; however, the special tax benefits make it slightly more complicated.

RRSP: When you deposit money into an RRSP, you’re allowed to deduct this amount on your tax return, saving you tax and increasing your refund. However, when you withdraw money from your RRSP, you have to pay tax on this amount.

TFSA: When you deposit money into a TFSA you do not get a tax deduction, although when you withdraw from your TFSA, you do not have to pay any tax.

All growth within an RRSP and TFSA is tax free.  

You can invest in many different ways inside the RRSP or TFSA, including: stocks, bonds, GIC’s, Mutual Funds, ETFs, and other more advanced options.

Continue Reading…