All posts by Financial Independence Hub

Why rely on hindsight for retirement saving?

By Atul Tiwari

Special to the Financial Independence Hub

New research from a colleague has me thinking about hindsight. The trouble, as the saying goes, is that hindsight is 20/20 — and you can’t benefit from it after the fact.

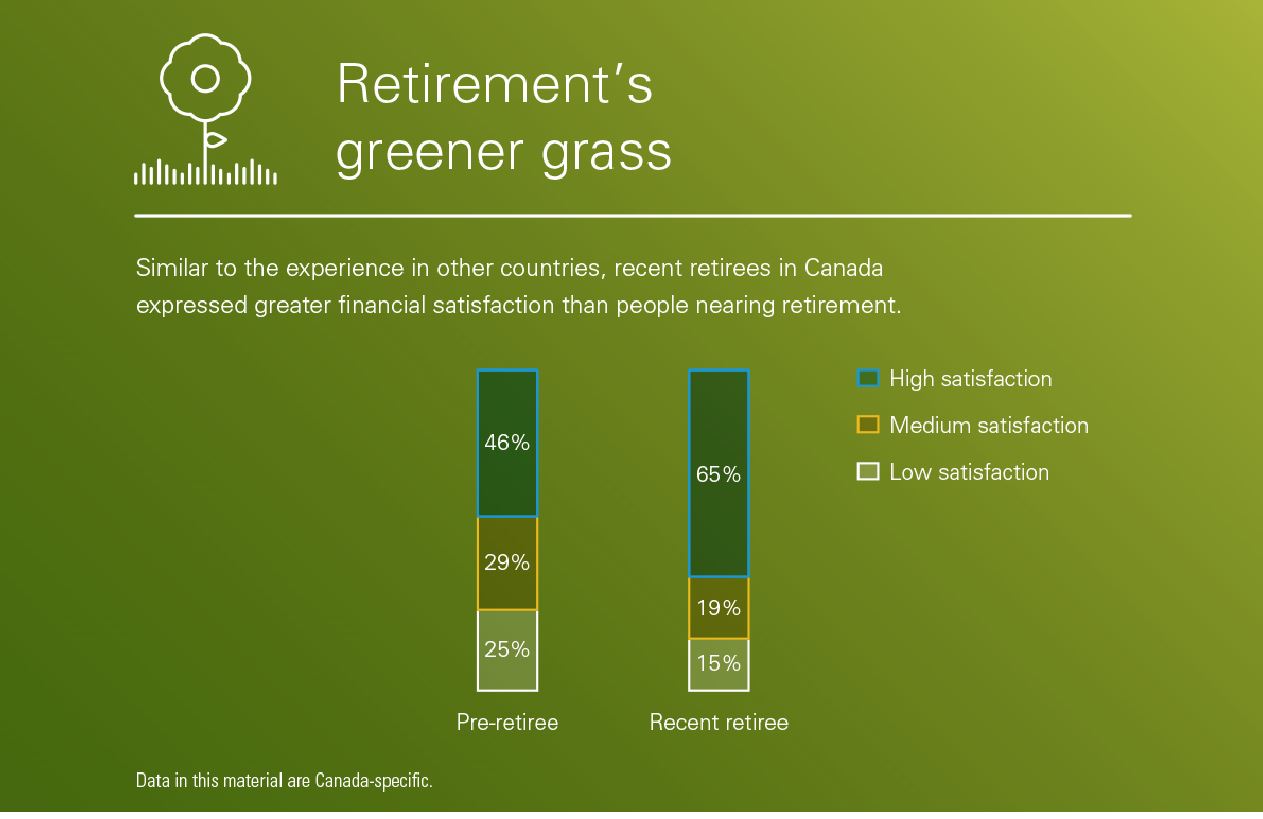
But why not try to benefit from someone else’s hindsight? My colleague Anna Madamba of the Vanguard Center for Investor Research found in a new study that recent retirees were largely satisfied with their financial situations in retirement, but, if they could, would still do some things differently in preparation.

With the benefit of retrospect, 43% of Canadian survey respondents “agreed” or “strongly agreed” that they would have saved more — a higher percentage than garnered by any other answer.

But perhaps it’s too simple to suggest that pre-retirees should just follow the example of others. Many people know at some level that they need to save more. Whether they do often comes down to two things: competing priorities and insight into how much money they’ll have (and need) in retirement.

Obstacles to saving more

Continue Reading…

How Smart Beta Strategies fared as Interest Rates rose in 2016

Rising Rate Case Study (July 8, 2016 to Dec 31, 2016) When U.S. 10- Year Treasury Note Interest Rate Went from 1.36% to 2.44%

By Christopher Gannatti, Associate Director of Research, WisdomTree Investments

Special to the Financial Independence Hub

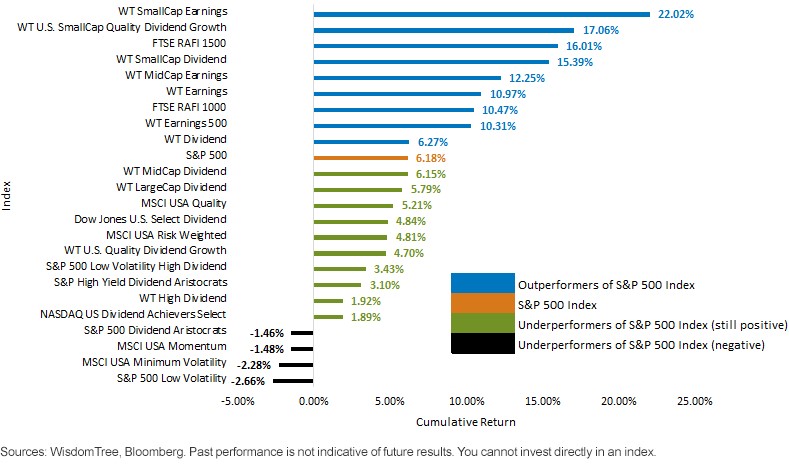
One of the biggest stories in 2016 was rising interest rates, most specifically that the U.S. 10-Year Treasury Note went from 1.36% on July 8 to 2.44% on December 31.1 While it may be too early to know if the greater than 30-year bull market in bonds (in other words, a longer than three-decade secular trend of falling rates) is over, 2016 did offer an interesting case study of smart beta strategies, many of which had only been in live calculation during falling rate periods.
How Strategies won as Rates rose

In the recent rising rate periods in 2013 (May 2, 2013, to December 31, 2013, when the U.S. 10-Year yield went from 1.62% to 3.03%)2 and 2016, a few big themes became clear:

  • Small Caps: One aspect of small-cap companies is their ability to respond quickly to trends of improving growth, which is typically apparent during periods when the 10-Year yield is increasing. Additionally, they tend to have cyclical exposures regarding sectors instead of more defensive exposures. Also, if the U.S. dollar is strengthening (not unusual when the 10-Year yield is rising), these firms do not tend to have exports as their dominant source of revenue and therefore have less of a competitive headwind.
  • Earnings: Rising rates tend to place strategies with higher valuations at risk, because one impact of rising rates is to lower the current valuation multiple of equities. WisdomTree’s earnings strategies are designed to provide lower price-to-earnings (P/E) ratio exposures to the market segments upon which they focus. It’s also notable that they tend to naturally be under-weight in the more defensive sectors of the market (Utilities and Telecommunication Services are two big examples) that usually tended to do better during the falling rate periods that directly preceded the rising rate period.

How Strategies Lost as Rates Rose

• Low Volatility/Minimum Volatility: It’s important to realize that the word “volatility” relates to both upside and downside market movements, seeking to lower both of them. Continue Reading…

Aman Raina’s Robo portfolio — 2 years later

Aman Raina

By Aman Raina, Sage Investors

Two years ago I decided to set up an account with an online wealth management company that manages portfolios using algorithms and computer code. At the time, these Robo Advisers were just getting out there but there was a fair bit of buzz on how they could threaten traditional wealth management services.
I was intrigued by the model, but there was one thing that many marketing materials, blogs, and mainstream media was avoiding … do these things make money for investors?


I was having a hard finding an answer to this so I decided to try to find out myself.  I set up an account with one of the big Robo Adviser firms. My goal was to go through the process and blog about my experience and more importantly, the results. We’ve now crossed the two-year anniversary of my ROBO account, so let’s take a look at how it’s doing now.

When we last checked in with our ROBO portfolio in January it was taking some hits along with the overall stock market. Since then the market has recovered quite nicely. Let’s take a look under the hood to see if the Robo Portfolio has bounced back.

Performance Continue Reading…

Why aren’t robo-advisors being used by those who need them most?

By Edward Kholodenko,  Questrade

Special to the Financial Independence Hub

Uber has quickly become the largest personal transportation company in the world, yet it  doesn’t own a single vehicle. That’s because there’s more to Uber than just hailing a ride from your phone. It’s providing more convenience at a lower price and in turn, transforming the transportation industry.

Substitute Uber for Amazon, Airbnb, or any other tech disruptor and a common theme emerges. On the road to becoming mainstream, applications that reduce cost and improve convenience are often first adopted by millennials and the tech-savvy. While the early adopters reap the many benefits of these innovations, those who hesitate are missing out.

Retirement challenge and the Robo-Revolution

When it comes to financial technology, there are certain populations that can no longer afford to be late adopters. Thanks to the innovation in the investment space, preparing for retirement has become easier than ever. Enter robo-advisors: an online wealth management service that provides diversified investing, much like a mutual fund, but at a much lower cost.

Given the current state of retirement savings in Canada, it’s apparent that this technology has great value to those willing to take the leap.

There is concern that 80 per cent of middle-income Canadians nearing retirement won’t have enough to support themselves. The average Canadian’s retirement savings of $71,000 will last only a few years, and, 50 per cent of Canadians are not confident they will have enough to retire comfortably.

Not only are Canadians saving far too little for their retirement, but also many can no longer depend on company pension plans to provide the income needed to stop working.  Our golden years are increasingly self-funded and investment decisions now fall on the shoulders of the individual. There’s a fantastic opportunity for new solutions in this space, and those willing to embrace a solution provided by fintech providers are reaping the reward.

Robo-advisors, in spite of the name, aren’t actually robots. Professional (human) portfolio managers handle all of the investments. In fact, there are two types of managed robo-advisor accounts: actively- and passively-managed:

Actively-managed advisors have a dedicated team of portfolio managers who select investments and adjust the portfolio to take advantage of market opportunities, all of this at a low cost. Passively-managed advisors typically invest according to set investment rules that only track the market.

These advisors use leading technology and proven strategies to provide a better investment experience at a lower cost to the consumer. And, by reinvesting the money you save in fees, individuals are able to increase their retirement savings and returns.

Robo-advisors are helping Canadians retire wealthier

Continue Reading…

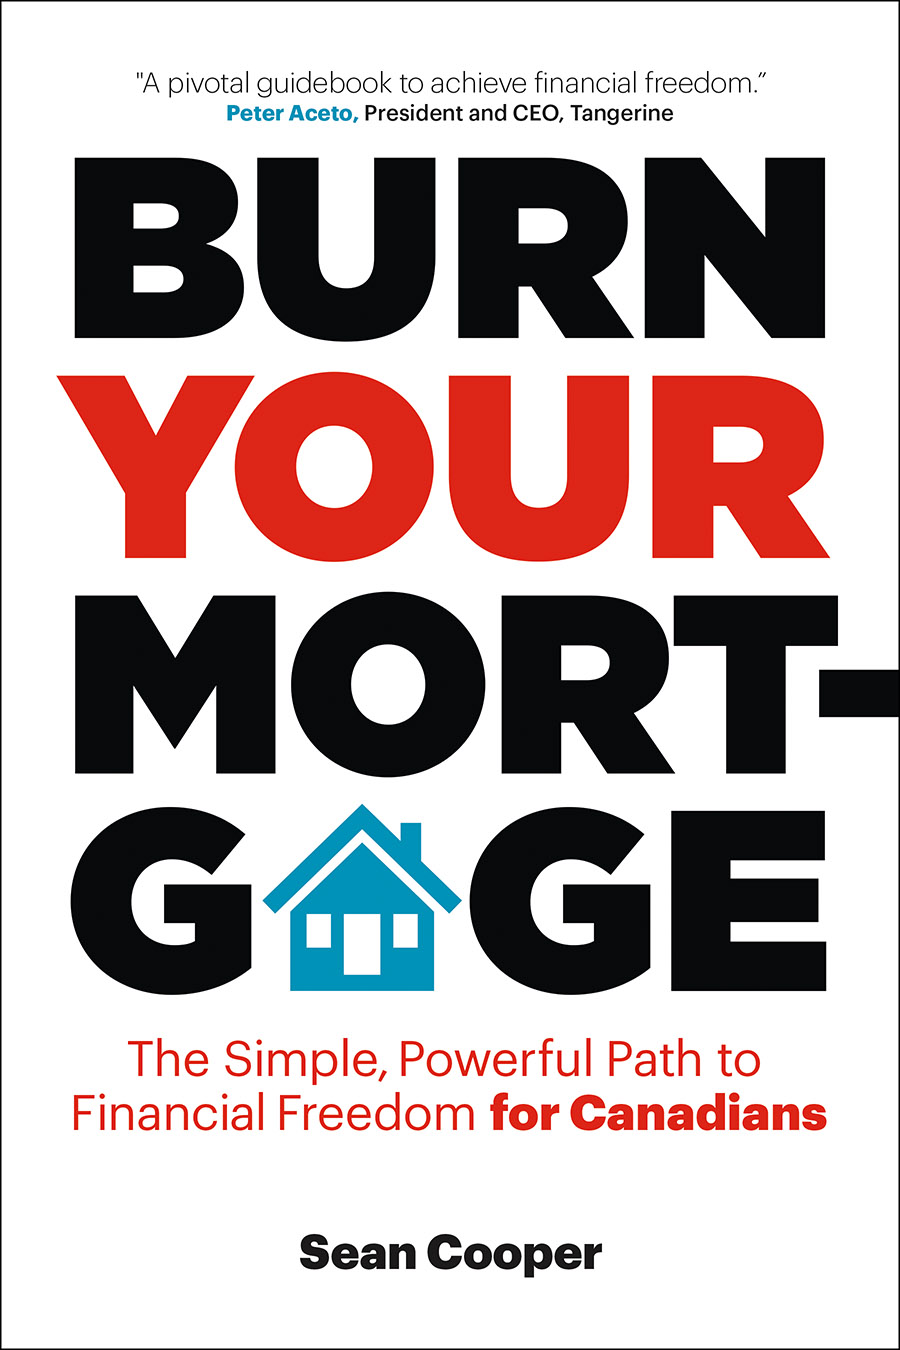
Burn Your Mortgage: The simple, powerful path to Financial Freedom

By Sean Cooper

Special to the Financial Independence Hub

Five years ago I read Jonathan Chevreau’s financial novel, Findependence Day, and it changed my life forever.

One of the central themes of the book is that the foundation of Financial Independence is a paid-for home. I wasn’t a fan of six figures of mortgage debt hanging over my head for the next 30 years, so I aimed to pay off my mortgage as quickly as possible.

A little over a year ago I reached my goal of “Findependence” when I burned my mortgage – literally. I paid off my home in Toronto in just three years by age 30. Thanks to a stroke of luck and good timing, the story went viral, making headlines around the world from the U.K. to Australia. I received hundreds of email from people congratulating me and wanting to follow in my footsteps.

This inspired to me write my new book, Burn Your Mortgage: The Simple, Powerful Path to Financial Freedom for Canadians. With home prices skyrocketing in cities like Toronto and Vancouver, many feel like  the dream of homeownership is out of reach. I’m here to tell you that it’s not. I may have paid off my mortgage in three years, but that doesn’t mean you have to. There are simple yet effective lifestyle changes that anyone — from new buyers to experienced homeowners — can make to pay down their mortgage sooner.

Some people argue it doesn’t make sense to pay down your mortgage early with interest rates near record lows. I see it differently. Instead of using low interest rates as an excuse to pile on more debt, use them as an opportunity to pay down the single biggest debt of your lifetime: your mortgage.

Here’s an excerpt from my book that looks at why you’re most likely better off paying down your mortgage instead of investing. [Editor’s Note: the official launch of the book is today.]

Why pay down your Mortgage when you can come out ahead Investing?

Continue Reading…