All posts by Financial Independence Hub

Q&A: Stock markets are at all time highs … should we sell?

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

Here’s a question I received recently, which rhymes with many I’ve heard before:

Now that the Dow has hit 20,000, we should seriously get out and put the cash under the mattress … don’t you think?

This time it was the Dow’s recent high-water mark. In the past, it’s been the same question in various forms, all of which could be rephrased to this question behind the question: Should the all-time nominal stock market highs be used as some sort of signal to reduce equity holdings?

Or conversely, should it be used as a rationale for holding onto cash balances or deferring new equity purchases (which, in my experience, is an even more common form of market-timing)?

It is human nature to look for shortcuts and/or ways to simplify complex questions. The fact that people predict outcomes by making up stories is what makes us all … humans.

Timing the markets when they’re at all-time highs is a nice, neat and simple story. Unfortunately it’s a fable; it doesn’t work. To use a “baseball story,”  three strikes and you are out.

One.

I can point a couple of my past posts here and here for frowning on these sorts of signals, or treating them as anything other than the noisy blips they are on your financial radar screen. Try to chase them, and you’re more likely to be left flying blind.

Two.

Nominal levels ignore market valuations. That means new market highs may be fun, but they’ve not been worth beans for predicting future returns. Those are expected either way, but for entirely different reasons.

Three.

To take a deeper dive into the subject, Dimensional Fund Advisors has done the heavy lifting for us in “New Market Highs and Positive Expected Returns.”Their conclusion is that it doesn’t work. Give it a read if you want all of the details.

Still not convinced? … then please contact me.
Steve Lowrie holds the CFA designation and has over 20 years of experience dealing with individual investors. Before creating Lowrie Financial in 2009, he worked at various Bay Street brokerage firms both as an advisor and in management. “I help investors ignore the Wall and Bay Street hype and hysteria, and focus on what’s best for themselves.” This blog appeared originally appeared on his site on February 3rd and is republished here with permission. 
 

A retired Advisor’s Open Letter to Bill Morneau on expanding TFSA

Finance Minister Bill Morneau (bmorneau.liberal.ca)

(To:) Hon. Bill Morneau, Minister of Finance,
House of Commons, Ottawa.

Dear Hon. Minister,

Thank you for your response to my previous letter. I am a strong believer in an enlarged Tax-free Savings Account (TFSA) and have NINE reasons for that belief through my experience as an IA (Investment Advisor).

I think you will agree that the larger TFSA makes retirement savings fair for all levels of Canadians incomes, but helps those who need it most as there is little RRSP deduction benefit for low-income Canadians. I think your background experience will lend itself to agreeing with my nine reasons for restoring the $10,000 TFSA.

Restore the $10,000 TFSA

The $10,000 TFSA [the previous annual contribution level] is the most profound and beneficial social program created in Canada’s 21st century. It benefits the young, seniors and the less fortunate as well as the well off. Its principal benefit is a meaningful and manageable amount of money which can be used as a saving vehicle and a retirement savings account.

1.)  It is especially beneficial to the non-working spouse, by enabling a savings and retirement account not requiring a monthly pay cheque and its commensurate income tax and tax deductions. This was the principal reason for the Americas Roth IRA, (ROTH account withdrawals are tax free,  but after the age of 58.)

2.) The larger TFSA amount is a meaningful savings target by today’s standards in that $400,000 can be accumulated over 40 years of adult life. Continue Reading…

RRSP Gross-up Strategy: Contribute 40-70% more to your RRSP

“Never put dry pasta into your RRSP.”

By Ed Rempel

Special to the Financial Independence Hub 

Wouldn’t it be great if you could save a lot more for your future without affecting your day-to-day cash flow?

One of the main things people learn when they first have a retirement plan done is that you need to invest more than you thought to have the future that you want. But with all the day-to-day expenses, it can be difficult to find the money to contribute as much as you would like to your RRSP.

The RRSP gross-up strategy is a simple strategy that can make a huge difference for you. It can enable you to easily contribute 40 to 70% more to your RRSP.

The strategy works if you already expect a tax refund. If you contribute monthly to your RRSP or have various tax deductions or credits, you probably expect a tax refund.

It is smart to gross-up every RRSP contribution you make.

You have three options with your tax refund:

  1. Spend it.
  2. Invest it.
  3. RRSP gross-up strategy.

Here is how the RRSP gross-up strategy works. Continue Reading…

Impact of the Trump administration’s Potential Tax Reform

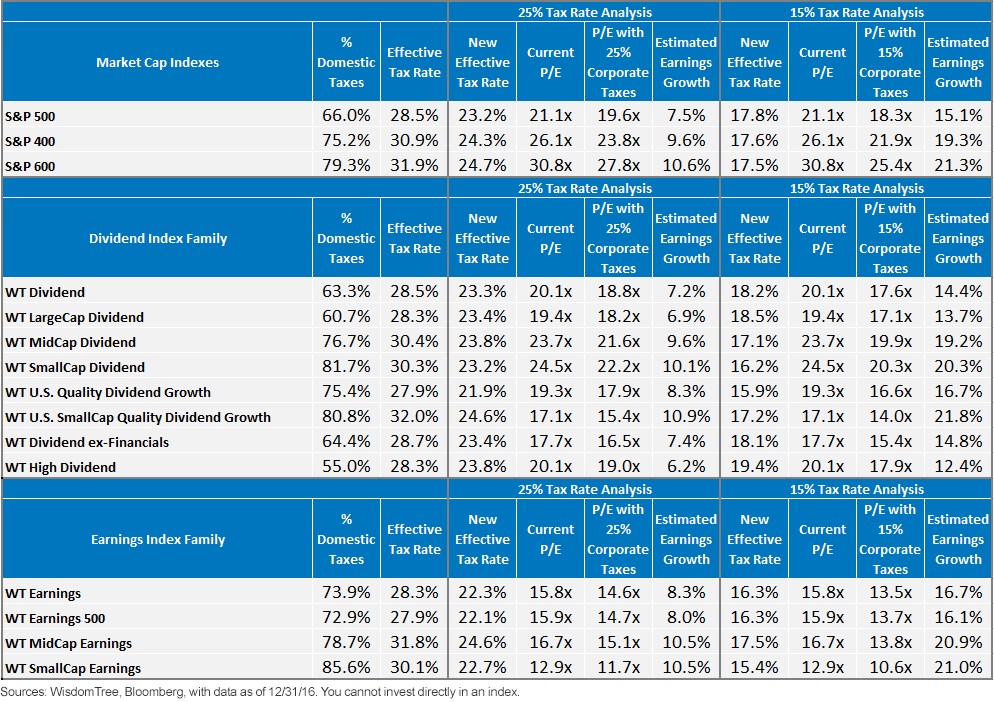
Summary of potential tax cut across Indexes

By Jeremy Schwartz, Director of Research, WisdomTree Investments and

Josh Russell, Quantitative Equity Strategist, WisdomTree Investments
Special to the Financial Independence Hub


Corporate tax cuts were a focal point of Donald Trump’s campaign — and Trump says lowering corporate taxes will be a priority in his first 100 days as president.

Based on the initial market response to Trump’s victory, lowering tax rates looks to us like the most important factor driving the market.

Equity markets, of course, like it when taxes are cut. It naturally means more after-tax earnings that can be reinvested or distributed to shareholders — and, importantly, an improvement in valuation ratios that many think look extended under present circumstances.

We published an initial sensitivity analysis to look at how various assumptions on tax rates might impact the earnings growth and ultimate market valuations across a market cap-weighted index set of the S&P 500, S&P 400 and S&P 600 — and across the sectors in those indexes. We have updated our original analysis to also include domestic WisdomTree Indexes; we also have updated our initial model for estimating the potential tax benefit that shows new results for the cap-weighted index family.1

Lower Tax Rates = Big Earnings Growth and Market Moves in Small Caps 

To summarize the results, a simple model shows the following: the more earnings (and taxes paid) that come from the U.S., the greater the earnings growth would be from a tax cut, because by and large, the companies with revenue across the world already have lower effective tax rates. Continue Reading…

Better Retirement choices: An elegantly simple solution

By Doug Dahmer

Special to the Financial Independence Hub

“Life,” philosopher Albert Camus contended, “is the sum of all your choices.”

Do you think otherwise?

Good or bad. Easy or hard. Right or wrong. Every choice you make will impact your life to some degree.

Choices with little impact are often made without much thought and the trouble is this casual approach to decision making tends to be deployed on bigger and more impactful choices.

In my profession, as a retirement income specialist, I see poorly made choices all the time. They, unfortunately, tend to be life altering, irreversible and totally avoidable. Like a doctor passing along a gloomy prognosis, I am heartbroken to see the look on peoples’ faces when I tell them how a choice they made will put them at a disadvantage for the rest of their lives.

And, as I said, many of these damaging financial choices are often avoidable.

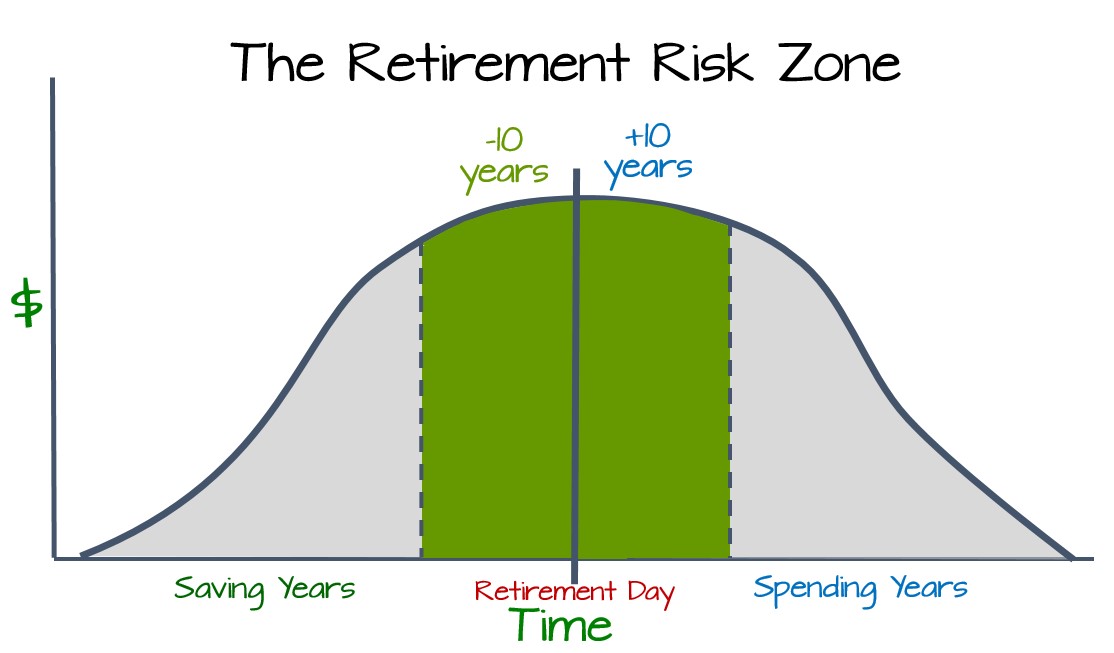
 The Retirement Risk Zone Years (TRRZY)

The years leading up to, and the early years of retirement are packed with important choices that can create turning points in your life. We call this period of your life ‘The Retirement Risk Zone Years’ (TRRZY).

TRRZY has aptly earned this acronym because this phase of life contains the highest concentration of high-impact choices that can lead to turning events, both good and bad, in people’s lives.

It is important to recognize that the number and frequency of tough and important choices increases during this time. In addition, the implications of choosing poorly intensify as both time and flexibility have turned from friend to foe. Successfully creating your best possible retirement years is directly linked to how well you navigate the challenging choices of TRRZY.

Over this nearly two-decade period we must adapt our thinking to a new reality. Strategies that served us well during our savings years can turn on their heads and start to work to our disadvantage as our flow of funds reverses from saving to spending. Those who fail to recognize and adapt to this new thinking have a high propensity for making poor choices, many of which they will regret in future years.

Turning Points during “TRRZY”

Continue Reading…