All posts by Financial Independence Hub

Buying a home with an Income suite? What you need to know

first-time-landlordBy Penelope Graham, Zoocasa

Special to the Financial Independence Hub

 As Canadian real estate becomes steadily more expensive, homebuyers are increasingly exploring new affordability options. Renting out a portion of your home to help offset mortgage costs has become a popular method – and with the price of an average detached house well past the $1 million mark in the Toronto real estate market, it may be the only way some buyers can move beyond condos and townhomes.

For these buyers, assuming the role of landlord in exchange for a bigger house or better neighbourhood seems a smart trade-off. However, renting out part of your property – especially when you also dwell there – can be a complicated undertaking, and requires extensive research and resources. Here’s what those considering the purchase of a home with secondary suite should take note of.

What is a secondary suite?

Also referred to as an income suite, secondary suites are separate units within a principal residence. It must have its own private entrance, kitchen, sleeping and living areas. In order to comply, and be protected by, your province’s Residential Tenancies Act (RTA), you cannot share any of these living facilities with your tenant, as they’re otherwise considered a boarder. Continue Reading…
Robo advisers will expand beyond investing to insurance & lending

img_85011
Invisor CEO Pramod Udiaver

By Pramod Udiaver

Special to the Financial Independence Hub

While the online advice industry is still relatively new to Canadian investors, the breadth of online financial services has been evolving quickly. This is good news for investors who are looking for more goal-based investing options and services that consolidate their various financial needs.

Goal-based investing considers a client’s goals and the steps needed to achieve them. This practice helps investors see their financial goals as easy-to-navigate paths, with clear beginnings and ends. It ensures investors fund their accounts based on desired results, rather than how much they think they might need. And it takes the uncertainty out of investing by showing exactly how and when each goal will be achieved.

While investing and insurance goals are not generally planned under the same service, insurance is an important part of any financial plan and the goal-setting process. Progress towards our goals can be thwarted by events like disability, serious illness, or the death of a loved one.

Role of insurance

We see that in many cases, even if one of these events were to occur, clients say they would still want to stay on a path to achieve their goals. Proper insurance can help them stay on track by replacing a portion of their income while they are disabled, allowing them to maintain a desired standard of living and keep saving. Life insurance can ensure that goals set for one’s family, like sending kids to good schools, allowing the surviving spouse to retire comfortably, or the desire to leave a legacy in the form of a charitable donation, can still be achieved.

Continue Reading…

What is goals-based investing?

Business People Employee Retirement Presentation Seminar ConceptBy James Gauthier, CIO, Justwealth

Special to the Financial Independence Hub

Most individuals are aware of the importance of investing – not everybody does it, but they know that it can be beneficial for their future.

For those who are able and engaged in investing, a good percentage will invest their savings through their financial institution, a financial advisor or some will do it on their own. Financial planning helps investors figure out questions such as “How much do I need to save?,” “How much can I spend?” or “What rate of return do I need to make?”

Before you attempt to answer these questions, you should be asking yourself the question “What is the objective of my investment?” The responses to this question can vary greatly, but might fall into one of the following categories:

• Saving for the short term (such as a down payment for a home in a few years)

• Saving for the long term (such as a retirement nest egg)

• Generating income (either as a primary or secondary source)

•Preserving your capital (looking to keep up with inflation or just very risk averse)

Continue Reading…

When and when not to hedge currency risk

depositphotos_16811249_s-2015-2By Tyler Mordy, Forstrong Global Asset Management

Special to the Financial Independence Hub

 An old Japanese proverb states “many a false step was made by standing still.”

So it is with currency exposures in investor portfolios. Consider the recent experience of Brazilian, Russian and even Canadian investors — to name a few countries with steeply depreciating exchange rates. By electing to remain invested in their domestic currency, they have all experienced a steep “loss” in their own global purchasing power (even if nominal values held up). An ostensibly conservative position has cost them dearly.

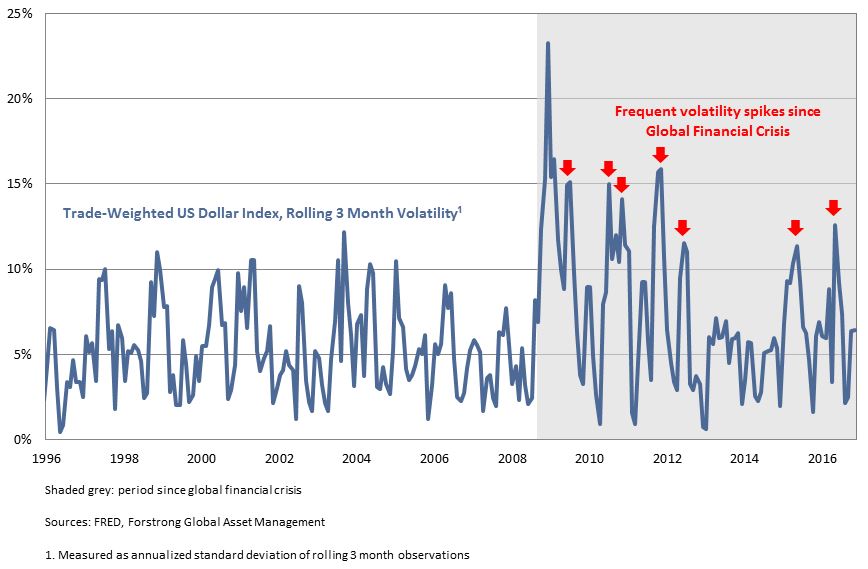
Welcome to the new, hyper-globalized world. Since the financial crisis, unorthodox policies — with central banks trying to outdo the effects of one another by plunging into a subterranean universe of quantitative easing and negative interest rates — have driven currency volatility much higher. Now, capital has a way of swiftly seeking out safe harbours and penalizing others who are not safeguarding their national currencies. Who would have thought the once-august Swiss franc would lose its safe haven status?

currency-chart-1-nov-2016

Indeed, currency exposures are having an outsized impact on portfolio returns. Currency-focused ETF vehicles could not have arrived at a better time, introducing yet another evolution in the portfolio management process.  Today, gaining global currency exposures is as easy as buying stocks.

Beyond the academic view

Continue Reading…

Which type of credit card is best for you?

Travel and tourism concept. Air tickets, passports and credit cards, tourism and planning, vector illustration
Travel a lot? A travel rewards credit card may be just the ticket.

By Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

 When it comes to choosing a credit card, it’s easy to feel overwhelmed by the number of different options available. Although it might seem simplest to choose one with your current bank or go with whatever your friends use, you could be leaving rewards such as cash back on the table by taking a one-size-fits-all approach.

Here are four common profiles and the best type of credit card for each.

Frequent flyer

Making the most of vacation days can be expensive, especially if you like to travel. However, you can often help offset these costs using a travel rewards credit card. There are some great travel rewards programs in Canada where you can start collecting points. But because each program is different, make sure you know how they work.

The BMO Rewards Program is a good example, because for every dollar you spend you can earn up to two points. You can then redeem 100 points for $1 back on a wide range of categories including flights, hotels, car rentals and even merchandise or gift cards. Your everyday spending can really start to add up – for example, if you spend $1,500 a month using the BMO World Elite MasterCard, after a year you would have enough points to redeem $360 in value.

Travel cards often also offer good value because most come with a range of insurance benefits such as lost or delayed baggage, trip delay or cancellation and medical coverage. You can then relax on your travels, knowing that if something does go wrong, you’ll be covered.

Big spender

If you like to use your credit card for most of your everyday purchases and bills, you should look to maximize your rewards with a premium rewards credit card. Many of these cards have an annual fee, but if you’re a big spender, the net reward from premium cards are often much higher because the earning potential is usually much higher than with no fee credit cards.

The best rewards cards typically fall into two categories – travel and cash back. If you’ve decided that you don’t fit into the frequent flyer category above, consider instead a cash back credit card. With this type of card, the amount you can redeem typically starts at around 1%, but can get as high as 4% or even more with special promotions.

Continue Reading…