Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Using arithmetic to crush closet indexers and fee scalpers


by Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

What is the profile of a fund that has the odds stacked against it?

For starters, “beta” index trackers that cover market capitalization-weighted indexes such as the S&P 500 may often lag their underlying index because of their fees, even though most of their expense ratios are tiny. Nevertheless, such funds may offer a better prospect than many active managers, who can’t get out of the way of their operating costs.

Another fund manager who is against the wall is the “closet indexer”: the career risk manager. These strategists claim to be coming up with great investments, but when you look under the hood, their holdings look just like their competitors’ funds. Then there is the manager who actually has a lot of unique holdings but high fees.

There is a fourth kind of manager who is not a market capitalization-weighted index strategist, a closet indexer or an expensive active manager. They have truly different holdings at digestible fees and higher active share.

To put this in context, a cap-weighted strategy would target an active share figure of 0% because it is trying to be exactly like the S&P 500, MSCI EAFE or some other major index. A closet indexing strategy may clock in at 30% or 40%. One that is totally different, with no holdings in common with its asset class, would have 100% active share.

Now, put active share in the context of fees: Using simple arithmetic, we can calculate the “hurdle rate” — popularized by Martijn Cremers at Notre Dame — which quantifies how well the active selections need to perform to cover their expense ratios. This really matters in picking a fund or ETF.

Path 1 is the worst. Sadly, trillions still sit in closet index funds that have low active share and high fees. Avoid these: Their existence is only justified if they somehow get past High hurdle rates.

Path 2 isn’t much better. These money managers at least have high active share, so they have the courage of their convictions, but they trip over their high fees. Their hurdle rates are Average.

Path 3 is a different breed, but just as bad as Path 2. These managers have low fees because they got the memo that the jig is up on huge expense ratios. But they are still closet indexing, hoping investors won’t notice their low active share. Their hurdle rates are Average.

Path 4 is hard to find. These are strategies that have both high active share and low fees. Their hurdle rates are Low: the sweet spot. Chances are good that a Path 4 fund is an ETF.

I put this in visual form in figure 1.

Figure 1: Visualizing the Four Paths

Find the Low Hurdle
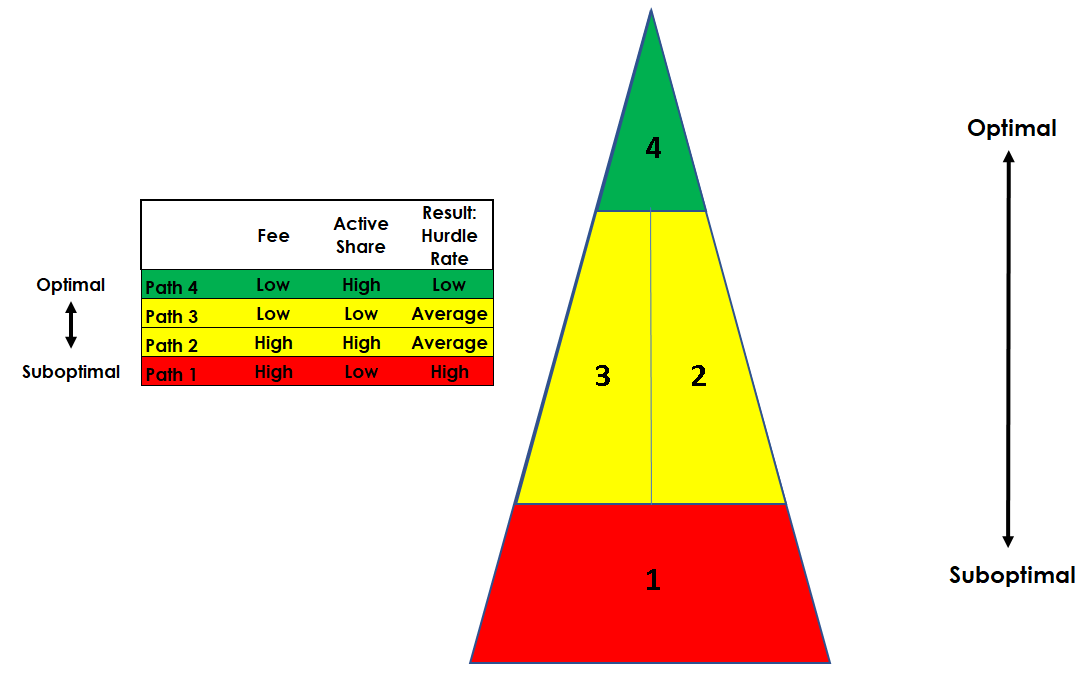
 

Figure 2 puts numbers to this concept, with hypothetical Path 1, 2 and 3 managers.

Start with the Path 1 closet indexer. It has 35% active share, meaning the other 65% of its holdings are found in the cap-weighted benchmark. It charges 0.80%, so the unique holdings need to outperform by 229 basis points (bps) to match the market’s performance. That figure is found by dividing the expense ratio by the active share. It’s a big hurdle rate. Continue Reading…
Smart ways to divvy up your tax refund

Situation: The income tax refund is a welcome sight for many taxpayers.

My View: Park it temporarily to reflect on its best use before allocating it.

Solution: Evaluate family needs and options that provide lasting benefits.

Income tax filing season is under way once again. Accordingly, I examine some smart ways to apply your tax refund. First, a little trivia:

For what year did Canadians last file a 1-page Federal income tax return?
It was the 1949 tax year.

I think of allocating the income tax refund loosely within these categories. For example, you can spend it, save it, invest it, reduce debt and help others.

Start by parking the refund into a saving account to resist impulse, say for 30 to 60 days. That provides you sufficient time to reflect and evaluate your needs and best options that apply.

Try your utmost to arrange lasting usefulness from this source of cash. Many of the allocations you will make are not reversible.

Everyone can reap benefits from these simple best practices. I summarize some sensible ideas in dealing with tax refunds:

Reduce debt

  • Repaying credit card balances are top notch, risk-free allocations.
  • Trimming a line of credit, mortgage or student loan is very desirable.

Invest it

  • Contributing to the RRSP boosts the retirement nest egg.
  • Adding to the TFSA generates tax-free investment income.

Help others

  • Donating to a charity of your choice is a noble cause.
  • Helping out someone less fortunate than you is generous.
  • Making RESP deposits helps pay the rising costs of education.
  • Funding the RDSP for a special needs family member is unselfish.
  • Lending it at the prescribed rate to the lower tax bracket spouse.
  • Assisting an adult child to purchase a vehicle or residence.

Save it

  • Leaving it in your saving account is a worthy choice.
  • Supplementing your family business capital is worthwhile.
  • Adding to your investment plan is productive strategy.
  • Improving your career or education fulfills goals and dreams.
  • Rebuilding the family emergency account is beneficial.
  • Setting funds aside for the next income tax instalment.

Spend it

  • Replacing an aging vehicle and appliance helps.

The new cost of Divorce

By Elena Hanson

Special to the Financial Independence Hub

On December 22, 2017, the largest U.S. tax reform in over 30 years was signed into law by U.S. President  Donald Trump. The new law brought with it several important changes that affect individual taxpayers who are going through, or have gone through, a divorce. As if divorce isn’t already costly enough!

Prior to the 2017 Tax Reform Act, Section 215 of the U.S. Internal Revenue Code  allowed individual taxpayers to claim alimony payments as a legitimate deduction. The deduction was permitted because section 71(a) of the IRC required the recipient spouse to include the alimony received in his/her adjusted gross income.

For tax purposes, a payment is considered alimony if all of the following criteria are met:

  • Each spouse files a separate return
  • Payment is made in cash (including check or money order)
  • Payment is made to a spouse/former spouse pursuant to a divorce or separation agreement
  • The divorce or separation agreement does not specify that the payment is “not alimony”
  • The spouses/former spouses are not living in the same household when payment is made
  • There is no requirement to continue making payments following the death of the recipient spouse
  • The payment is not treated as child support or a property settlement.

However, under the new Act alimony payments are no longer deductible on U.S. income tax returns if the separation or divorce agreement is executed after December 31, 2018. In addition, the person receiving alimony no longer has to claim these payments on their tax return as part of their gross income.

These changes are permanent, unlike other personal tax measures included in the Tax Reform Act. For those who have agreements in place prior to January 1, 2019, these changes do not apply because the original provisions are grandfathered into the agreement. But, as of January 1, if changes are made to the original agreement, the amended agreement must state that the new rules will not apply, or else they will. In other words, the parties must “opt-in” to the 2017 provisions if there is a modification of the separation or divorce instrument after 2018.

Prior to these changes, the recipient spouse had something of a bargaining chip when negotiating alimony payments. Why? The paying spouse could deduct the payments dollar-for-dollar, making the amount of the alimony payment almost a non-issue as it would come back to the party paying it in the end. Now, it is likely that negotiations will become a more drawn-out affair as divorcing couples struggle to come to an agreement as to what is fair to both parties under the new law.

With any major tax law overhaul, we can always speculate as to the rationale for certain changes. This is one of those situations where there doesn’t seem to be any real benefit to either party and, in fact, simple calculations show that these changes typically result in less after-tax income for both the payor and the payee. Perhaps, U.S. lawmakers were looking out for families by making divorce a less-attractive option in times of trouble?

Overall, these changes are quite a departure from laws that have been in place for decades, and they will bring upheaval and adjustment for divorce lawyers and divorcing taxpayers alike. That’s why it’s so important to consider all the factors, and geographies, involved when drafting up new settlement agreements.

What if recipient spouse resides in Canada?

Now let’s consider a twist to the post-marital arrangement. The spouse paying alimony is a U.S. resident, and the recipient spouse is a nonresident alien, residing in Canada. Domestic laws in Canada remain unchanged in that the Canadian resident receiving alimony from the U.S. must report the income on their Canadian tax return. The result is a situation where the alimony payment is now taxed twice – once in the U.S. where alimony is no longer deductible, and again in Canada where it is taxable income for the recipient. Fortunately, there is relief under the U.S.-Canada Income Tax Convention (1980) which we will call the Treaty. Continue Reading…

Key technologies for smarter financial decisions

By Sia Hasan

Special to the Financial Independence Hub

Have you ever considered going paperless? The switch might seem daunting at first, but you will find that electronic options can give you greater freedom and reduced expenses. Whether you’re in business or healthcare, the following technologies will transform your company into a more profitable and financially independent institution.

Cloud Technologies

Cloud computing uses remote servers on the internet for managing data, rather than storing files on a personal computer or external hard drive. When you store data in the cloud, you’ll enjoy higher speeds and greater security. Even if a computer or hard drive crashes, all of your files will still be safely stored in the cloud. In addition, cloud technologies can be a lot cheaper than more traditional options. With cloud computing, you don’t have to pay for unnecessary hardware or software, there will be fewer labor costs. You will also have increased productivity, saving you both time and money.

Strategic Analytics

Implementing analytics can help you better prepare for the future. These forecast technologies use past data to predict future events for your business. With analytics, you can use mathematical approaches to determine the most valuable resources to invest in. Define specific business goals and create strategies that will allow you to test changes on a smaller scale. Analyze costs, advertising, product management, and your ability to meet customer demands. Making small changes now will help you save money in the long-run.

Artificial Intelligence (AI)

Machines are revolutionizing the work industry by learning how to perform human-like tasks. From self-driving cars to bots, AI is making it easier and faster to maximize efficiency. Al offers many benefits, like faster performance, reduced error margins, and lower costs. AI can also achieve breakthroughs by recognizing blind spots and detecting trends. While the initial cost is high, using AI long-term will save you money and increase your efficiency. Instead of replacing workers, AI supplements the work that your employees are already doing. AI can perform smaller tasks, like updating the company website, managing finances, tracking inventory, and finishing payroll. By automating these time-consuming tasks, workers are free to focus on important duties, like human interaction.

Project Management Software

Project management software keeps teams on the same page, while helping managers to better organize tasks and data. Improve your efficiency by storing all of your information in one, easily-accessible location. Simplify team collaboration through crowd-sourced documents and shared to-do lists. Keep track of schedules, budgeting, and resource allocation. Easily communicate questions and concerns to other team members. Track time and expenses, paying attention to areas where you can improve efficiency and cut costs.

Healthcare Software

Going paperless in the healthcare industry has never been easier. With the variety of new software available, you can improve the way you schedule, treat, and communicate with patients. Continue Reading…

FP: Bank on Yourself — Why women need to focus on Financial Independence with or without a spouse

My latest Financial Post column looks at an upcoming book, Bank on Yourself, which focuses on how Canadian women need to focus on Financial Independence, whether or not they are currently part of a couple. Click on the highlighted headline here for the full review: Why Women shouldn’t let a solo retirement catch them by surprise. The review also appears in the print edition of Tuesday’s Financial Post (page FP 3, April 2, 2019).

The book, which is being published this month (April) by Milner & Associates, is co-authored by a lifelong single woman, Ardelle Harrison, and a financial advisor, Leslie McCormick. McCormick is a Senior Wealth Advisor with Scotia Wealth Management but Ardelle is not a client.

The subtitle says it all: “Why every woman should plan financially to be single. Even if she’s not.”

The authors say 90% of women will end up managing their own finances at some point, whether because of divorce, widowhood or because they never married in the first place. And because women tend to live longer, expect five female centenarians for every male who reaches 100 years (according to the 2016 Canadian census).

Allegedly one of women’s biggest fears is ending up in old age as a “bag lady” destitute on the streets. In fact, 28.3% of unattached women live in poverty and single older women are 13 times more likely to be poor than seniors living in families, the authors say.

They cite Pew Research’s eye-opening finding that when today’s young adults reach their mid 40s and mid 50s, 25% of them are likely to never have been married, and that by then “the chances of marrying for the first time after that age are very small.” (Whether by choice or circumstance.)

But even those who do “couple” earlier in life may not always remain in that state. A 2013 Vanier Institute of the Family report says 41% of Canadian marriages end before their 30th wedding anniversary. 68% of divorced couples cited fighting over money as the top reason for the split. 2011 Canadian census data shows the average age at which women are widowed is 56.

Multiple Streams of Income

A key concept emphasized throughout the book is having Multiple Streams of Income, at least three in Retirement. Employment income is the springboard to other income streams,  including employer pensions.

A second is government benefits unlike CPP and OAS. Other streams are business, investment and real estate income, and annuities. Home owners have a potential backup in their home equity, although the authors rightly say “Debt is not something you want in retirement.”

I asked McCormick if these principles apply equally to single men. General financial planning principles apply across genders, she replied, but women have longer life expectancies, so when you add the gender wage cap, it’s harder for women to build wealth. Female baby boomers can expect to outlive their spouses by 10 to 15 years, “yet so few women plan for it.” While 31% of women view themselves as being financially knowledgeable, 80% of men do.  Her hope is the book will help bridge that gap. So might a planning tool at her Plan Single website (www.Plansingle.ca).