Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Retiring at home — and how to get the funds to do it

By Darlene Vilas

Special to the Financial Independence Hub

I’ve spent many years helping a lot of retirees to stay in their home. So, I wasn’t surprised when a survey by HomeEquity Bank and IPSOS revealed that 93% of Canadians aged 65+ are determined to retire at home.

For people with a healthy pension and retirement savings, staying in their home is rarely a problem. However, many Canadians have inadequate retirement savings. According to a report by CIBC, 30% of people have no retirement savings at all, while another 19% have saved less than $50,000. I help people with lower retirement income to understand the financial options available to them, so they can retire comfortably in their home.

Why staying put is so important

According to HomeEquity’s research, maintaining independence is a key reason for retirees wanting to stay in their home, followed by staying close to family, friends and their community.

Many of my older clients find just the idea of moving to be very stressful. They don’t like the thought of downsizing, which means leaving behind loved ones and places they’re familiar with.

I can understand that, so I try to help people stay in their home, whatever their financial situation. Thankfully, for homeowners, there are several options available.

The financial tools that can help you stay at home

Taking out a mortgage or a line of credit can allow you to cash in on some of your home’s equity. However, the mortgage option is becoming increasingly difficult for retirees. With the new mortgage stress test, you have to qualify at a much higher rate than before, which means you can now borrow much less. Plus, taking on mortgage payments for up to 20 years can put a strain on your retirement income. If you miss some payments, you could lose your home.

A home equity line of credit can be a good option if your income qualifies.  They are fully open and can be repaid at any time without penalty. This is a very helpful option for homeowners who would like to access cash easily if they experience unforeseen home expenses such as emergency repairs to the home. Payments are typically interest only, which keeps your monthly obligation at a minimum.   The downside of a home equity line of credit is they are callable at the discretion of the bank.  This means you could be forced to sell your home to repay the line of credit.

With a reverse mortgage, you can borrow up to 55% of your home’s value. You never have to make a mortgage payment and you’ll never be forced to move out. Many of my clients use a reverse mortgage as an efficient way of cashing in some of their home’s equity. Because there are no regular mortgage payments, it can help them to greatly improve their financial situation, boost their disposable income and live the kind of retirement they’d hoped for.

Those people concerned about maintaining their home’s equity can make monthly interest payments, but the nice thing is, they don’t have to. Continue Reading…
New mandatory risk rating is misleading Canadian investors

By Nick Barisheff (Sponsor Content)

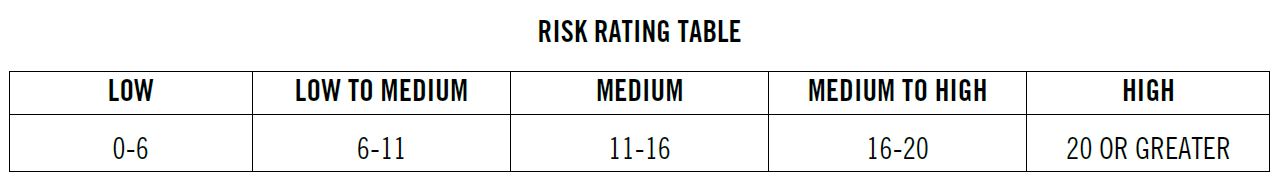
Canadian securities regulators may be putting investors at risk. They implemented a new mandatory risk weighting system in September 2017 based on 10-year Standard Deviation. Every Canadian mutual fund and exchange-traded fund (ETF) must now include a risk rating based on the following:

Before implementing this policy, the Ontario Securities Commission (OSC) asked for submissions from the industry. These can be viewed here.

Over 50 submissions were received (mine included.) and out of those, three warned about the deficiency that Standard Deviation does not differentiate between upside and downside volatility.

Scott C. Mackenzie of Morningstar made a particularly succinct comment:

“A conservative investor’s portfolio that is missing a key sector or asset class, essential for prudent diversification (and risk reduction), may demand the inclusion of a small amount of a concentrated sector mutual fund or ETF. A single measure risk score for such a vehicle may be higher than recommended for the investor and they are consequently dissuaded from incorporating it. The irony and potential downside is that the risk of the conservative portfolio may actually be higher than otherwise would have been had the investor included the diversifying investment. “Diversification as a risk-reduction activity is a sensible approach, practiced by many, and supported by decades of investment research.” http://www.osc.gov.on.ca/documents/en/Securities-Category8-

Comments/com_20140312_81-324_mackenzies.pdf

There are two major flaws with the methodology:

  1. It does not differentiate between Standard Deviation and Downside Deviation; and
  2. It measures individual portfolio components rather than the overall Standard Deviation of the entire portfolio.

This policy will not protect investors from experiencing losses, but may prevent investors from structuring portfolios for reduced volatility, optimal performance and effective diversification. The resulting reduction in investment demand in sector funds will result in a negative impact for many Canadian public companies.

The overall weakness of this approach is best exemplified by the fact that Bernie Madoff’s fund had the lowest Standard Deviation in the industry for over 30 years – yet investors lost most of their money.

David Ranson of H.C. Wainwright & Co. published a report entitled “Why Standard Deviation Won’t Serve to Classify the Risk of a Portfolio.” This report details why Standard Deviation is a poor and overly simplistic approach to measuring the risk of a portfolio.

“The riskiness of an investment product cannot be represented by the Standard Deviation (volatility) of its historical returns, or by any other single statistic … On a real risk scale, cash could be assessed as risky and gold as safe.” 

http://bmg-group.com/wp-content/uploads/2017/12/why-standard-

deviation-wont-serve-to-classify-the-risk-of-a-portfolio.pdf

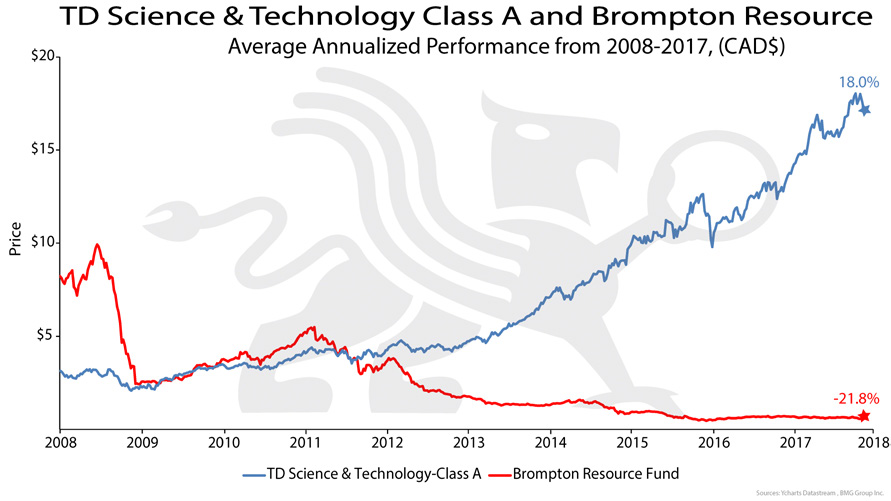
As an example of how flawed this policy is, Morningstar Canada lists 9,412 equity classes of mutual funds. Of these,1,932* have 10-year performance histories. The best-performing fund is the TD Science and Technology Fund, which achieved an 18.00% 10-year annualized return net of MER. A $10,000 investment in 2007 would now be worth $66,554*.

On the other side of the performance scale is the Brompton Resource Fund. It ranks as 1,932*(last) in performance and has experienced a-21.8% annual decline over the same 10-year period. A $10,000 investment ten years ago would now be worth only $643*.

*As of July 18, 2018

The 10-year (2008-2017) Standard Deviation for the TD Science and Technology Fund is 17.7% (MEDIUM to HIGH RISK) and for the Brompton Resources Fund it is 29.57% (HIGH RISK). However, the Downside Deviation is 10.6% (LOW to MEDIUM RISK) for the TD Fund and 25.7% (HIGH RISK) for Brompton Fund.

It should be obvious, even to the unsophisticated investor, that the risk of these funds that are at opposite ends of the performance spectrum is not similar.

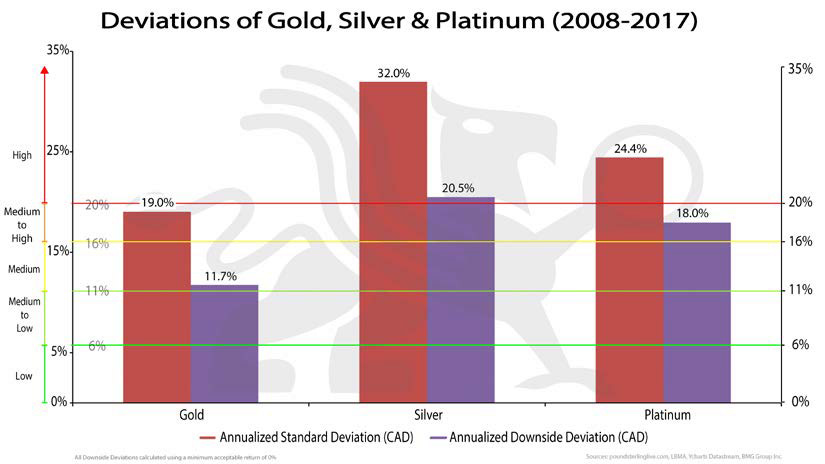
This flawed methodology is more pronounced when it comes to physical bullion funds such as the BMG Funds. According to this methodology, the Standard Deviation for gold results in a MEDIUM to HIGH risk rating. Silver and platinum would be rated HIGH RISK.

This new risk rating methodology is in direct contradiction to the suggested risk rating for gold established by the Basel Committee on Banking Supervision (BCBS). BCBS brings together regulators from 28 countries, and establishes rules governing the appropriate level of capital for banks. The current version of these rules, known as Basel III, is a key element of the international regulatory reform agenda put in motion following the global financial crisis of 2008. During the 2008 financial crisis, gold was used in international settlements as a zero-risk asset after many decades of being sidelined in the monetary system. Gold’s old emergency usefulness resurfaced, albeit behind closed doors, at the Bank of International Settlements (BIS) in Basel,Switzerland. Continue Reading…

5 surefire ways to stay out of Debt

By Gary Bordeaux

Special to the Financial Independence Hub

In the modern world, there are two types of debt: good bad and bad debt. Good debt would be considered financing something that has the potential to go up in value, like a home or a small business. Bad debt would be considered consumer debt like jewelry, designer clothes, and luxury cars. These things tend to depreciate. People typically get into trouble financially when they start going into debt with consumer goods or things they really don’t need.

1.) Create a budget

Unless you are already financially well-off, you are going to need to create a budget for you and your family. This is the single biggest way not to go into debt. Why? Because you are tracking every dollar you spend. Start out by listing your monthly income after taxes at the top of the budget, then list your expenses below that. If you don’t have a surplus of money after all your expenses are accounted for, you are either spending too much money or you are not making enough money. Whatever the case may be, adjust your budget accordingly.

2.) Quickbooks

The Quickbooks online platform by Intuit is probably one of the best online financial tools you can use for your business. In general, it is an online accounting software that helps manage your finances for you. With an easy Quickbooks online payment, you can pay people and you can receive money too. In the end, business finances can get pretty confusing. Quickbooks allows you to track your finances more easily. Also, Intuit has a budgeting app called Mint. I use Mint quite often and it tracks all my transactions and spending activity. It also tracks your budgets, monthly cash flow, and your credit score along with many other investments and other accounts.

3.) Emergency fund

Let’s face the fact that bad things happen to good people. When these setbacks occur, people need money set aside to protect themselves from debt. This is what an emergency fund can do. First, start by putting away a simple $1,000 just in case an emergency happens. Continue Reading…

How to Retire debt-free

By Laurie Campbell

Special to the Financial Independence Hub

These days, don’t be surprised to find a senior citizen standing behind the counter of your favourite fast food spot taking your order instead of a braces-wearing teen. What retirement looks like today has changed quite significantly from what it was even just ten years ago, and there’s no stopping this trend. More and more seniors are staying in the workforce, and for many of them, they have no choice.

Last June for Seniors Month, our agency, Credit Canada co-sponsored a seniors and money study that looked at the financial difficulties Canadian seniors are facing; the results, while shocking, were no surprise.

As a non-profit credit counselling agency, our counsellors are on the forefront of what’s happening when it comes to people and their financial hardships, and we are seeing a large number of people who should be starting to settle into their “golden years” still working, maybe even taking on an additional side job, just to pay off their debt, let alone get a time-share in Florida.

When we conducted our study in June 2018, it revealed that one-in-five Canadians are still working past age 60, including six per cent of those 80 and older. And while one third do so simply because they want to — which is fantastic, kudos to you — 60 per cent are still working because of some form of financial hardship, whether it’s too much debt, not enough savings, or other financial responsibilities, like supporting adult children.

The truth is the golden years have been tarnished, and I don’t know if we’ll ever get them back.

Half of 60-plus carrying some form of debt

Many of today’s retirees are living on fixed incomes, making them vulnerable to unpaid debt. In fact, our study revealed more than half of Canadians age 60 and older are carrying at least one form of debt, with a quarter carrying two or more types of debt. What’s even more alarming is that 35 per cent of seniors age 80 and older have debt, including credit-card debt and even car loans.

Staring at the problem isn’t going to help, nor is hiding from it. The best thing we can all do is to face the facts head-on and devise a plan of action that we know will work, whether it’s getting rid of any debt while building up savings, taking on a side job, delaying retirement by a few years, or all of the above.

Sizing up Government support

Before delving into the numbers it’s important to understand what income you can expect to have during your retirement. A few numbers have been compiled here as an example, but if you wanted to get more detailed information you can visit the Government of Canada website and click on the Canada Pension Plan (CPP) or Old Age Security (OAS) pages.

So, let’s get started by taking a look at 2017. Continue Reading…

Retired Money: How to avoid pre-retirement financial stress syndrome

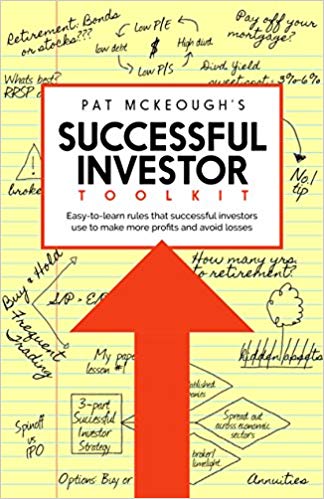
My latest MoneySense Retired Money column looks at how near-retirees can avoid what author Patrick McKeough calls “pre-retirement financial stress syndrome.”

That’s a syndrome he identifies in his new book, Pat McKeough’s Successful Investor Toolkit. McKeough is a regular contributor here at the Hub and you can find the full MoneySense review of his book by clicking on the highlighted text: Investing tips for retired Canadians.

The book is a distillation of McKeough’s long investment career, honed first at The Investment Reporter, and in recent years his own firm, The Successful Investor, and its stable of newsletters. As a member of his Inner Circle and TSI Network, I have long been a proponent of his common-sense approach to investing. He is remarkably consistent in his insistence that investors of any age rely mostly on a conservative portfolio of quality dividend-paying stocks spread among the five major economic sectors (Manufacturing & Industry, Resources, Finance, Utilities and Consumer). And, he never fails to remind you, steer clear of stocks in the crosshairs of what he calls the “broker/media limelight.”

His newsletters are focused variously on Canadian stocks and U.S. and international stocks, and in recent years he has increased his coverage of ETFs.

A cure for PRFSS: Work longer or refine your spending

So what is“pre-retirement financial stress syndrome,” or PRFSS? PRFSS strikes when mature investors realize they may not have enough savings to generate the stream of retirement income they’d been counting on. While some investors are searching for one last desperate “hail Mary” gamble, McKeough advises the opposite: aiming for safer investments.

And while it may not be what some may want to hear, he suggests those suffering from PRFSS adopt one or both of these two solutions: work longer and/or refine your spending. He challenges them to “turn frugality into a game.”

With his focus on stocks, it’s no surprise that McKeough is not keen on bonds, even for retirees and those on the cusp of it. Continue Reading…