Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

How to make money online for your business marketing

By Kristen Pearson

(Sponsored Content) 

When you think of something like business marketing, it’s important to consider that it’s not just limited to making people attracted to certain aspects of your business. Given the scope and kinds of business marketing you can pull off, you are actually more than capable of utilizing your business appeal and tap into your potential audience to make means to earn more money for your business outside your products and services. When you read the article below, consider trying to apply these methods to your overall business strategy, and you might find out some new way of creating passive income for your various needs.

It’s important to understand, however, that while there are a lot of ways you can make passive income — in both through your personal endeavors and through marketing itself — you shouldn’t forget to maintain these income streams’ performance. In fact, some of these passive income ideas can actually boost your marketing efforts as well, making it quite the stone that hits the proverbial two birds. This can be very helpful if you’re stuck in a bind and want to use your resources efficiently, as the methods can not just get you potential sales and boost your marketing, but even earn you additional income.

Tips on making money online

With the above in mind, it may be important to consider as early as now that business marketing does hold a lot of potential to attract people to your business. However, did you know you can make passive income out of it? That’s right, try to review the journalreview.org passive income methods below and see if you can actually apply this to your business:

Make your blog suitable for outreach 

Blogger outreach is one of the most relied-upon methods of gaining traction with your audience, though it can be challenging using this to earn passive income as blogging is really more of an investment. When you make a blog, don’t just focus on your rankings and your keywords, but rather to write content relevant enough for your audience across a long period of time. This not only encourages other bloggers to source you, but you can build yourself a reputation of publishing relevant content in your blog. Give it time, and other blogs will want to guest post in your blog – and that’s when you can start charging them on piggybacking on your rankings. And if this is a competitor or someone in a niche, you’re likely going to get samples and other benefits to review as well.

Maximize content releases by making them on sale

Blogging is free: most of the time, anyway. However, if you want to provide more technical and more precise knowledge to your audiences, you always have an option to make them exclusive content. Provide your more relevant information through ebooks and other releases that your fans will want to buy from you, all the while proving to them you provide relevant content through your blog. You’d be surprised how well ebooks and other exclusive content can sale if you get them out there enough.
Encourage fans and audiences to take up an online course

If you know you and the members of your team are experienced enough in your field, you can actually offer a course to help others jumpstart a career in your niche. You can gather your meeting data and your notes in order to create lectures subscribers and loyal customers can avail for a certain fee. This not only puts you in a position to spread learning, but being able to actually teach what you know puts you in a position of relevance. What better way to establish authority than to do things that make you appear like one? Continue Reading…
Getting the best bang for your buck with everyday purchases

By Sia Hasan

Special to the Financial Independence Hub

You work hard for your money, so it makes sense that you would want to stretch your dollar as far as possible. If you are like many other hard working adults, you may splurge here and there on a cup of coffee or a matinee movie. However, most of your take-home pay may go toward everyday or typical purchases. These may include food, gas, clothes and more.

It may seem challenging to stretch your dollar in these essential areas, but rest assured that there are several strategies you can employ to get the most bang for your buck. Before you make another purchase on regular or everyday items, consider how these tips can benefit you.

Choose your payment method carefully

The primary payment methods for standard purchases are cash or credit cards. Cash may be in the form of hard currency, checks or a debit card. Many people believe that paying with cash or a cash alternative is a smart option because it helps you avoid taking on expensive debt. It is true that debt can cost you money.

However, if you use credit cards responsibly, a credit card may be a better payment option. Consider that you can make all your regular purchases with a credit card, and you can pay the full balance off each month. Therefore, no interest is accrued, and there is not a cost for using the credit card. You may enjoy the benefit of bolstering your credit score with responsible use of your credit card. Keep in mind that higher credit scores may qualify you for a lower rate on a mortgage, a car loan, insurance rates and more. Therefore, this payment method can yield tremendous savings over time.

Take advantage of Credit Card Rewards

When you make purchases with credit cards regularly, you may also enjoy the additional benefit of earning rewards points. You can begin by searching for a good credit card for average credit and comparing rewards programs or opting into the rewards program on an existing account. Pay attention to the fine print as you compare programs. Some credit card rewards programs, for example, limit the points that you can earn within a specified period of time. Other programs require you to use the points within a certain period of time. These rewards may essentially give you cash back on your purchases, or the points may be redeemed for other items with financial value.

Shop around

Even when you take these steps to stretch your dollar, there may be other ways to save as well. Shopping around is easier to do than ever because of the Internet. Continue Reading…

Why we are taking Social Security at age 62

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

We decided to take Social Security at age 62. We know there are as many ways to consider this decision as there are days in a year. And many experts advise against taking social security “early” so that you get a bigger check at full retirement age.

It is hard to argue against that.

We have always lived an unconventional lifestyle and the fact that so many experts agree on waiting for payment gives us pause for thought. Here is our logic.

First, the S&P 500 index has averaged over 8% per year, plus dividends, since we retired in 1991. If we take social security early and invest it, we won’t be losing the 8% per year the experts claim is the annual increase of waiting – although one is guaranteed and the other is not. Maybe the markets will trend sideways or go down or even up, no one knows.

For the last 27 years we have lived off of our investments through up and down markets, so investing the monthly check is definitely an option. More likely, we will just not spend our stash and look for opportunities in the markets as our cash positions grow. Plus we have control of the money at this point, adding to our net worth.

Next let’s look at some numbers.

11 years to break even

For easy math, say at 62 you are going to receive $1000.00 per month in benefits, but if you wait until you are 66, your payment will be $1360 ($1000 x 8% for the four years you have waited). Sounds great, right?

However, you would have missed receiving $48,000 dollars in payments from the previous 48 months. How long is it before you make that money back? Using this example it would take 133 months or a little over 11 years ($48,000 divided by $360) and that would put us at 77 years of age, just to break even. In that time frame, the Social Security we are receiving plus our investments should grow far outpacing the extra money received by waiting.

For some people deferring until their full retirement age could make sense, especially if they do not have the assets to support themselves, are poor at handling money or if they are still working. However, this is not our situation and therefore we decided to take the money and run.

It’s really a question of who you think can handle your money better; You or Uncle Sam?

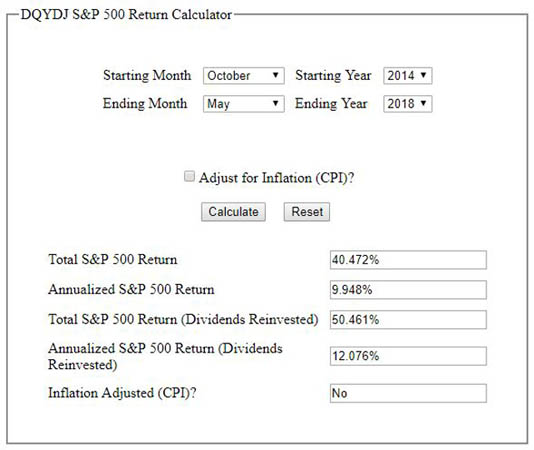
Update: The illustration above shows the return of the S&P 500 Index since we took Social Security at 62.

Billy and Akaisha Kaderli are recognized retirement experts and internationally published authors on topics of finance, medical tourism and world travel. With the wealth of information they share on their award winning website RetireEarlyLifestyle.com, they have been helping people achieve their own retirement dreams since 1991. They wrote the popular books, The Adventurer’s Guide to Early Retirement and Your Retirement Dream IS Possible available on their website bookstore or on Amazon.com.
.

Retired Money: Should you worry a large TFSA will trigger a CRA audit?

MoneySense/Shutterstock

Should you worry that a large TFSA will trigger a CRA audit? My latest MoneySense Retired Money column looks at a legal debate between the Canada Revenue Agency and taxpayers who have succeeded too well in growing their Tax-free Savings Accounts (TFSAs) with shrewd investing. You can access the full story by clicking on the highlighted headline: Why the CRA is targeting some TFSAs in court. 

If you’ve contributed regularly to the TFSA since it began in January 2009 you now have $57,500 of cumulative contribution room. With decent growth, it’s easily possible to have accumulated $100,000 in a TFSA by now: in fact, the CRA told me for the article that of the 13.5 million TFSA accounts that existed by 2016, 18,000 have balances of at least $100,000 (a number that includes myself and my own Millennial daughter, thanks to a few good FANG stock picks).

A Globe & Mail article last week profiled several ordinary Canadian investors and financial bloggers who have TFSAs of at least $100,000. See How to Grow your TFSA: Tips from Financial Bloggers to Fatten Your Account.

My MoneySense article quotes an unnamed investor who is being audited because his TFSA has grown to $500,000, owing to  timely growth of some private technology companies. He doesn’t think $100,000 is enough to trigger an audit but suggests $250,000 may be. In other words, the CRA may be fine with TFSA doubles but five-baggers will invite scrutiny and ten-baggers most certainly so.

But the real controversy involves TFSAs that are run as de facto securities trading businesses. The Globe highlighted this latest crackdown in an earlier article in July but was merely the latest of a series of TFSA audit scares that have been surfacing virtually since after the first year the program existed.

Shrewd stock-picking is not “aggressive tax planning” 

Some of those earlier audits involved TFSAs that soared because they held private companies but my guess is that, as in my own case or that of my daughter, the vast majority of TFSA holders are neither day traders nor experts in investing in private companies. We only buy exchange-traded funds or blue-chip North American stocks, including the FANG tech giants (Facebook, Amazon, Netflix and Google).

True, depending on when you bought them, it’s quite possible TFSA investors may have experienced 5- or even 10-baggers on stocks like Facebook, Amazon or Netflix. I doubt many investors would make concentrated bets on just one or two of these but if they did, then a $250,000 TFSA would not be inconceivable. That might invite scrutiny from the CRA but I strongly doubt they’d have a case for running a securities business.

Based on the CRA numbers cited in the MoneySense column, Tim Clarke estimates the CRA would have to audit 9,000 TFSAs in order to “recover” the amount of tax specified in the July G&M column that sparked this latest round of TFSA audit worries.

“I love how they say successful traders are conducting ‘aggressive tax planning’ “, Clarke told me in an email, “The purpose of TFSAs was stated in the budget that announced them to be a vehicle to allow taxpayers to save for retirement and other legitimate purposes. How can being successful at that be aggressive tax planning?”


TFSAs remain a critical tax-shelter for retirees

If you’re a retiree or close to it, presumably your TFSA will be invested fairly cautiously, just like an RRSP or RRIF, which means some combination of blue-chip dividend-paying stocks and fixed income. The TFSA is too valuable a tax shelter to get scared by audits of a handful of aggressive investors. Keep in mind that unlike RRSPs, you can still keep adding to your TFSAs well after age 71, to the current tune of $5,500 a year, and perhaps with future inflation adjustments.

There’s no reason that a retiree shouldn’t keep adding to their TFSAs until their late 90s or even beyond: not necessarily with “new” money but from post-tax money liberated from non-registered investments or after tax is paid on forced annual RRIF withdrawals.


Want an affordable neighbourhood with top Schools? Head for the ‘Burbs

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

The mantra for real estate shoppers is typically “location, location, location” – but for those with kids in tow, it might as well be “schools, schools, schools.”

For parents, whether or not a home is close to a highly-ranked educational institution is a top consideration, alongside affordability, number of bedrooms, and parking.

In fact, living within a certain school catchment can significantly impact one’s home value: even homes located across the street from one another that are in different school zones may see that difference reflected on their home listing prices.

EQAO school ranking and home price are especially correlated in high-demand urban centres, such as the City of Toronto, where home buyers pay a premium of hundreds of thousands of dollars to live within their coveted catchment.

For example, in Etobicoke, where the top EQAO-ranked school of Lambton Kingsway Junior Middle School boasts a score of 3.2 (out of 4), home buyers would pay a premium of $821,580 to dwell nearby. In York, that premium is $689,178 to live near Humbercrest Public School (3.1), and $444,183 to be close to CD Farquharson Junior Public School in Scarborough (3.3).

Exploring affordability in the Greater Golden Horseshoe

However, those who wish to live close to a top-ranked school at a more affordable price are wise to head to the suburbs: according to recent data compiled by Zoocasa, the correlation between school ranking and average home price isn’t as strong in surrounding Greater Golden Horseshoe markets.

Consider the city of Hamilton, located just west of Toronto along the shores of Lake Ontario. Also known as “Steeltown” or the “Hammer” for its roots as a steel manufacturing centre, it’s now highly sought for its growing “eds and meds” industry; and the fact that detached Hamilton houses with large lots are relatively inexpensive.

Those looking to live close to the best schools have many options in Hamilton; for example, one of the top-ranked schools, Sacred Heart Separate School (2.9) is located in East Hamilton, where the average home price clocks in at $396,964. In upscale Ancaster, where the average home sells for $838,337, is the similarly-ranked Immaculate Conception Elementary School, illustrating similar education standards are available for buyers regardless of home budget.

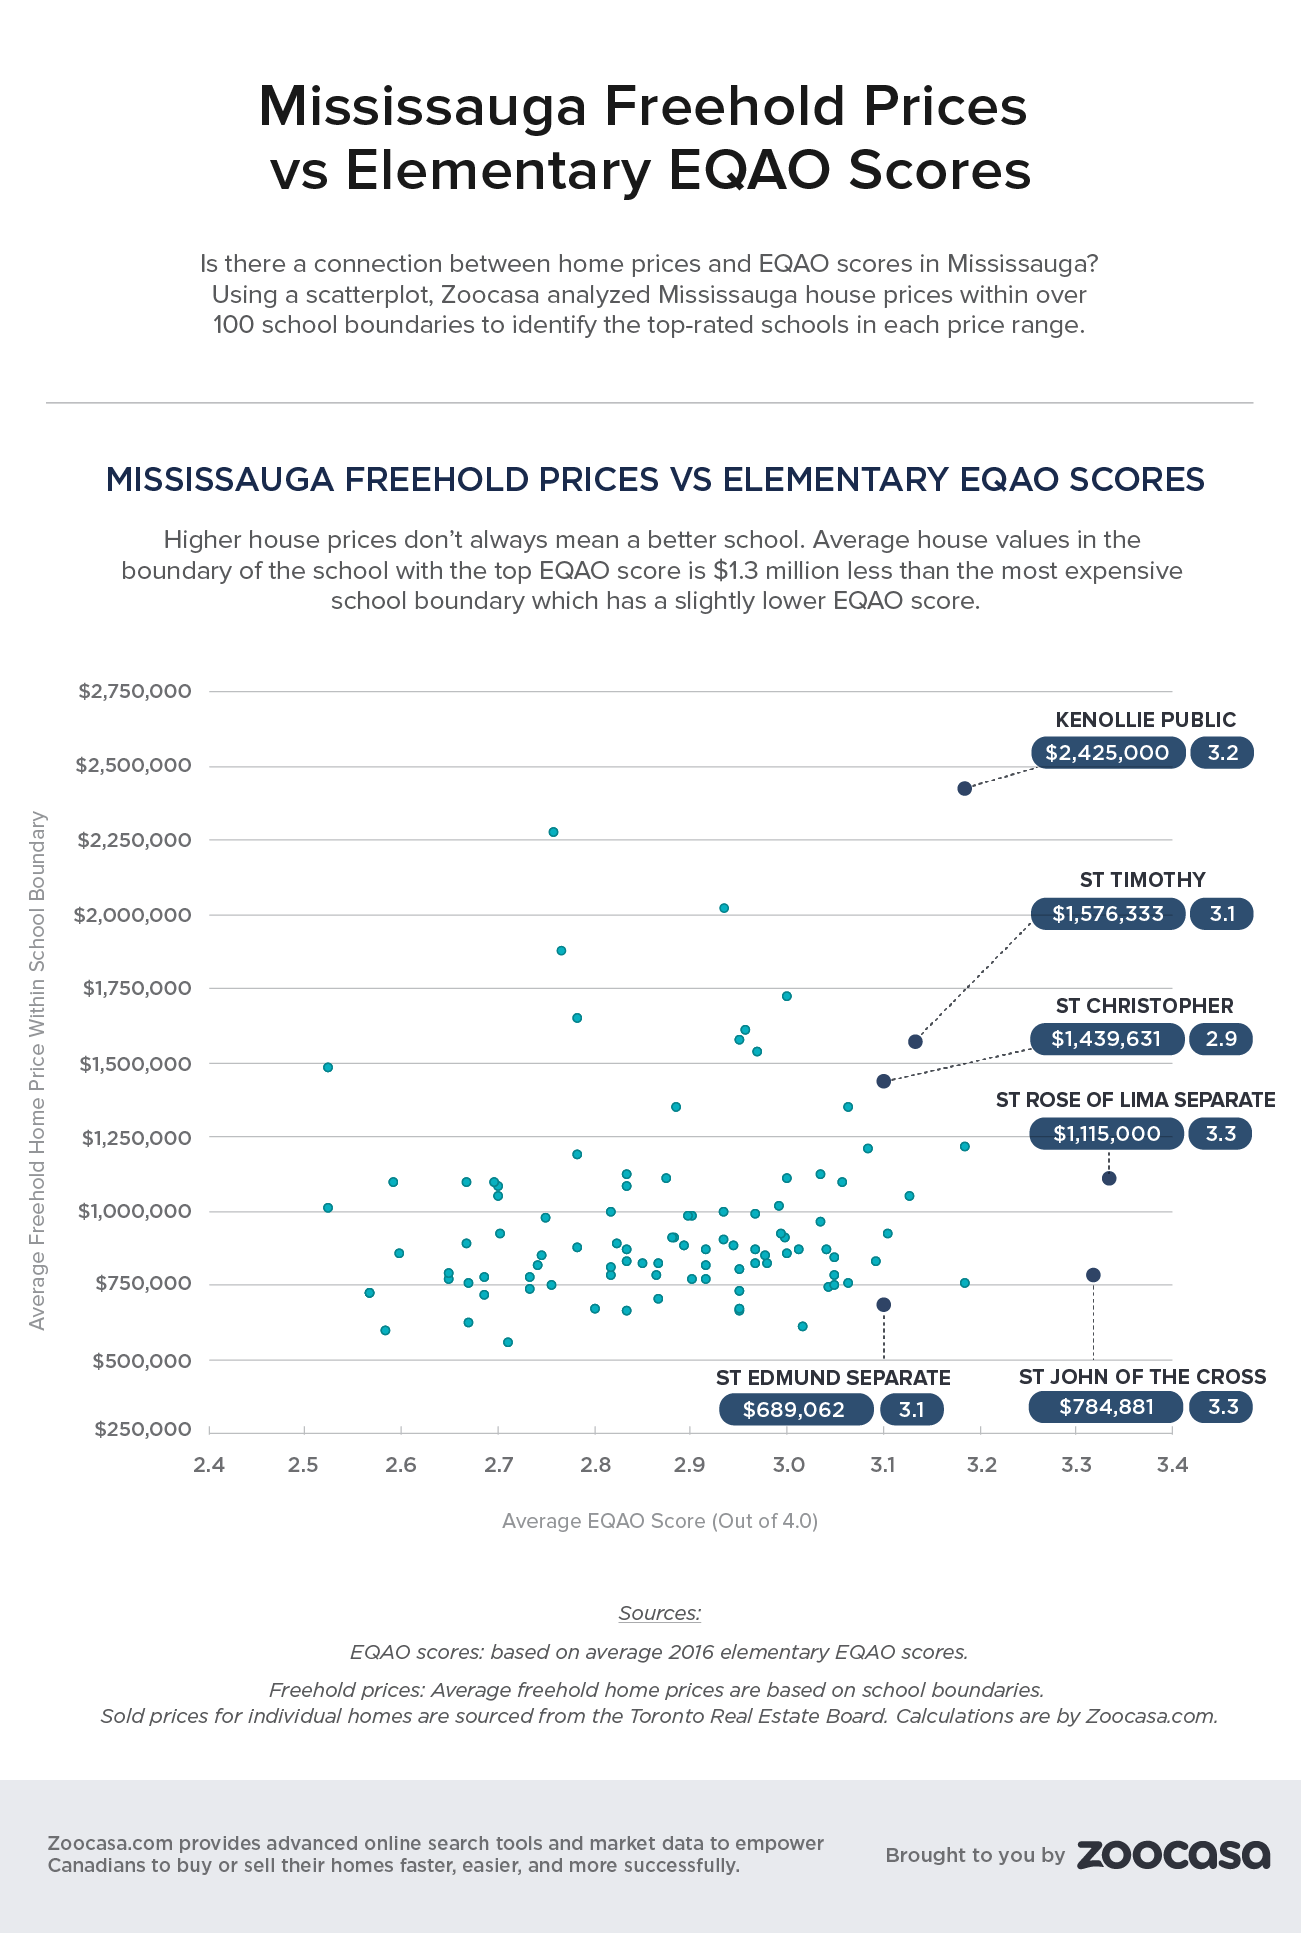
Mississauga schools among the best

The City of Mississauga is also a great example of a municipality where good schools and real estate affordability go hand in hand. Continue Reading…