Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Overhaul of mutual fund fees not as sweeping as some would like

Deferred Sales Charges (DSC) on mutual funds are going to be eliminated in Canada but recommendations released today by securities regulators did not go so far as to implement an outright ban of trailer commissions (aka trailer fees, also referred to as embedded compensation.)

The Canadian Securities Administrators (CSA) also released proposals regarding rules about what advice or products are in the “best interest” of financial consumers.


You can find a full summary in this article that appeared today in the Globe & Mail. (The full link may only be available to G&M subscribers, depending on how many free views readers have previously accessed). Rob Carrick also has a column on the topic titled It just became clear we’ll never see an investment industry where clients must come first. Well, we’ll see. Over at the Financial Post, Barbara Schecter reports OSC drops push for adviser standard.

Big win for industry

For more of an industry perspective, there is a full report here at Advisor.ca. And the industry’s newspaper, Investment Executive, headlined its coverage as “a big win for the industry.”

John De Goey

One of the sources cited in both G&M articles is John De Goey, an investment adviser and author, who also sent this email to the Hub expressing his disappointment in the decisions:

“This is shameful on the part of the CSA.  It has been almost 15 years since Julia Dublin’s Fair Dealing Model drew attention to the concern of bias caused by embedded commissions.”  He also offered these four observations:

  • The primary concern is advisor bias as caused by embedded compensation, and there’s nothing here to address that
  • Does not allow for “product meritocracy”
  • Does not address how the trailing commission on equities is double the trailing commission on income (which creates obvious, massive, self-evident advisor bias)
  • Does nothing to address the discrepancy between ETFs and mutual funds.  Advisor’s preferred business model should never drive product recommendations


Vanguard says industry will organically evolve away from embedded compensation
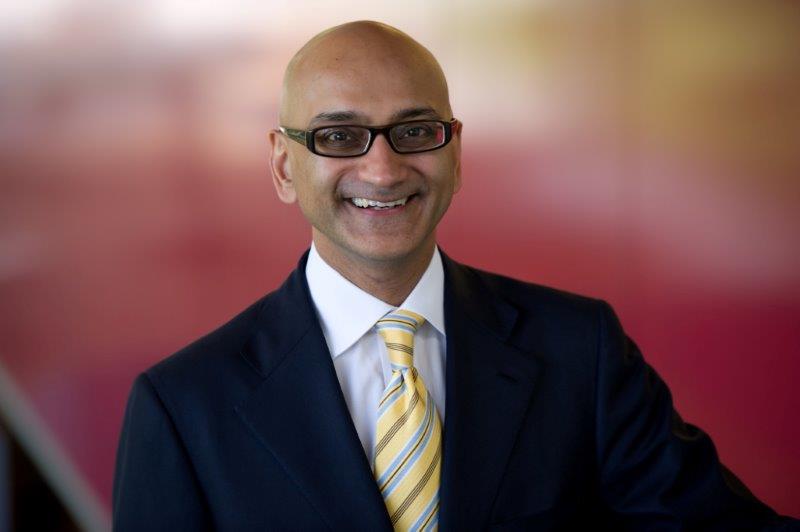
Vanguard Canada’s Atul Tiwari

However, Vanguard Investments Canada Inc. managing director Atul Tiwari said Vanguard is “encouraged by some of the proposals from the CSA. Although there will not be a ban on embedded commissions, we believe that the Canadian market, like other regions around the world, will organically evolve away from it. The CSA has made clear that suitability determinations will need to be in the best interests of clients. This will likely accelerate the move that we are already seeing in advisors going from commission-based to fee-based models. We support that trend as providing superior fee transparency and enhancing the use of low cost products to give clients better long term returns. Vanguard will continue to champion the interests of Canadian investors with more low-cost and high-quality product options.”

And finally, my take on this at the Motley Fool

(Added on Friday afternoon): You can find my own take on this development in my monthly blog at Motley Fool Canada. Click on the highlighted headline here: New mutual fund advice guidelines underwhelm advocates for Consumer-Investors.

 

Why starting your own business is better than getting a job

By Savannah Wardle

Special to the Financial Independence Hub

Instead of getting a job, make a job. You can take a large vacant place where a business should have been and fill it with everything you’ve ever dreamed of. If you’re on the verge of a major career change, you have the unique ability to customize that change to your needs. It might be time for you to branch out on your own and do things for yourself: you can wind up better off for having done it.

It’s easier than it used to be

The internet revolutionized the way that people run businesses. It used to be that people were confined to working for someone else because they didn’t have the resources they needed to become fully independent. Now, almost everything you can’t do yourself can easily be outsourced to software, apps, or freelancers who know how to get things done the right way. It doesn’t matter if you need to hire a Twitter expert, have a catering website built, or find specialty garage door software. The internet has it, and you can use it to build your own empire.

You’re free to explore Innovation and Creativity

Think about all the aspects of your old job that were holding you back. Did you have bold new ideas that you were dissuaded from pursuing because they didn’t adhere to the company’s “play it safe” motto? You don’t have to worry about that anymore. You’re the one calling the shots, and if you know you have the potential to shake up your industry, no one is stopping you. You can try and try and try, even if you fail, and you don’t need to worry about the powers that be restricting you from exploration.

You can live the way you want  

If you used to work long hours and weekends, you probably felt like you were missing out on life. If you run your own business, you can be open from 9 to 5 on weekdays. Close up shop for dinner and the weekends and live your life. A lot of people cite work/life balance as being one of the reasons they opt for a career change, and if you’re one of those people, you can easily find the exact balance you want by becoming an entrepreneur or an independent contractor.

You get to build your dream team Continue Reading…

How do Canadians feel about the new Real Estate regulations?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

The anniversary of the implementation of the Ontario Fair Housing Plan has come and gone, and the playing field is just starting to even in the province’s housing market. Designed to cool demand and price growth in the Greater Golden Horseshoe, the 16-part package of housing regulations has effectively done just that, with sales down double-digit percentages throughout the region, and prices softening for the most expensive housing types.

Housing analysts argue that this result is mainly due to psychological factors, rather than the new regulations – which include a foreign buyer’s tax, and overarching rent controls – themselves.

But what do Ontarians really think about the new regulations? To find out, Zoocasa conducted a survey of 1,400 respondents on their sentiments around the highlights of the plan, and whether they support the government’s intervention in the free housing market.

Following BC’s footsteps

If Ontario’s attempt to tax foreign purchasers of real estate seems familiar, that’s because it closely resembles what occurred in British Columbia; the province initially implemented a 15-per-cent levy on foreign buyers within the Metro Vancouver area in August 2016, before upping the tax to a full 20 per cent, and extending the affected geographical area, in February of this year.

While Ontario’s version, called the Non-Resident Speculation Tax (NRST) still taxes just 15 per cent of a home’s purchase price, it will apply to anyone buying a home within the GGH – including homes for sale in Hamilton, or condos for sale in Mississauga, who is not a Canadian citizen or permanent resident (those who obtain such status, or who are enrolled in a minimum two-year full-time post-secondary program within a year of their home purchase are eligible for a full rebate on the NRST).

At the time of its implementation, former Ontario premier Kathleen Wynne was adamant that the tax was not intended to discourage newcomers to Canada from settling in Ontario.

“The Non-Resident Speculation Tax has nothing to do with new Canadians or people who want to make Ontario their home,” she stated to a media scrum on April 20, 2017. “This is targeting people who are not looking to raise a family, who are just looking for quick profit or a place to park their money.”

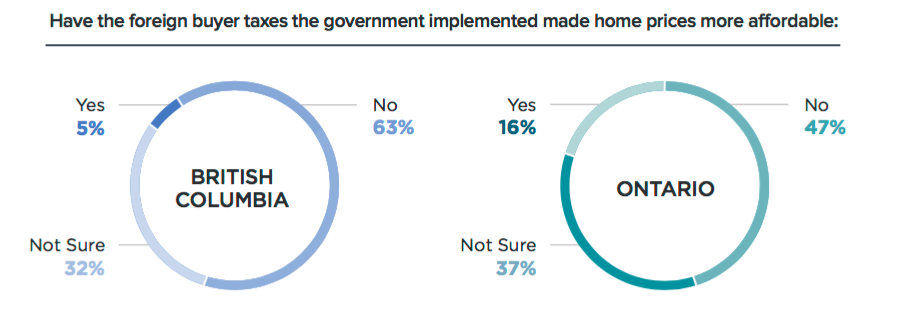
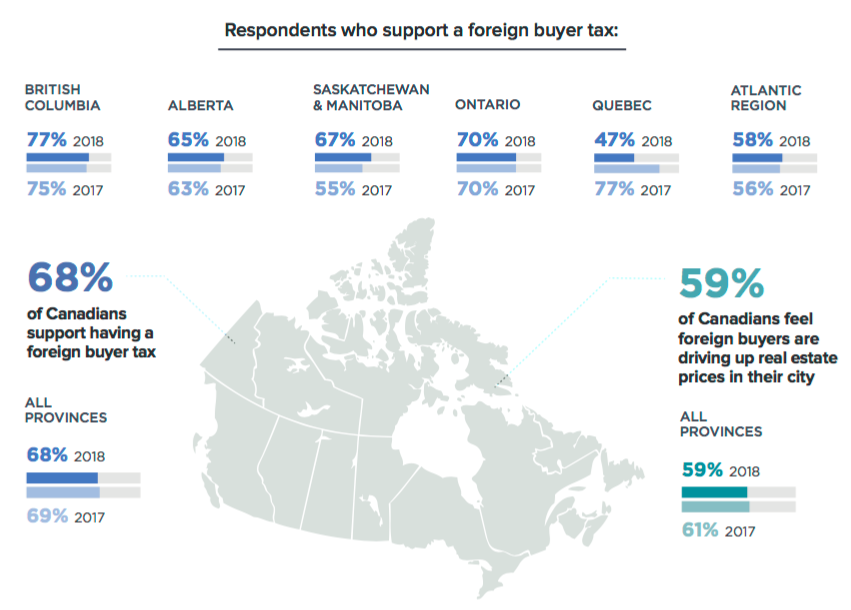
The measure appears to have resonated well with all Canadians; according to survey results, 69 per cent of respondents from all provinces indicated they support the tax, while 61 per cent felt foreign ownership directly impacts prices in the local housing market.

Perhaps not surprisingly, respondents from provinces with the most competitive real estate marketplaces were most likely to support the tax: 77 per cent of British Columbians and 70 per cent of Ontarians indicated they were pro-tax.

Support extends beyond affected Housing markets

However, even respondents from provinces where foreign investment and homeownership is not considered a stressor on the market, indicated support for the tax; 65 per cent of Albertans indicated support, even though only 40 per cent feel out-of-country buyers impact housing prices in their region. Continue Reading…

Retired Money: How to be financially, physically and emotionally fit for Retirement

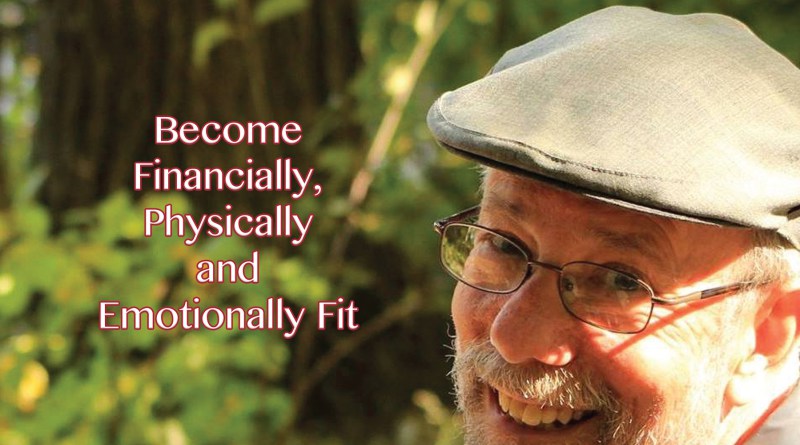
My latest MoneySense Retired Money column, which has just been published, looks at a self-published book by the semi-retired (at age 64) Howard Pell. His book is titled Retire Fit, Fit & Fit. Click on the highlighted headline to retrieve the full MoneySense column: Retirement fitness involves mind and body, as well as money.

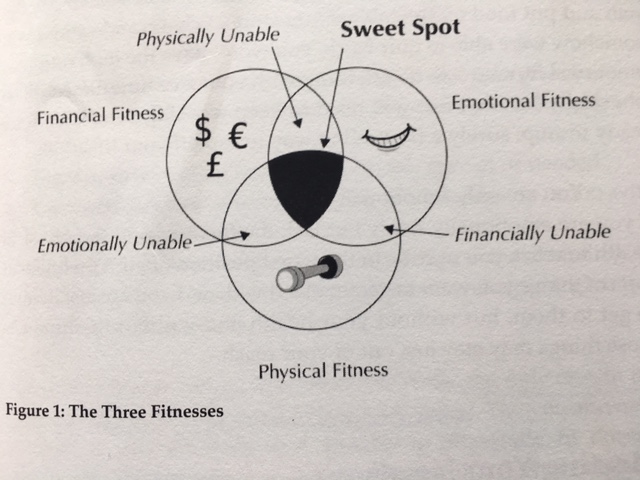
So what does the Fit, Fit & Fit mean? It’s in the headline of this blog as well as the adjacent photo taken from the book cover, which is the book’s subtitle. So it’s referring to being all three of financially fit, physically fit and emotionally fit for Retirement.

There are plenty of books about financial fitness so Pell pays only lip service to that aspect: what he brings to the table is insights on how to integrate finances with physical and emotional fitness. (To some extent, so does the book I co-authored with Mike Drak: Victory Lap Retirement)

Pell, who is based in Waterloo, Ont., does add a few newish terms to the semi-retirement lexicon.  He dubs the lifestyle “voluntary unemployment” but like many at this stage, finds the word “retired” inadequate. He tosses out several alternatives but the best one is his suggestion to simply adopt the Spanish word for “retired,” which is Jubilado (for males) or Jubilada (for females.”) He would use the term to signify anyone who is financially, physically and emotionally fit.

I can certainly relate to his observation of the semi-retired life that  “The big difference is that now all my deadlines and commitments are self-imposed.” Of course, as the old quip goes about driven self-employed business people: “My boss is a slavedriver.”

Pell also went personally through the “glide path” to semi-retirement described in other Retired Money columns and here at the Hub, via working a three-day week for his then employer during the last two years of his time there. This is a good way to test out your financial fitness while also clearing time for more physical fitness and — perhaps the toughest challenge — preparing for emotional fitness for retirement (I’m speaking for myself here.)

Finding the sweet spot

A Venn diagram on page 7 of Pell’s book (shown adjacent) illustrates that the sweet spot is the intersection where financial, emotional and physical fitness all converge.

If they don’t, and you became financially fit by selling out either your physical and/or your emotional health, the retirement your finances make possible may be a very limited and unsatisfying one.

It’s also possible to be only physically fit or only emotionally fit but lack the financial resources for retirement. The need to keep working to pay the bills will be frustrating, especially if all your peers have retired.

Continue Reading…

How in sync are global Central Banks?


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Without much fanfare, the U.S. Federal Reserve (Fed) provided its policy guidance late in May. Although no rate hike was implemented [it raised its overnight lending rate by 0.25% at 2 pm today, June 13, at 2 pm: Editor]  the money and bond markets fully expect the U.S. central bank to continue on its tightening path for the remainder of 2018, if not beyond. While the lion’s share of the focus has been Fed-centric on this front, it seems like a good exercise to check in on what the expectations are for the developed world’s other key monetary policy makers.

Heading into 2018, optimism for ongoing global growth seemed to be the norm. Indeed, along with the outlook for continued global growth, discussions were arising on whether central banks would soon turn their attention to any potential increase in inflation. While we still have almost seven months to go in this calendar year, recent data appears to be suggesting a plateauing of sorts on the economic front.

One economic indicator that is widely watched for help discerning economic trends on a global basis are the various Purchasing Managers’ Indexes (PMI) on a country or regional basis. While the levels being posted in the developed world still point toward further expansion, they don’t necessarily indicate a pick-up in growth prospects on the immediate horizon. In fact, the readings for April on an aggregate basis were relatively flat, and in some cases — such as the eurozone, the UK and Canada — have actually slipped a bit from their recent peaks.

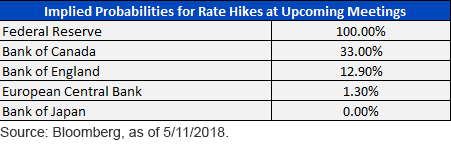
So, what should investors expect in near-term global central bank policy? As illustrated in the table above, expectations for the upcoming policy meetings certainly differ quite a bit. The overarching outlook is for the Fed to raise rates at its convocation on June 13, with the Fed Funds Futures implied probability being 100%, as of this writing. The remaining four developed world central banks — the European Central Bank (ECB), the Bank of England (BOE), the Bank of Canada (BOC) and the Bank of Japan (BOJ)  — all fall in the “no rate hike” camp. Continue Reading…