Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

What does it really take to move overseas?

Overseas life is adventuresome

By Akaisha Kaderli

Special to the Financial Independence Hub

In preparing for a retirement overseas, we would wager that most people occupy themselves with the practical concerns of residential visas, banking, owning property, finding a doctor they like, medical care that they can afford and dealing with any language barriers. These are pragmatic matters with realistic solutions, and we say that these areas are almost the easiest part of making this lifestyle change. While the above mentioned topics are important and must be solved, we want to share with you what it really takes to move overseas.

It may surprise you, but what we have seen take people down, destroying their retirement dreams and sometimes even their marriages, are the emotional and psychological challenges one faces in adjusting to their new lifestyle overseas.

How do you prepare for these obstacles ahead of time? We hope the following tips and insight will shed some light on the topic.

Just like home, only cheaper
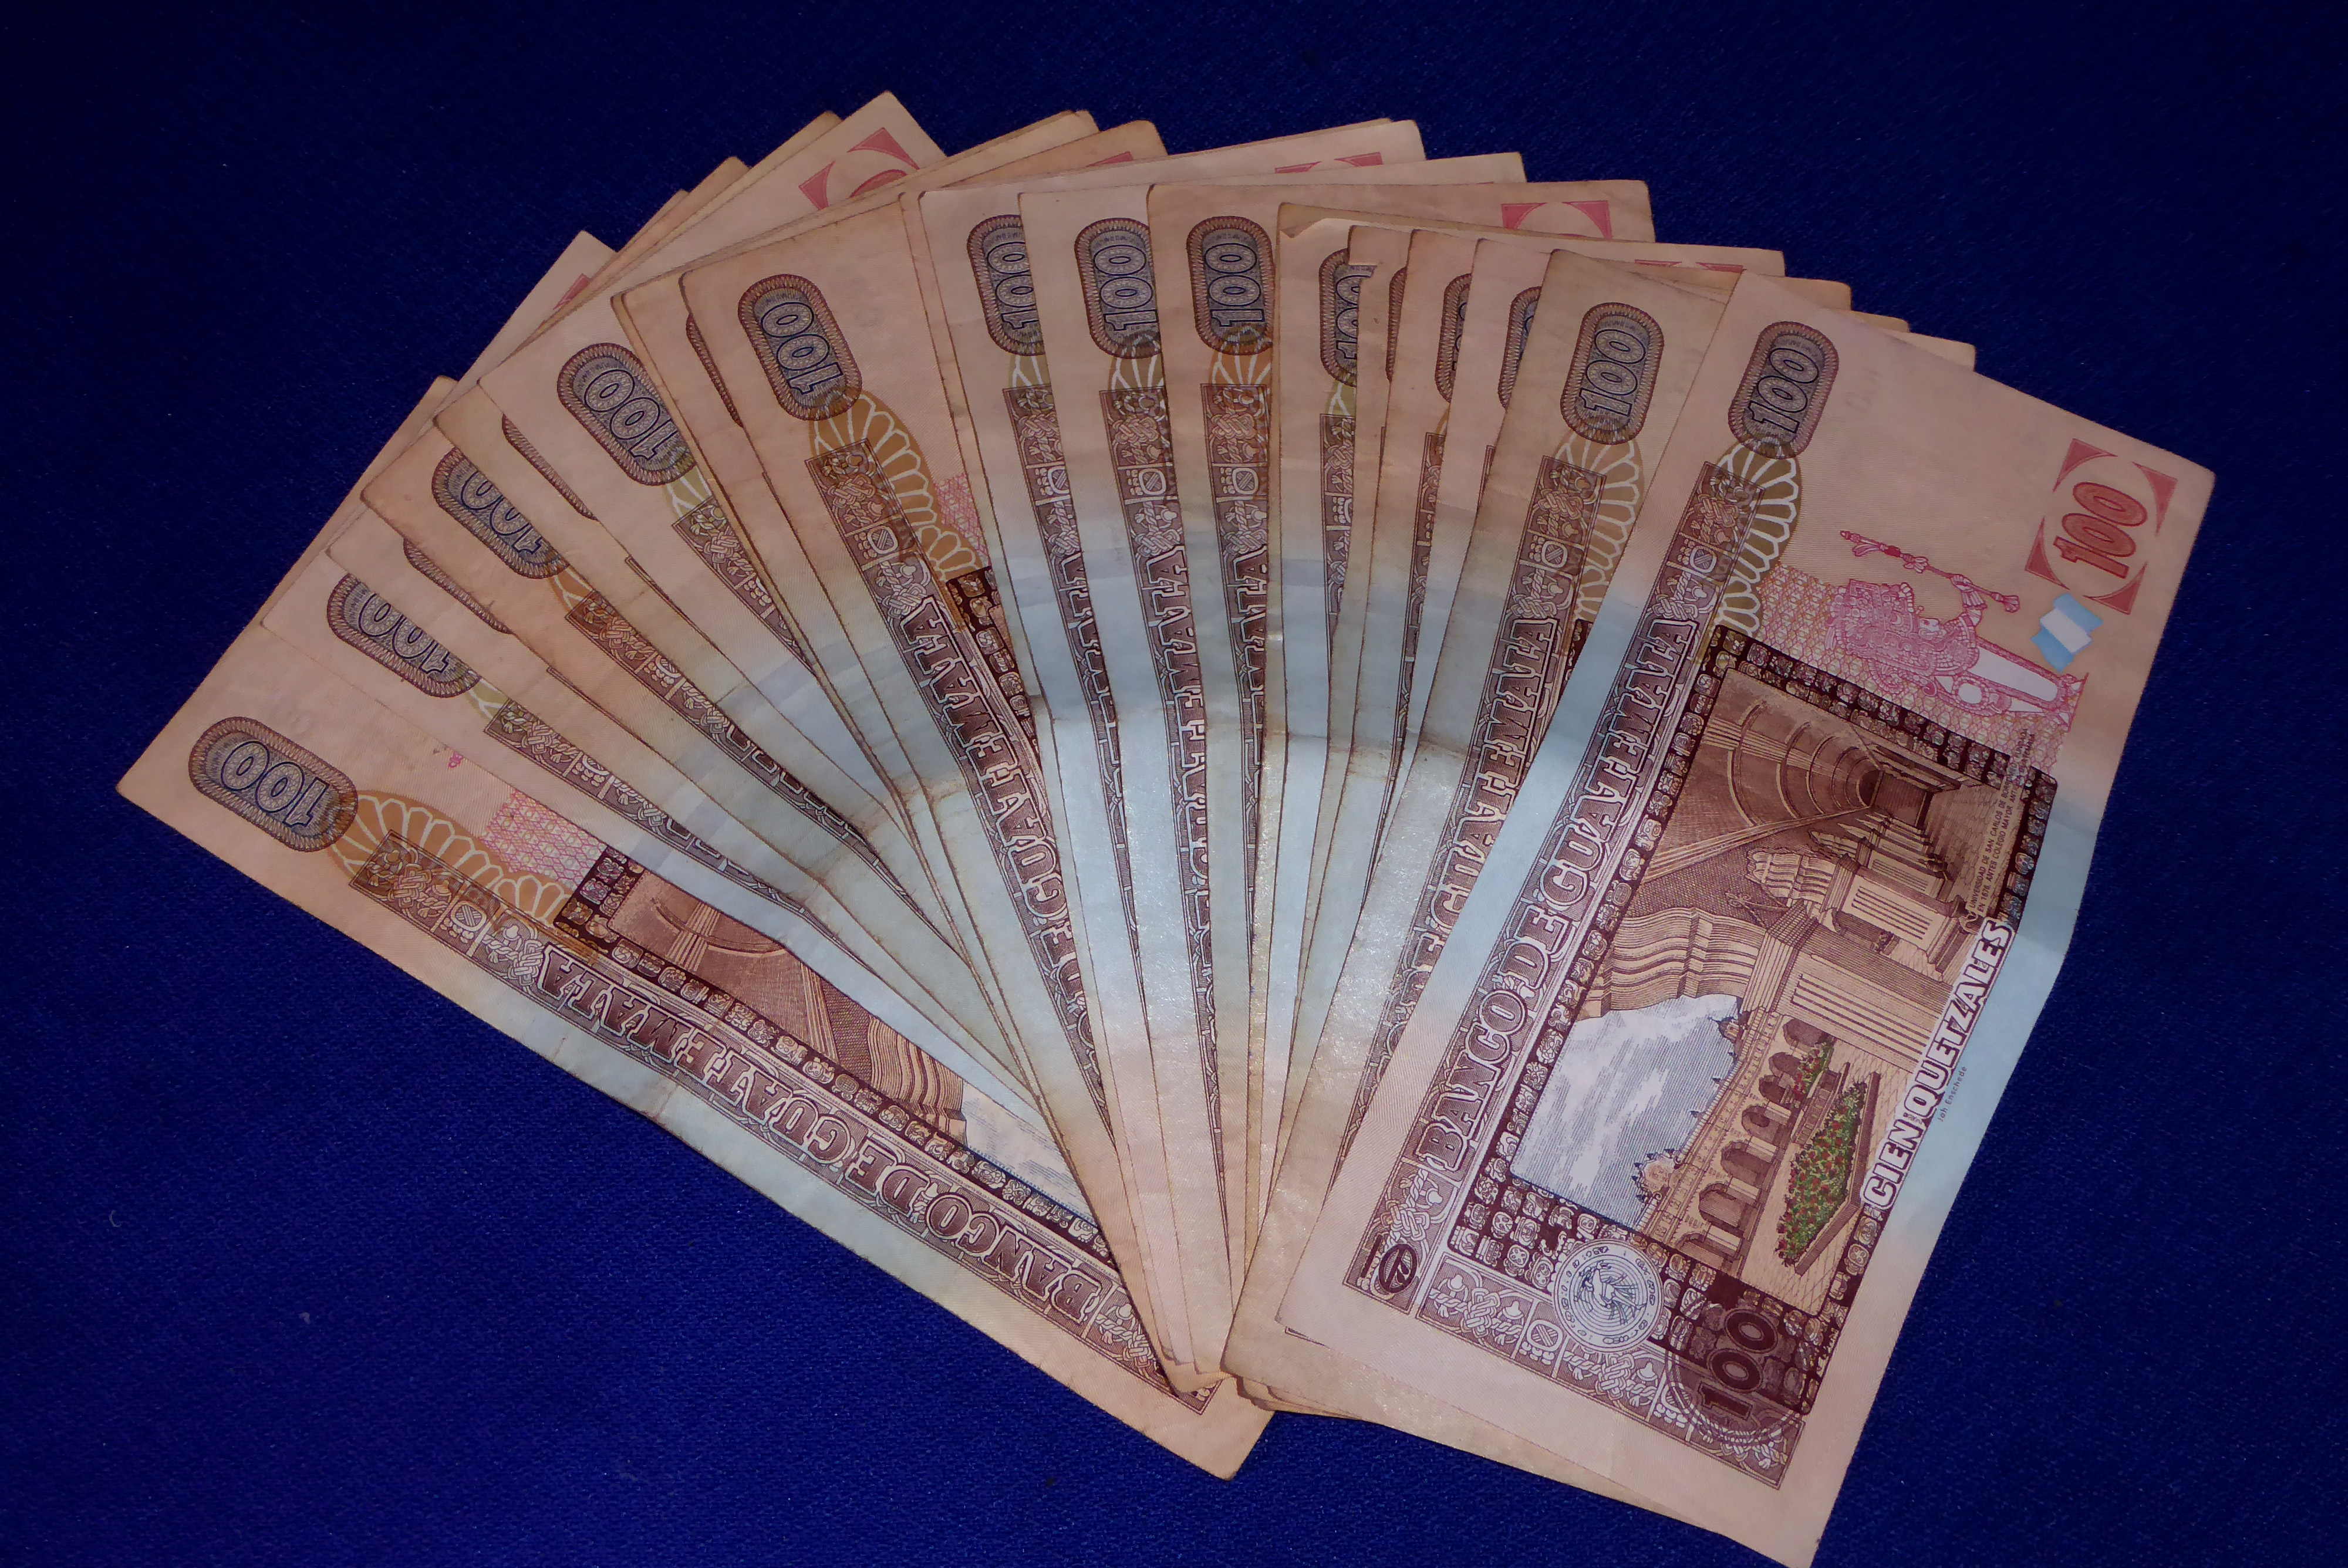
You could save a bundle moving overseas

Many people trip themselves up with their giddiness over the fantastic cost of living in their new location. They often come into a new country talking themselves into believing that living in their new destination is just like home, only cheaper. We want to tell you that no place overseas is just like home. Customs, foods, weather cycles, housing codes, the treatment of pets, the laws, the language, cobblestone streets and workmanship quality are all different.

We have seen folks love the quaintness of their new town but then fall apart because they can’t find parking near to markets where they shop. Their charming town might not have one-stop-shoping with a parking lot tying several stores together so they find that market day involves stopping in six locations, perhaps fighting traffic in between. Instead of taking their time to enjoy their enchanting town, they find this situation to be annoying and they carry the frustration with them all day.

 Culture and customs

Animals are treated as animals in developing nations and not as family members. Street dogs are common and if your heart is easily broken, then this might pose a problem for you. Continue Reading…
Accidental Death Insurance: What you must know before buying it

By Lorne Marr, CFP
Special to the Financial Independence Hub

Some insurance products are quite straight-forward (e.g. term life insurance), but others were created when insurance companies saw an opportunity in the market to increase their sales while reducing their own risk of needing to pay the claims. Accidental death insurance (often called accidental death and dismemberment) is one of these products.

Think of this product this way:

“If you look for a simple explanation, imagine all life insurance products to be cars. Your accidental death insurance is a car that you can drive only 30 minutes a day and only in one particular neighbourhood …”

Now, let’s understand this product better …

What is accidental death insurance?

Accidental death insurance is a life insurance policy (or an addition to an existing policy) that pays a claim only in particular cases: when the cause of death is an accident. In other cases, this insurance will pay nothing.

An important statistic to know is that only ~5 per cent of all deaths in Canada originate from accidents. That means that, in 95 per cent of cases, the policyholder will not be paid.

What is accidental death and dismemberment insurance?

Accidental death and dismemberment insurance is an insurance policy that pays a claim only if a death or a dismemberment (such as the loss of a particular body part, like a leg, hand, finger, etc.) occurred due to an accident. Typically, an accidental death and dismemberment insurance contract will define what amount will be paid in case of death and certain different types of dismemberment. Claim coverages associated with heavier dismemberments (e.g. a lost leg) are normally higher than claim coverages associated with smaller dismemberments (e.g. loss of a finger).

Is accidental death insurance worth it?

The quick answer is that, in most cases, it is not worth it. Continue Reading…

Benefits of hiring a “Discretionary” Portfolio Manager

Canadian investors have been following a variety of recent debates about the structure of the advisor/client relationship. I’m going to cut to the chase quickly.

If you seek core qualities and competencies from your investment professional, such as the following list, you need to conduct some research. Your mission is to find a way to hire a “discretionary” portfolio manager (DPM) for your ongoing wealth management needs.

Continue Reading…

When $70 Crude Oil doesn’t feel Like $70 Crude Oil

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

“Judging by the oil market in the pre-OPEC era, a ‘normal’ market price might now be in the $5-10 range  … Last week Algeria’s energy minister declared, with only slight exaggeration, that prices might conceivably tumble ‘to $2 or $3 a barrel.’”

—The Economist, March 4, 1999

That quote feels like it was from a million years ago. A decade later, straight-faced economists would be talking about US$200 or US$300 per barrel. Times change.

With oil two years along in a bull rally that has witnessed its price triple from  lows in the first quarter of 2016, it may be just a matter of time before the purported list of stock market obstacles starts to include retail gasoline pain. With West Texas Intermediate (WTI) crude oil changing hands at US$67.44 and Brent crude at US$73.26, it’s hard not to be scared off by our collective ups and downs at the gas station.1

After regular unleaded challenged US$4 a gallon — $3.695, to be precise2 — in the summer of 2014, many strategists began to fear the worst. Gasoline would once again deal the death blow to the American middle and lower classes, as it had a half-decade prior.

But 2014 marked the worst of it, at least for now. WTI crude oil collapsed from triple digits to less than $30 in early 2016. Retail gas followed along, to levels south of $1.80.

But it has quietly chipped back, closing the first quarter at $2.57, and $3 looms in the American psyche. Unlike in Canada, where expensive fossil fuel prices tend to benefit the federal budget, Alberta employment and so forth, Americans historically have had no similar solace outside of petroleum-rich Texas and Alaska, perhaps. It’s just a different economy. People remember the first time they saw a gas station post a price of $1, then $2, then $3. And at $4, that memory strikes the gut: the insolvency years.

Regular Canadians feel pain from expensive gasoline, for sure, but not quite like the pain that hits Americans.

Tie the threat of a national average of $3 per gallon south of the border, maybe during the Labor Day road trip, with the possibility that U.S. Fed Chairman Jay Powell may bring two or three more rate hikes of 25 basis points by this year’s close, and it is not much of a leap to be sympathetic to a thesis of a gasoline-induced blow to American consumer confidence. But be careful, because that thesis is flawed.

Whispers

The “whisper number” on Saudi aspirations for Brent crude is $80 to $100 per barrel. But Donald Trump was already tweeting angrily at $70 per barrel, so it is reasonable to assume that another $20 to $30 would unwind much progress on recently fruitful U.S.-Saudi relations. But suppose ROPEC — Russia plus OPEC — marks oil up to $100 anyway. Gasoline could be closer to $4 than $3 in that circumstance. Does that break the American consumer? A half-generation or a generation ago, yes — certainly. But psychological anchoring on round numbers like $100 or $3.00 deceives. Consider our analysis below.

Our 2018 Reality

Figure 1 places unleaded gasoline costs in context. The U.S. population of some 322 million people consists of 126 million households driving more than 3 trillion miles per year. But because millennials do not drive as much as their predecessors, the number of auto miles driven per household has fallen to less than 25,000 from a peak of 26,413 in 2004.

Additionally, today’s cars are essentially computers on wheels, and fuel efficiency is notably higher than it was in prior years.

Twenty years ago, the American new car fleet got 23.4 miles to the gallon.3 By 2008, it was virtually unchanged, at 24.3. But the U.S. got burned on triple-digit oil, making it somewhat politically palpable when the Obama administration pushed forward with mandated 54.5 mpg fuel economy targets for model year 2025. In pursuit of such efficiency, the new car fleet’s efficiency rose to 30.0 mpg for the 2017 crop. Continue Reading…

Vanguard Canada unveils low-cost actively managed mutual funds

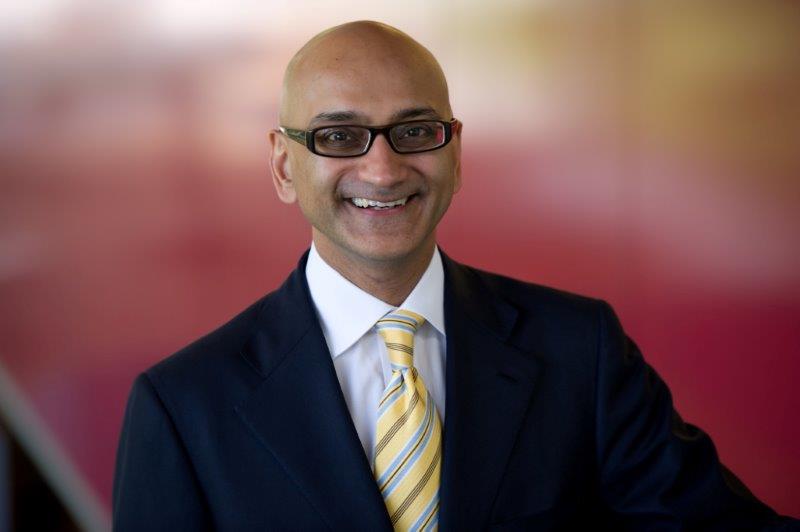
Vanguard Canada’s Atul Tiwari

On the heels of its three asset allocation ETFs that shook up Canada’s investment industry in February, Vanguard Investments Canada Inc. today announced it will be providing four new low-cost actively managed mutual funds to the Canadian market.

The four new mutual funds are its first actively managed products for the domestic market: until now, it has been providing 36 exchange-traded funds (ETFs), with more than C$16 billion in assets. Vanguard says Canadians hold more than C $28 billion in Vanguard investments if you include both its Canadian products and its funds trading on US stock exchanges.

All four of the new active mutual funds are globally diversified: Vanguard says its management fees are about half that of the mutual fund industry average in Canada. (According to the Investment Funds Institute of Canada here, the average total cost of ownership of mutual funds for clients using advice-based distribution channels in Canada at the end of 2016 was 1.96% when taxes are excluded.)

IFIC has said these costs continue to fall and there’s little doubt Vanguard’s entry will accelerate the trend, and not a moment too soon, given last Thursday’s disappointing proposals from the Canadian Securities Administrators. (See the Hub’s roundup here or my Motley Fool Canada blog here).

In a press release distributed at 8 am Monday, Vanguard said the four new funds “feature global investment strategies from some of Vanguard’s longest-tenured sub-advisors” and complement its broad-based lineup of ETFs.

Vanguard Canada managing director Atul Tiwari (pictured) said “Vanguard has a deep 40-year history of active management expertise and we are excited to extend that to mutual fund investors in Canada, at a low cost … These mutual funds reflect our philosophy as an organization with a disciplined long-term approach and world-class investment managers that have worked with Vanguard for decades.”

Despite the fact The Vanguard Group Inc. pioneered index funds and low-cost passively managed investing (with more than US$5 trillion under management), it is also one of the world’s largest active managers, with US$1.2 trillion in global actively managed assets. The key contributing factors to successful active management are low costs, talent and patience, said Tim Huver, Vanguard Canada’s head of product.

Pricing varies with investment performance

Vanguard says it will use a unique pricing structure in the Canadian marketplace that aligns the interests of the sub-advisors with the funds’ investors. The maximum management fee for each mutual fund will be 0.50% and the management fee will vary up or down, up to that maximum amount, based on the investment performance of each fund.


Mutual Fund Maximum Management Fee First Year Management Fee
Vanguard Global Balanced Fund


0.50% 0.38%
Vanguard Global Dividend Fund


0.50% 0.34%
Vanguard Windsor U.S. Value Fund 0.50% 0.35%
Vanguard International Growth Fund 0.50% 0.40%


The first year management fee shown above is effective from June 25, 2018 to June 30, 2019. The funds will be available to financial advisors through Series F units and institutional investors through Series I units.

Canadian investors currently hold $1.5 trillion in mutual funds, according to Tiwari. “Vanguard has a long track record of lowering investment costs in the areas in which we operate, so we see providing greater choice and lower costs to a broader group of investors as very positive.”

More on the four actively managed global mutual funds Continue Reading…