Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Ontario Retirement Pension Plan to roll out from 2017 to 2020

Minister Robb with Ontario Premier Kathleen Wynne, Northern Development and Mines Minister Michael Gravelle, HOM Tony Negus and Consul General/Senior Trade and Investment Commissioner Portia Maier.
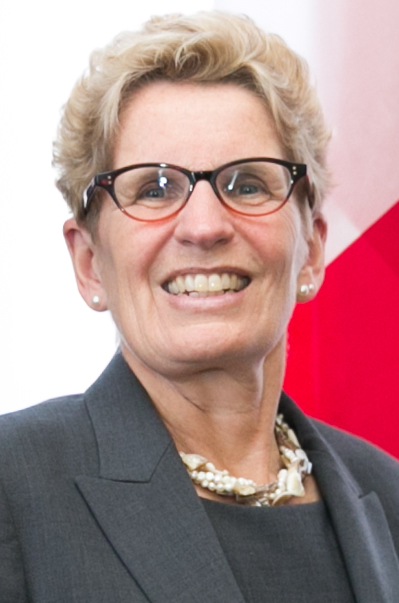
Ontario premier Kathleen Wynne (Wikipedia)

The National Post today reports the Ontario Government has revealed more detail today about its oft-criticized Ontario Retirement Pension Plan or ORPP. As it reported in a later update, staff at the province’s bigger employers will have to start paying into the plan by 2017, with a full rollout by 2020.

Employers will be exempt only if they already offer a mandatory Registered Pension Plan that Ontario deems comparable to the ORPP.

In 2022, Ontario residents who are 65 or older can start drawing benefits from the ORPP. Full-time or part-time workers  can  start contributing at 18 and continue until they turn 70.

While Premier Wynne has not released cost estimates of the program, the Post reported the plan will collect 1.9% of a workers’ income up to $90,000 from both employers and employees to a total of 3.8%, or a combined total of $3,420 a year

Meanwhile, proponents and critics of the plan got a little more ammunition from two different retirement reports produced by the Fraser Institute and the Mowat Centre.

Released Tuesday, the Fraser Institute report is titled Lessons for Ontario and Canada from Forced Retirement Savings Mandates in Australia. It suggests that if Canada really needs more “forced” retirement savings, Ontario should look for global examples that could be alternatives to its current plans for the ORPP. For example, it should look at Australia’s “superannuation” program, a contribution-based scheme to which both employers and employees must contribute. Australia’s system of “individual accounts” provide more flexibility and choice than, for example, the Canada Pension Plan (CPP.)

Like the CPP, the ORPP is a “collective” pension plan that pay out defined benefits over a lifetime. The paper by the Mowat Centre (titled Lower Risk, Higher Reward: Renewing Canada’s Retirement Income System) says the Australian plan has had “mixed” success because as a Defined Contribution plan it doesn’t guarantee a set income for life, as does the CPP and DB pensions in general.

Middle-to-upper income earners may need more help

Continue Reading…

“Stop Doing” #2: Stop Reacting to Market Noise

SL Picture - Full Colour
Steve Lowrie

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

In recently revisiting Jim Collins’ classic, bestselling business book “Good to Great,” I was reminded of this timeless tip:

Successful business owners make as much use of “stop doing” lists as they do of “to do” lists.

“Most of us lead busy but undisciplined lives,” says Collins. “We have ever-expanding ‘to do’ lists, trying to build momentum by doing, doing, doing – and doing more. And it rarely works.”  In his related piece, “Pulling the Plug,” He adds: “One key decision about what to stop doing might have as much impact as five new initiatives.”

Stop Reacting to Market Noise

Having a “stop doing” list seems like a fantastic idea – in business, in life and especially in your financial management. So often, I see investors who would probably be doing fine if they would just form a plan that reflects their personal goals, build a low-cost, globally diversified portfolio that complements those plans … then STOP reacting to near-term market noise that distracts them from their focus.

And Stop Reacting to Others Who React to Market Noise

Continue Reading…

Investment Fees Are Costing You Way More Than You Think … Here’s Why

vitatv_big_left-150x150
Vita Nelson

 By Vita Nelson, Editor and Publisher of Moneypaper’s Guide to Direct Investment Plans

Special to the Financial Independence Hub

You may not give much thought to the investment fees you pay. That’s because they seem so small. Right?

According to an October, 2014 survey by investment management firm Rebalance IRA, many Americans incorrectly believe they pay no fees in their retirement accounts. Among baby boomers between ages 50 and 68, all with full-time jobs, “forty-six per cent believed they paid nothing, and 19 per cent were under the impression that their fees totaled less than 0.5 per cent.” (In fact, research reveals that actual expenses average 1.5 per cent of their assets per year every year.)

Chances are that fees are costing you much more than you realize! Why?

Because the fee itself isn’t the real culprit. The real killer is the opportunity cost of not investing the money you’re spending on fees. That’s why John Bogle, founder of Vanguard, calls investment fees the “tyranny of compounding costs” in a recent Forbes interview.

The real cost of investment fees is the value of the shares you never bought, and how much those shares would have increased your wealth over the long term. That is, you’ve lost the compounding effect of owning those shares: the dividends that would have been paid to you on the shares and the compounding effect on those dividends. Continue Reading…

Motley Fool co-founder launches new Rule Breaker podcast

Motley-Fool-podcast
David Gardner’s new podcast

As was announced here recently, Motley Fool co-founder David Gardner has launched a new weekly financial podcast called Rule Breaker Investing.

I’ve long been a fan of Chris Hill’s weekly Motley Fool Money podcast, which generally runs close to 40 minutes and makes a nice weekend catchup on the financial week just past. He also spearheads a shorter podcast called Market Foolery, which runs Monday to Thursday. (Full disclosure, I once appeared on that podcast and also write for Motley Fool Canada).

Identifying the “lead” dogs

Continue Reading…

Building Your Financial “Stop Doing” List. Part 1: Stop feeding on Junk Media

SL Picture - Full Colour
Steve Lowrie

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

This month’s financial “STOP Doing” advice is inspired by the events in Europe, with Greece at Ground Zero. I wish I could tell you how it’s all going to play out or, better yet, promise you a happy ending, sooner than later.

Unfortunately, I can’t do that. Time alone will tell. The understandable craving to maintain control over your personal and financial well-being may leave you scanning the popular media’s headlines, searching for tidbits on how to protect yourself from the unfolding uncertainty. That’s why this is an excellent time to repeat a theme I’ve covered before: STOP feeding on junk media.

The Media Can’t Protect You from Volatile Markets

As I described in an April 2014 post, “Here’s why you should ignore the [popular] financial media … While I could recommend many things, I think the most important point for everyone to remember is that it is a myth that today’s headline news has a direct effect on the financial markets.”

This point can be hard to wrap your head around. It seems counterintuitive, but here’s the scoop: Any good or bad news reported by the media may feed your curiosity about what’s going on in the world, but it’s of no use with respect to investing.

Continue Reading…