Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Why the 4% Rule doesn’t work for FIRE/Early Retirement


By Mark and Joe

Special to the Financial Independence Hub

The 4% rule is a common rule of thumb in many retirement planning circles, including the Financial Independence, Retire Early (FIRE) community in particular.

What does the 4% rule actually mean?

Should the 4% rule be used for any FIRE-seeker?

Does the 4% rule really matter to retirement planning at all?

Read on to find out our take, including what rules of thumb (if any) we’re using at Cashflows & Portfolios for our early retirement dreams.

The 4% rule is really a starting point for a safe withdrawal rate

Unlike 2 + 2 = 4, the 4% rule is not really a universal truth for any retirement plan at all.

It is, however, in our opinion, a great starting point to understand the impacts of asset decumulation, related to inflation, over time.

As you’ll read more about in the sections below, the 4% rule is fraught with many problems. None more so than for an early retiree or FIRE-seeker. In some cases, for the FIRE community, we believe the 4% rule should no longer be used at all.

Are any financial rules really rules?

Backing up, here is the source for the 4% rule.

The article from 1994!

4% rule

Despite the geeky photo, by all accounts, Bill Bengen was one heckuva guy and a smart guy as well!

Potentially no other retirement planning rule of thumb has received more attention over the last 25-30 years than Bengen’s publication about the 4% rule. This publication in 1994 has triggered a new generation of devotees and arm-chair financial planners that are using this quick-math as a way to cement some retirement dreams. We believe that is a mistake for a few reasons.

First, let’s unpack what the 4% rule really means.

What does the 4% rule actually mean?

From the study:

“In Figures 1 (a)-l(d), a series of graphs illustrates the historical performance of portfolios consisting of 50-percent intermediate-term Treasury notes and 50-percent common stocks (an arbitrary asset allocation chosen for purposes of illustration). I have quantified portfolio performance in terms of “portfolio longevity”: how long the portfolio will last before all its investments have been exhausted by
withdrawals. This is an intuitive approach that is easy to explain to my clients, whose primary goal is making it through retirement without exhausting their funds, and whose secondary goal is accumulating wealth for their heirs.”

Unpacking this further, for those that do not want to read the entire study, here is something more succinct from Bengen:

Assuming a minimum requirement of 30 years of portfolio longevity, a first-year withdrawal of 4 percent, followed by inflation-adjusted withdrawals in subsequent years, should be safe.


“Should be safe”.

Again, the theory is one thing. Reality is something different and the financial future is always subject to change. Furthermore, if you’re blindly following this formula without considering whether it’s right for your situation, let alone putting in some guardrail approach to monitor your portfolio value at various checkpoints, you could end up either running out of money prematurely or being left with a huge financial surplus that you could have spent during your retirement. We’ll prove that point in a bit from another leading author.

Should the 4% rule be used for any FIRE-seeker?

Probably not. For many reasons.

Recently, Vanguard published an outstanding article about the need to revise any thinking about the 4% rule for the FIRE movement – a driver for this post.

Although the 4% rule remains a decent rule of thumb we believe most FIRE-seekers should heed the cautions in the Vanguard post. Here are some of our thoughts based on the article’s contents.

  • Caution #1 – FIRE-seekers should not rely on past performance for future returns

We agree. In looking at this Vanguard set of assumptions below, and based on our own personal investing experiences, we believe historical returns should not be used to guarantee any future results.
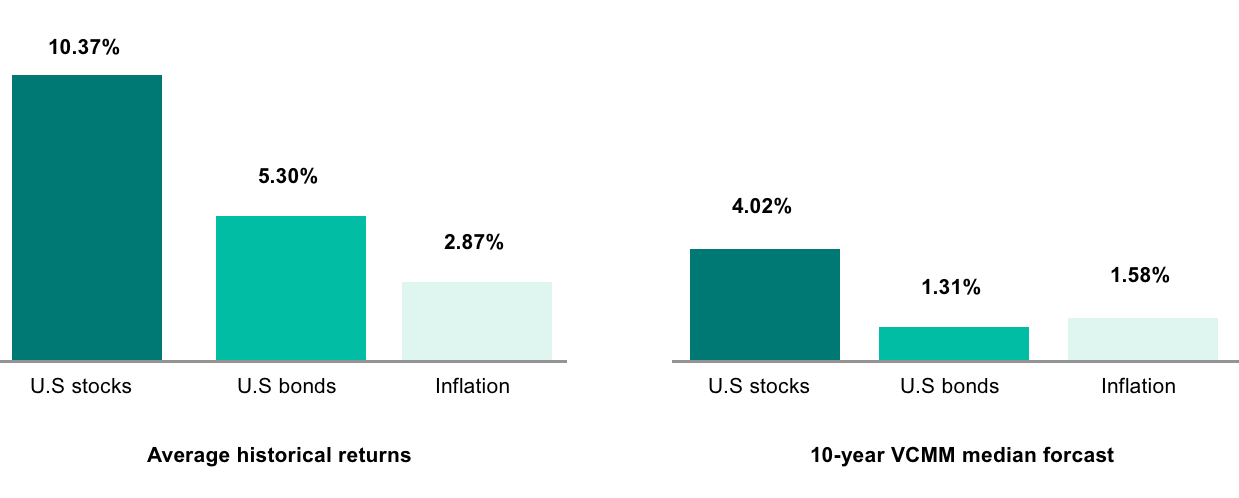
 

Source: Vanguard article – Fueling the FIRE movement

While the FP Canada Standards Council doesn’t have a multi-year (10-year) return model in mind, they did highlight in their latest projection assumption guidelines that going forward, investor returns may not be as juicy as in years past.
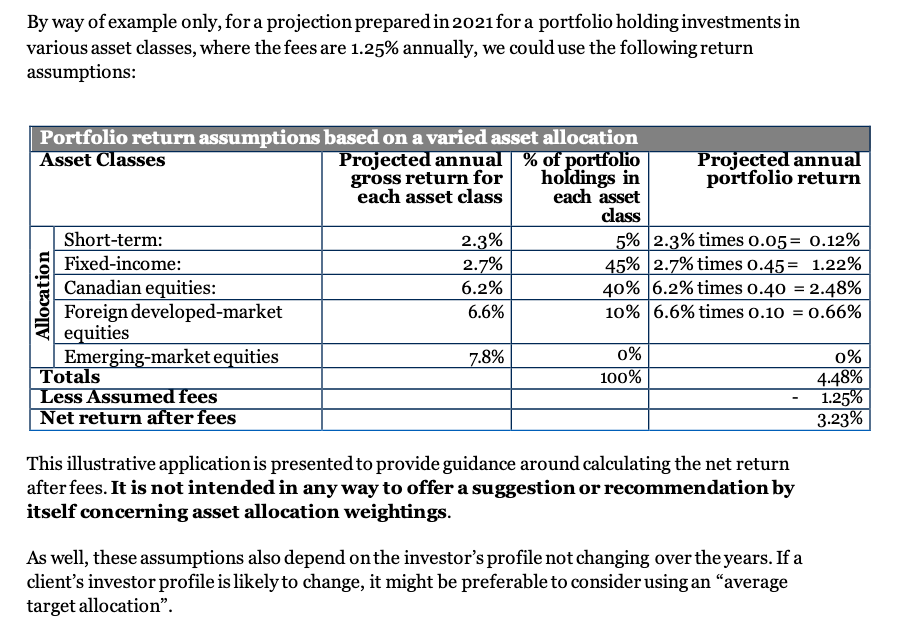
 

Source: FP Canada Standards Council.

This means for any historical studies, while interesting, may not be a great predictor of any future outcomes.

  • Caution #2 – The FIRE-seeking time horizon is longer

Bengen noted in his 1994 study:

“Therefore, I counsel my clients to withdraw at no more than a four-percent rate during the early years of retirement, especially if they retire early (age 60 or younger). Assuming they have normal life expectancies, they should live at least 25-30 years. If they wish to leave some wealth to their heirs, their expected “portfolio lives” should be some longer than that. “

Bengen goes on to say:

“If the client expects to live another 30 years, I point out that the chart shows 31 scenario years when he would outlive his assets, and only 20 which would have been adequate for his purposes (as we shall see later, a different asset allocation would improve this, but it would still be uncomfortable, in my opinion).
This means he has less than a 40-percent chance to successfully negotiate retirement–not very good odds.”

To paraphrase, Bengen’s study was relevant to 30 years in retirement. Not 35 years. Not 40 years and certainly not 50 years like some FIRE-seekers may need if they plan to retire at age 40 and live to age 90 (or beyond).

This is simply a huge reminder that your time horizon is a critical factor when it comes to retirement planning.

  • Caution #3 – FIRE-seekers may need to live with more stocks

Bengen’s 1994 study was based on the following:

“Note that my conclusions above were based on the assumption that the client continually rebalanced a portfolio of 50-percent common stocks and 50-percent intermediate-term Treasuries.” Continue Reading…
Reframing the RRSP advantage

I’ve read a lot of bad takes on RRSP contributions and tax rates over the years. One that stands out is the argument that you should avoid RRSP contributions entirely, and focus instead on investing in your TFSA and (gasp) your non-registered account. This idea tends to come from wealthy retired folks who are upset that their minimum mandatory RRIF withdrawals lead to higher taxes and potential OAS clawbacks. They also seem to forget about the tax deduction generated from their RRSP contributions and the tax-sheltered growth they enjoyed for many years leading up to retirement.

I’m hoping to dispel the notion of an RRSP disadvantage by reframing the way we think about RRSP contributions, RRIF withdrawals, and tax rates. Here’s what I’m thinking:

Most reasonable RRSP versus TFSA comparisons say that it’s best for high income earners to prioritize their RRSP contributions first, while lower income earners should prioritize their TFSA contributions first.

The advantage goes to the RRSP when you can contribute at a higher marginal tax rate and then withdraw at a lower marginal tax rate, while the advantage goes to the TFSA when you contribute at a lower rate and withdraw (tax free) at a higher rate.

If your tax rate in your contribution years is the same as in your withdrawal years then there’s no advantage to prioritizing either account. They’re mirror images of each other.

Related: The next tax bracket myth

This comparison focuses on marginal tax rates. But is this the correct way to frame the discussion?

Marginal Tax Rate vs. Average Tax Rate

Isn’t it fair to say that an RRSP contribution always gives the contributor a tax deduction based on their top marginal tax rate (assuming the deduction is claimed that year)?

But when you look at retirement withdrawals, shouldn’t we focus on the average tax rate and not the marginal tax rate?

An example is Mr. Jones, an Alberta resident with a salary of $97,000 – giving him a marginal tax rate of 30.50% and an average tax rate of 23.59%

Alberta MTR $97k

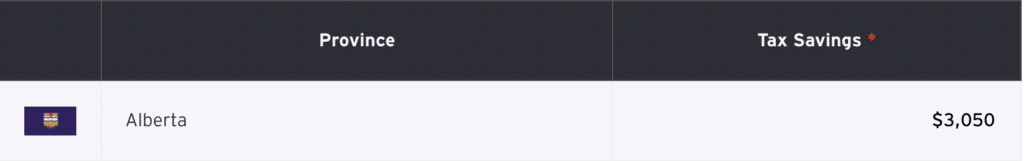
If Mr. Jones contributes $10,000 to his RRSP he will reduce his taxable income to $87,000 and get tax relief of $3,050 ($10,000 x 30.5%).

RRSP deduction

Fast forward to retirement, where Mr. Jones has taxable income of $60,000 from various income sources, including a defined benefit pension, CPP, OAS, and his $10,000 minimum mandatory RRIF withdrawal.

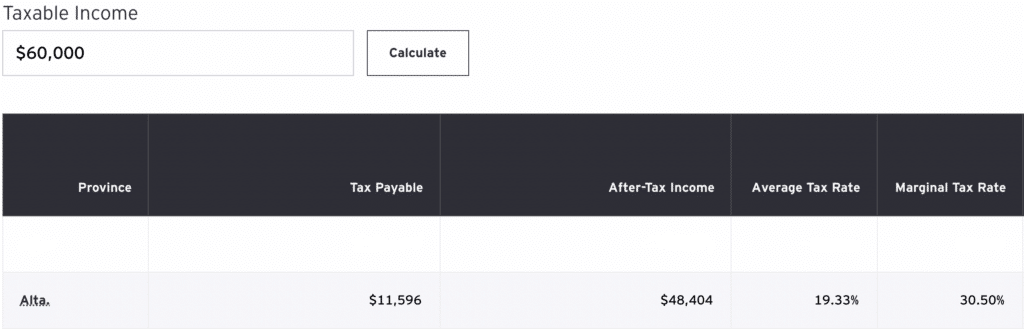
The range of income in each tax bracket can be quite broad. With $60,000 in taxable income, Mr. Jones is still at a 30.5% marginal tax rate, but his average tax rate is just 19.33%. That’s right, he pays just $11,596 in taxes for the year.

Alberta MTR $60k

Conventional thinking about RRSPs and marginal tax rates would tell us that Mr. Jones should be indifferent about contributing to an RRSP in his working years because he’ll end up in the same marginal tax bracket in retirement.

But when we consider all of our retirement income sources, why do we treat the RRSP/RRIF withdrawals as the last dollars of income taken (at the top marginal rate) instead of, say, income from CPP or OAS or from a defined benefit pension? Why would Mr. Jones’ $10,000 RRIF withdrawal be taxed at 30.5% when it’s his average tax rate that matters? Continue Reading…

Letting go can lead us to Opportunity and Freedom

Photo by Sebastian Staines on Unsplash

By Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

Often, we have the idea that letting go means the loss of something valued. This implies that there might be grief and pain involved.

Out of fear we envision ourselves in some barren emotional wilderness, with nothing around that is familiar so there has to be that dreaded chaos, right?

 And who wants that?

But what if letting go leads us to brilliance? To our own personal freedom of expression? What if this is Life’s way of steering our personal growth in a manner where we display our best talents?

Letting go could mean opening up.

Examples

 Art/music

Have you ever heard a musician or singer who is technically perfect: but there seems to be no soul? No felt connection to the audience?

Yes, all the notes are there and in the right place, but … something is missing.

There is no grab at my heart. I could just as well be chopping carrots in the kitchen for soup. It’s just routine, and maybe I should have bought a bag of frozen carrots instead.I always know when I hear someone “Who’s got it.” My eyes well up and I can’t reign it in. That’s my validation signature.

Photo by Daniel Angele on Unsplash

Chills on my arms, my eyes are glued to the performer and I am transported. The artist has whisked me away, and I want to go.

It could be a jazz singer who scats, a sax player having a riff or Billy Joel hitting the high notes for Christy Lee.

They let go and have entered “The Zone.”

Sports

Ok, here’s another example.

We have all seen outfielders throw their bodies at a fly ball just to catch that thing. Or a basketball player speed down a court and ram a ball into a basket. Ballerinas, ice skaters, skateboarders spin incomprehensibly – how can a physical body DO that?

Maybe as a skier you have caught air and you know that sensation of flight for yourself.

That’s my point.

To let go, is to leave the ground and enter genius territory.

Fear and contraction

When we begin to learn something new – cooking, Latin dancing, painting on canvas, surfing – there are basics. We learn the techniques, the rules, the boundaries. And then to develop proficiency, we leave them behind. Continue Reading…

Retired Money: how to prepare for “Transitory for Longer’ inflation

As oxymorons go, you have to love the phrase “Transitory for Longer,” which comes up in my latest MoneySense Retired Money column. It looks at inflation, which of course is in the news virtually every day this summer, and one reason why stock markets are starting to weaken again (along with renewed Covid fears). You can find the full MoneySense column by clicking on the following headline: How might Inflation impact your Retirement plans?

As with trying to divine short-term moves in stocks or interest rates, I view predicting inflation — whether near-term, medium-term or longer-term — as somewhat futile. So the column preaches much the same as it would about positioning portfolios for stock declines or rises in interest rates: broad diversification of asset classes.

Asset Allocation for all Seasons

The ever useful four asset classes of Harry Browne’s Permanent Portfolio I find may be a good initial mix of assets to prepare for all possibilities: stocks for prosperity, bonds for deflation, cash for depression/recession and gold for inflation. Browne, who died in 2006,  famously allocated 25% to each.

That’s a good place to start, although as I point out in the column, many might add Real Estate/REITs and make it a five-way split each of 20%. Some suggest 10% in gold (both bullion ETFs and gold mining stock ETFs), which might be expanded to include other precious metals like silver, platinum and palladium. Some might add to this a 5% position in cryptocurrencies like Bitcoin and Ethereum, which some view as “digital gold.”

To the extent stock markets and interest rates will forever fluctuate over the course of a retirement, such a diversified approach could help you sleep at night, as some asset classes zig as others zag. Seldom will all these assets soar at once, but hopefully it will be just as rare for all to plunge at once.

Annuities and new “Tontine” approaches

Another approach to this problem is not so much Asset Allocation but what finance professor Moshe Milevsky has dubbed “Product Allocation.” Continue Reading…

How to generate Passive Income 

Image Credit: Pixabay

By Mike Khorev

Special to the Financial Independence Hub

Many of us strive for financial security; luckily, passive income investments open up the opportunity to make extra money on the side. 

All you need is the willingness to put in some fundamental groundwork: you don’t necessarily need savings to kickstart your investment. There are plenty of options when it comes to generating passive income that go far beyond the realms of compound investing. Here are some fresh ideas to get you started.

1.) Investments

Exchange-traded funds (ETFs)

Exchange-Traded Funds, known as ETFs, are a great way to invest in the stock market without needing to research individual companies. Investing in ETFs provides both capital gains and dividends. Diversify your investments to receive the maximum benefit. ETFs are rather low maintenance and yield a lower risk than regular equities.

Dividend-paying stocks

Feel the benefits of dividend stock investments with a range of stocks yielding up to 5% dividends. The hardest part is knowing which stocks are worth investment. The best way to generate larger profits is to choose dividends that come with franking credits. Stock market unpredictability is no secret, be willing to face a sudden rise and fall in value or cut dividends altogether.  

Robo-advisors

If you’re looking for an affordable financial advisor to manage your investments, Robo-Advisors could be for you. They personalise automated trading decisions based on your financial targets, limits and time frames for a fraction of the cost. They are one of the most passive forms of income. 

2.) Real estate

Rental income

Rental yield can be one of the most profitable forms of passive income. Experts state that small apartments containing 1-2 bedrooms have more success on the market generating returns of over 8%. Real Estate Agents will handle legal documentation, rent collection, and advertise your property for a recurring fee of 5-12% of the monthly rent.

Airbnb

Airbnb is a thriving marketplace with host’s estimated monthly earnings sitting at $924 per month. While properties are free to list, hosts are charged a 3-5% service fee and are liable to income tax. Many hosts invest earnings into outsourced housekeepers to maintain passiveness. 

Real estate investment trusts (REITs)

REIT investments are perfect for those who are interested in real estate without the responsibility of sustaining individual properties. Typically, REITs support non-residential buildings such as offices, apartment complexes, and retail centres. Commercial buildings are famous for yielding large profits, passive income will be paid in the form of dividends.

3.) Content creation and advertising

Affiliate marketing

Affiliate links are more negotiable than ever, not only do they support affiliate businesses, they are also a manageable form of passive income. Invest some time into digital content creation that generates healthy volumes of traffic. Aim to recommend products you truly believe in to build a trusting relationship with your audience and boost clicks.  Continue Reading…