Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

8 things to know before applying for Life Insurance

What should someone know before applying for life insurance?

To help you prepare for life insurance application processes, we asked insurance experts and business leaders this question for their best advice. From researching the required health tests to budgeting monthly costs, there are several tips that may help you when applying for life insurance.

Here are eight things to know before applying for life insurance:

● Know What Test Might be Done
● Clarify Term Life vs. Whole Life
● Determine Your Why
● Gather Your Paperwork Early
● Check Your Health Prior
● Assess Length of Policy
● Budget Monthly Costs
● Figure Out Future Needs

Know What Tests Might be Done

In the past, my life insurance companies would test for marijuana and reject applications for applicants who tested positive for marijuana use. However, since marijuana is legal in several states, but still illegal at the federal level, it is wise to work with an insurance expert to help work you through the process so you can find the right policy at the best rates to meet your needs. — Chris Abrams, Marcan Insurance

Clarify Term Life vs Whole Life Insurance

Learn the difference between term life insurance and whole life insurance so you can select the option that works best for your situation and budget. Term life insurance is an agreement between you and your insurance provider that lasts between 10-30 years. This type of insurance does not usually require a health exam. On the other hand, whole life insurance is truly meant to last your lifetime and carries additional benefits. However, it is also more costly. Understanding how these policies differ can help you make an educated decision about your life insurance. — Brian Greenberg, Insurist

Determine Your Why

The reasons why you are getting life insurance factor into the coverage amount and type of coverage you’ll receive. This can also help motivate you to stay consistent with payments. Most people who have families that rely heavily or solely on them for financial support and stability might opt to get sufficient life insurance coverage in the event of an unexpected death. Depending on the amount and type of life insurance, you provide an income replacement for your family in your absence. –– Rronniba Pemberton, Markitors

Gather Your Paperwork Early

Before applying for life insurance, it’s important to know what kind of personal information you’ll need to give the company. Some companies require detailed medical records while others just require simple information such as your name, date of birth, place of residence, and social security number. Prepare documents accordingly to ensure there won’t be any surprises along the way. — Tim Mitchum, WinPro Pet

Check Your Health Prior

Before applying for life insurance, you should be aware of your health. If you are rejected for life insurance, you could be affected down the road. You could have trouble getting life insurance from another company. Your credit score could even be lowered. The cost of life insurance could be raised out of your reach due to poor health. Learn if you have a preexisting condition. You can be denied life insurance if you have preexisting conditions. Check on the status of your own health condition before asking a life insurance examiner to look at you. — Janice Wald, Mostly Blogging Academy

Continue Reading…

Retired Money: Is “Core & Explore” too dangerous for retirees and near-retirees?

My latest MoneySense Retired Money column revisits the topic of Core & Explore. You can find the whole column by clicking on the highlighted headline here: Rethinking Core & Explore.

If the image on the left looks familiar, it’s because we used it last week to illustrate a republished blog on Explore by Michael J. Wiener, the blogger behind the popular Michael James on Money blog.

Go back to a couple of my Retired Money columns the last year and you’ll see I touch on the topic of speculation for retirees more than once, usually couched in the context of Core & Explore.

See for instance these pieces: Should Retirees Speculate? and How to Master Core & Explore.

“Core” is the prudent long-term strategy inherent in the MoneySense ETF All-Stars: low cost, diversified across geographies and asset class. Fully takes advantage of the “only free lunch:” that of broad diversification.

“Explore” on the other hand, is the polar opposite. The theory is that if you’ve taken care of 80 or 90% of your “Core” or Serious Money, you can go crazy with the other 10 or 20%, by “scratching the itch” of taking flyers on all those crazy things we’ve seen lately, like SPACs, cryptocurrencies etc., nicely surveyed by CFA Steve Lowrie in this recent blog: SPACS, NFTs and another Tech-inspired Silly Season.

Of course, as long as markets keep soaring, it’s hard not to love assets like Bitcoin or Ethereum, which may have tripled or quadrupled in a matter of months. Anyone who bought Tesla a year or two ago, or the ARK ETFs that were roughly 10% in Tesla and many comparable high flyers, was looking like an investing savant by the end of 2020, including Yours Truly. Continue Reading…

What the Olympics can tell us about managing Retirement portfolios

Adrian Mastracci, “fiduciary” portfolio manager at Lycos Asset Management touches on applying Olympian wisdom to your retirement portfolio.

Let’s reflect on the Olympians who recently competed at Tokyo. They deserve praise for braving years of preparation, training, commitments and pandemics.

Striving and competing to be best in their chosen pursuits. Regardless of outcomes.

I especially appreciate long distance events like cycling, running, swimming and rowing. They demand a wealth of endurance and perseverance, much like retirement portfolios.

Athletes often have to reach down deeper to muster more bursts of adrenalin. Just when it seems there is little, if anything, left in the tanks.

My top takeaways

Investors can draw some parallels from hard working Olympians. Wisdom from the Olympiad is relevant and applicable, particularly to long-term investing.

I summarize my top takeaways. Successful athletes require:

• Much dreaming and sketching out of personal goals.

• Setting specific, well thought out strategies.

• Disciplined game plans that realize on their dreams.

• Patience for the roller coaster of setbacks and achievements. Periodic tweaking of their action plans.

• Time horizons to learn and master their quests.

Olympians make wonderful ambassadors for the investing profession. I encourage investors to take a few moments and apply Olympian wisdom to the precious nest egg.

Athletes make choices and sacrifices along the way in their quest for Olympic goals. Investors balance choices between spending for the moment and saving for the long haul.

Risk is an inevitable part of the Olympics, as it is in long term investing. Athletes try different training plans, much like investors try a variety of strategies.

Investors can improve their long term portfolios with these four pearls of wisdom:

  •  Pay attention to issues that you can control:  risks, diversification, asset mix and investment quality.
  •  Ensure that no investment can cause serious portfolio damage: losses are typically your biggest destroyers of wealth.

Buy and sell methodically over time – timing the markets is a low percentage strategy.

Always expect the unexpected – a positive mindset is best for making portfolio decisions. Stick to simpler game plans. Skip the fancy moves.

All the very best to the athletes. May they treasure the accomplishments and cherish the memories.


Adrian Mastracci, Discretionary Portfolio Manager, B.E.E., MBA started in the advisory profession in 1972. He is portfolio manager with Vancouver-based Lycos Asset Management Inc.  


Information provided is intended for educational purposes only. Copyright ©2021, Adrian Mastracci. All rights reserved.

RBC finds young Canadians flocking to online DIY investing since pandemic

By Lori Darlington, President & CEO, RBC Direct Investing 

(Sponsor Content)

I was asked a question recently that made me look at what we’ve been experiencing during the pandemic in a new way.

A colleague asked if we would look back someday and see this as a time when people took more direct control of their finances – driven in part by so much else that feels outside of our control.  Considering the surge in Canadians becoming self-directed investors over the past 18 months, there may be some truth there, but I think there’s more to it than that.

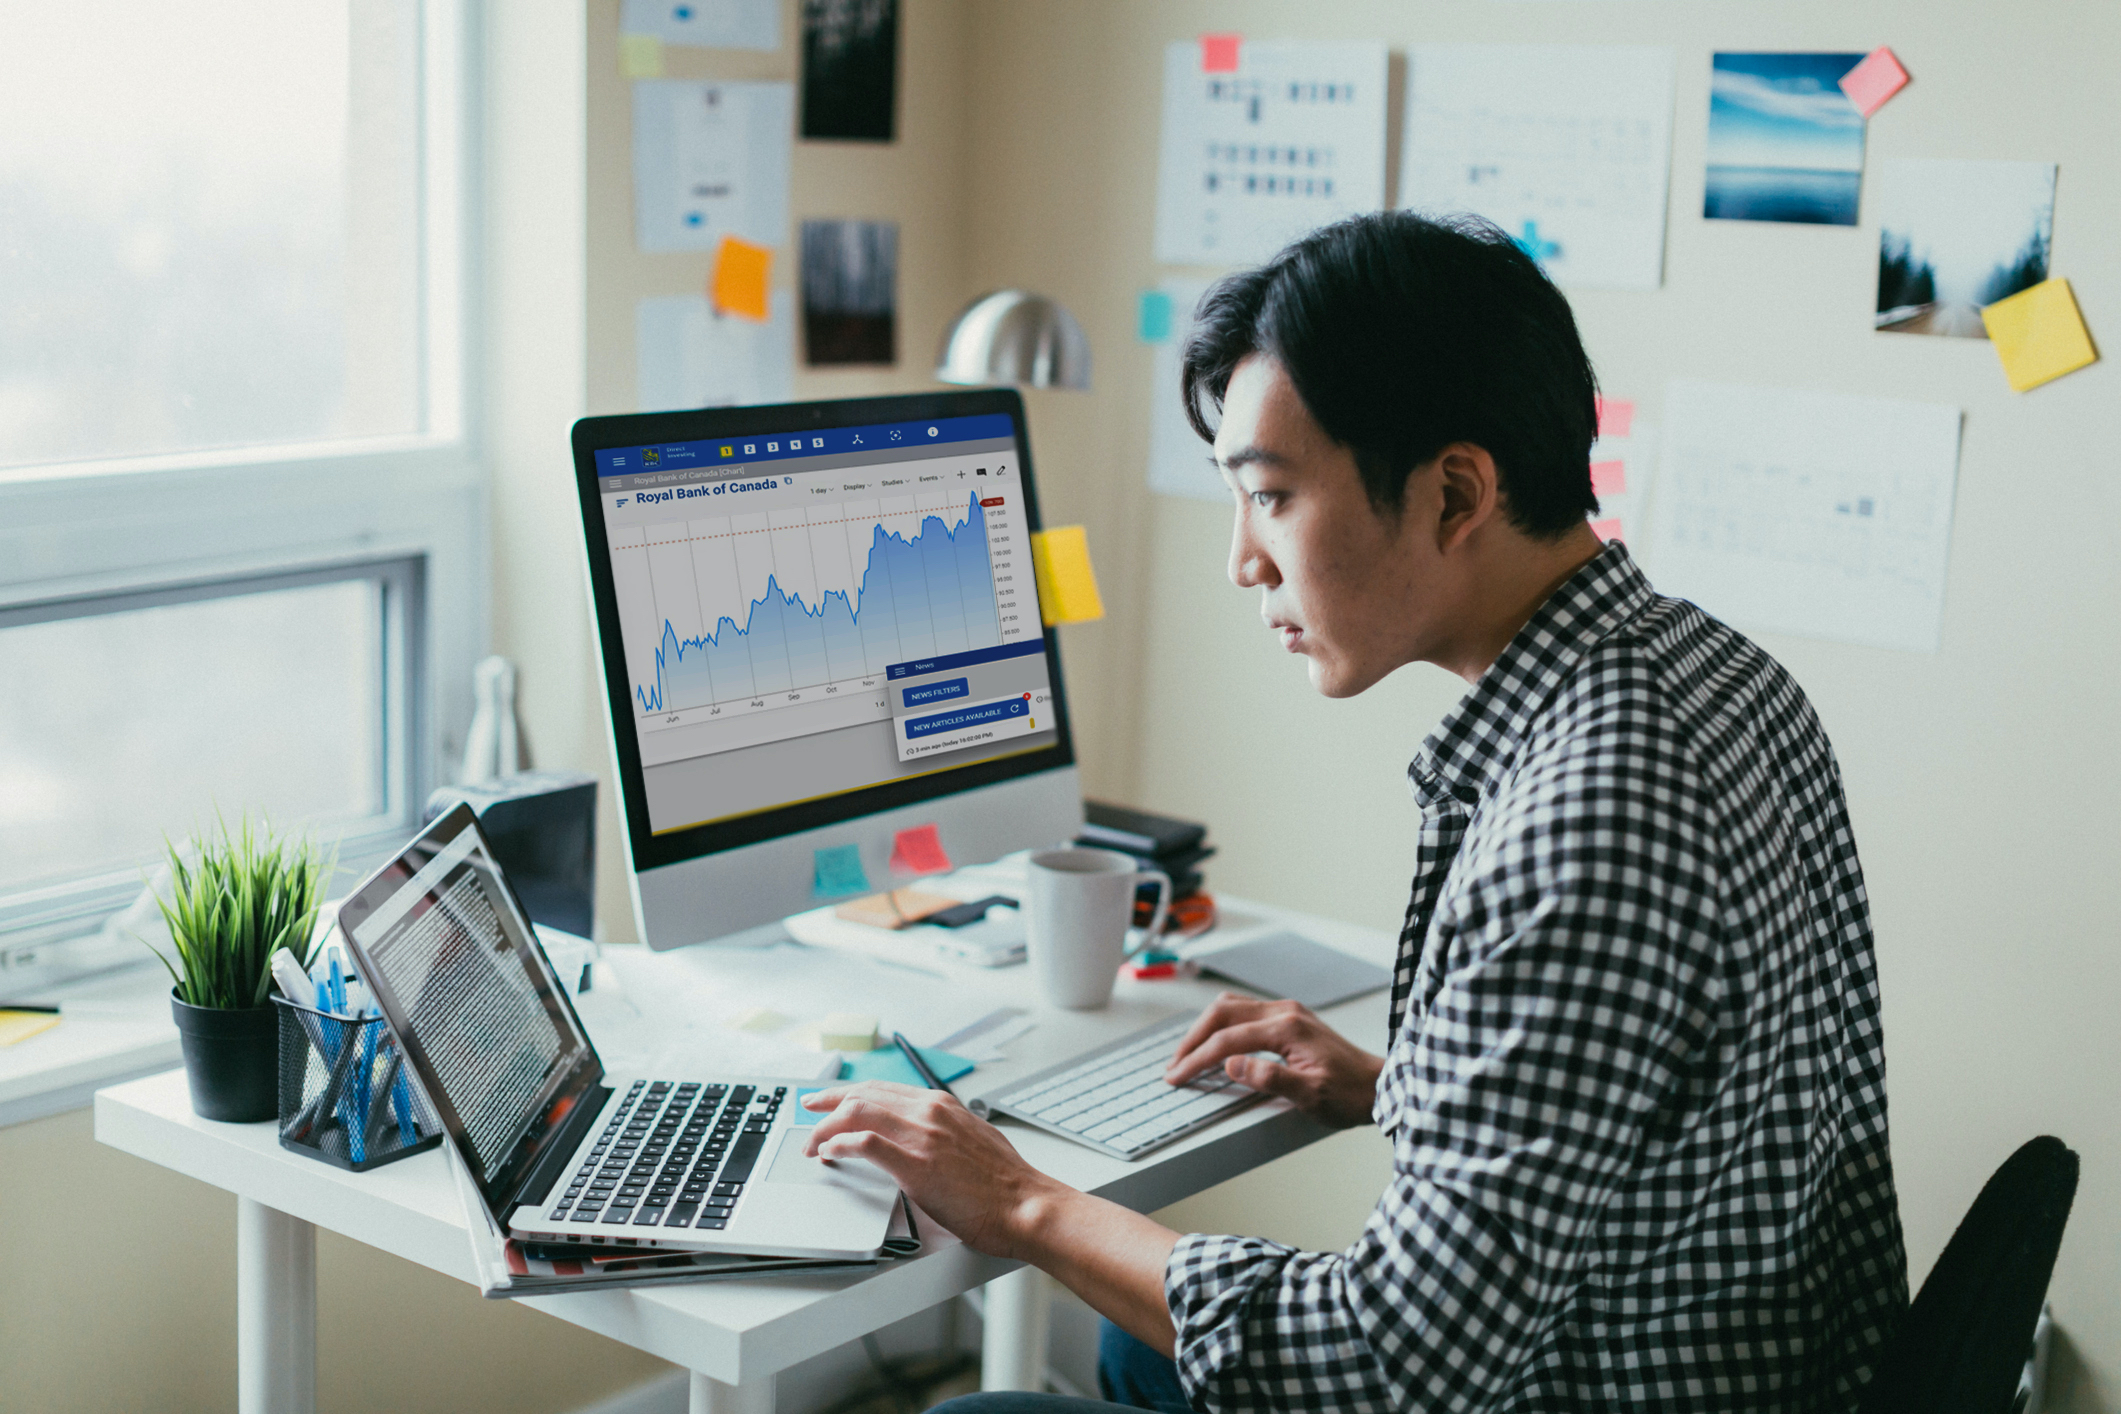
We’re seeing a new age group emerging within this wave of new online investors: increasing numbers of younger Canadians are becoming DIY investors. More than half of the new clients who’ve joined us at RBC Direct Investing over the past 12 months are under the age of 35.

I don’t think this is simply a pandemic spike. I believe this is a generational shift. These younger investors are comfortable with digital platforms and they enjoy doing their own research – two key aspects of being a successful self-directed investor.

What this means for us is that we need to ensure we’re providing comprehensive support for these younger DIY investors, to help them make informed online investing decisions.

Years ago, we realized we needed to connect with younger Canadians who might be interested in investing. We created our own editorial team to produce a digital magazine, Inspired Investor, which features quick reads that show how our everyday lives intersect with investing and to offer ideas and tips for both newer and more experienced investors. We also have a Getting Started Guide and how-to videos in our Investing Academy.

And you don’t need to be a Direct Investing client to access our Inspired Investor or Investing Academy resources. We want to help investors across Canada build their knowledge and ensure that they are making decisions that match their own risk appetite, so they can trade with confidence.

No-risk Practice Accounts

We also understand that each person has a different comfort level with trading online, so we provide a ‘no risk’ Practice Account. Just as it sounds, this account doesn’t use real money; we provide $100,000 in ‘pretend money’ so investors can test out making trades. You don’t need to be an RBC Direct Investing client to do this, but you do need to have an RBC Online Banking account. Continue Reading…

10 ways to get Funding for your Start-Up


What is one way to get funded as a start-up?

To help start-up owners get their projects funded, we asked business owners and investors this question for their best suggestions. From crowdfunding to generating user donations, there are several tips that may help you fund your start-up to scale your business and reach new goals.

Here are 10 pieces of advice for funding a start-up:

  • Seek Specific Funding
  • Know Your Price
  • Establish Key Partnerships
  • Join a Business Accelerator
  • Look Into Crowdfunding
  • Save for Self-Funding
  • Build a Customer Base
  • Reach Out to Your Network
  • Go to the Bank
  • Get User Donations

Seek Specific Funding

When researching the right path for getting funding for your start-up, consider seeking out sector-specific funding that is relevant to your business. Many lenders in the industry specialize in funding specific sectors in order to offer maximized support. Here at AVANA Capital, we actually specialize in the Renewable Energy sector. Our renewable energy lending products include pre-development, development, equipment, construction, and mini-perm financing, as well as distressed debt acquisition. — Allan J. Switalski, AVANA Capital

Know your Price

Funding is an incredibly important yet challenging part of being a founder. We mostly self-funded Kegelbell’s $160,000 that got us to market, including product testing, mold building, and FDA registration. Shortly thereafter, we took a few smaller investments as convertible notes that helped get us to where we are now. Today, we’re in the process of fundraising a larger amount that will help take Kegelbell to the next level. All that to say, I’ve run the spectrum in the world of start-up finances, and one thing I’ll definitely note is that you need to know your “ask.” Prepare and practice ahead of time and always have a success-oriented mindset. — Stephanie Schull, Kegelbell

Establish Key Partnerships

Get funding for your business through strategic partnerships. Especially for business owners with limited experience within the industry, particularly manufacturing-related industries, it makes sense to develop strategic partnerships with the best manufacturing and distribution companies to help secure the success of your business venture. With some stake in the game, these strategic partnerships are almost certain to win out when compared to other approaches. While not related to funding, in digital PR, we rely heavily on strategic partners to help grow companys’ online footprints. — Rronniba Pemberton, Markitors

Join a Business Accelerator

A great way to get funding for your start-up, especially if it’s a tech-heavy business, is to try a business accelerator or incubator. These are located across the country, mainly near colleges with business programs. Continue Reading…