Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.
Recently I previewed Fred Vettese’s completely updated and revised edition of Retirement Income For Life. I’m giving away an extra copy of the book and asked readers to enter to win by sharing when they took (or plan to take) CPP. The results were interesting.
Deciding when to take CPP is a key consideration of your retirement income plan. What I found interesting about the responses was the rationale or the stories behind these decisions. For instance, there is a lot of misinformation about the Canada Pension Plan: that it is government run (it’s not), that it will become insolvent before you collect benefits (it won’t), and that you could do better investing the money on your own (not likely).
These misconceptions can lead to poor decisions. It’s estimated that just 1% of CPP recipients elect to take their CPP benefits at age 70. Clearly more education is required.
Several of the responses in favour of taking CPP early showed this lack of knowledge or a perceived bias around the CPP program.
Some retired early and took CPP early to “avoid too many zero contribution years.”
While it’s true that your calculated retirement pension may decrease with each year of zero contributions, the amount of the decrease is typically less than the amount of the increase you’d get by deferring CPP (0.6% per month to age 65 and 0.7% per month to age 70).
CPP expert Doug Runchey uses the example that by waiting you will receive a larger slice of a smaller pie, but you will almost always receive more pie.
Earlier this year, the Hub ran a blog by Franklin Templeton Canada entitled A cure for the headaches of Fixed Income investing, written by Ahmed Farooq, Vice President of ETF Business Development for the company. Franklin Templeton is a sponsor of the Hub. Today’s blog is a question-and-answer session between Ahmed’s colleague, Jon Durst, Vice President, ETF Business Development, that picks up where we left off.
Jon Chevreau, Q1: Do you believe active management makes more sense in the fixed-income space versus the equity space? Perhaps it makes sense in both?
Jon Durst, Franklin Templeton’s Vice President, ETF Business Development
Jon Durst: There are merits to active management in both equities and fixed income; however, I feel recently, it has been a heavy skew towards active fixed income in this current market environment, and for many reasons. Early in March 2020, we saw a 50bps cut in interest rates by the Fed in the US: it was the first unscheduled rate cut since 2008 and the biggest cut since the financial crisis. There also appears to be a strong consensus on the street that rates will be “low for longer” going forward. If you own a passive fixed income strategy, the goal is to minimize tracking error to the index and what it cannot do is to adjust or try to anticipate any type of market events, like interest rate changes or changing company fundamentals.
This can certainly be a worrisome event for most advisors if they buy their own bonds directly or passive fixed income products covering different sectors/regions, as they have to scramble and figure out if they should continue with the same fixed income allocations in their portfolio, as the onus of making any changes to their portfolio will be on them.
Active managers with years of experience can focus solely on their investment mandates and can adjust to different types of market events, such as shape of the pandemic recovery or the consequences of the Democrats winning the 2020 US elections.
Outsourcing in this market environment and buying active fixed income exposures that align with your client’s outcomes will hopefully provide a calming effect that is certainly needed. Not to mention, active fixed income ETFs in particular are now often priced very similarly to passive indexed products, which is even more important in this low rate environment to help maximize clients cash flow.
Jon Chevreau, Q2: For income-oriented retirees, do you generally see more opportunity in corporate or government bonds?
Jon Durst: I do see more opportunity in corporates debt, as the yields are higher, they also tend to be less sensitive to interest rate movement, but the risk level and volatility do tend to slightly go up.
A passive aggregate bond strategy that encompasses both corporate and government debt in Canada yields around 2.55%, a pure passive Canadian government bond strategy at 2.11%, and a passive Canadian corporate strategy around 2.77%. On the other hand, for example, an active Canadian corporate strategy FLCI – Franklin Liberty Canadian Investment Grade Corporate ETF, yields 3.12%. An active manager can select certain bonds over others, perhaps looking for higher coupons and/or YTMs, or overweighting certain sectors that will benefit from the pandemic trade or the Biden Presidency.
Jon Chevreau, CFO of Financial Independence Hub
Jon Chevreau, Q3: How much exposure should Canadian investors have in US and international bonds and through what vehicle? On that note, what is your stance on currency hedging?
Jon Durst: We do need to think outside of Canada; even from a fixed income perspective, Canada’s total debt in comparison to the world is about 3-4%. Also, there is no tax incentive to buying solely Canadian debt, unlike the Canadian Dividend Tax credit provided on distributions from Canadian equities. There are many fixed income opportunities to take a look at – a solution based option via a Canadian Core Plus strategy is one – where you would still keep 70-75% in Canadian bonds and have an active manager select the 25-30% in the US and/or globally. You could also consider a more broad-based global aggregate option, having the portfolio manager look for opportunities from a global stand-point, which offers the PM a lot of flexibility to diversify geographically and from a currency perspective. Yields in different countries can vary significantly which can create a lot of opportunity for higher yields and capital appreciation, not to mention diversification benefits.
In terms of buying a pure-based exposure – in other words, buying direct US, EAFE or EM debt, either by purchasing individual bonds or a managed product — I find most advisors are still tippy toeing into pure US, EAFE or EM debt spaces: most still maintain a home country bias and the complexity of selection, weighting, and trading these exposures is difficult, to say the least. Those that see the value in investing outside of Canadian debt usually outsource this complexity by using active fixed income strategies that provide access to the US/Global exposure, in addition to Canadian bonds.
I am for 90-100% in currency hedging fixed income exposures. With interest rates and yields being at historical lows, another level of worry should not be placed on how the global currencies are going to perform relative to the CAD$, especially in fixed income, which is supposedly the conservative component of a client’s portfolio. In my opinion, currencies should be hedged out as much as possible in fixed income.
Jon Chevreau, Q4: Your blog back in February compared bond funds to GICs. Do you see a role for both and in what proportion?
Jon Durst: In this environment, it can get even trickier: do you really want to lock into GICs for a certain period of time at a certain rate? Or want to be nimble and have liquidity? It’s a question on how to balance stable income that is locked in (currently at historically low rates) and/or including a short term bond strategy that can yield a little more in this environment and provide liquidity in the event of a requirement. I am beginning to see a fair number of advisors who have started to allocate to short term bonds funds as client GICs mature. Usually cash, GICs and short-term bond funds make up about 5-10% of a clients portfolio, but GIC investors are being compensated very little, so short term bond funds are being used for those with a higher need for income, and cash now being used for those with a 100% capital preservation requirement (not taking inflation into the equation). GICs appear to be losing some steam.
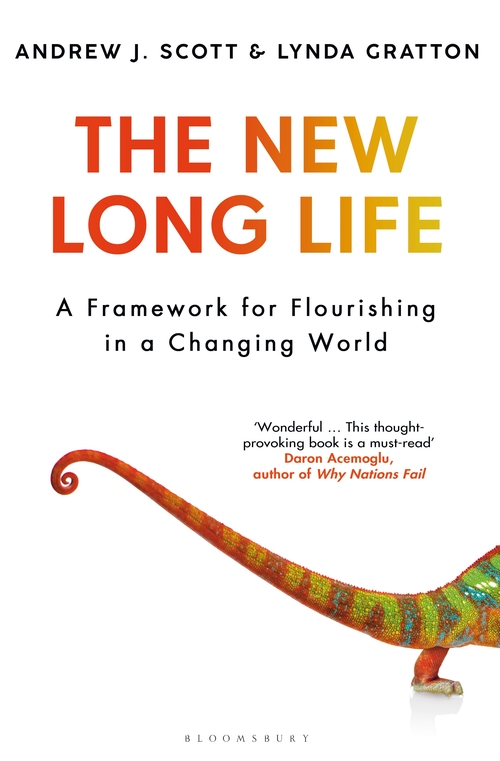
“In the face of longevity, if we want to reimagine age then we must first decouple the idea of a simple link between time and age. That requires imagining your age as malleable… It is this malleability that underpins the redesign of life stages.” Andrew J. Scott & Lynda Gratton, The New Long Life, 2020
Scott and Gratton challenged our minds, that if we were to look at the promise of living a longer life that would mean the lockstep three-stage experience would evolve and stretch, and we would have to reimagine a multi-stage life, more fluid, perhaps not so orderly. It would mean we would need to rethink how we finance this potential longer life, transform our personal journeys and as suggested now here in the sequel: rediscover our human ingenuity.
For all the side steps and jump-starts that a fluid and frequently interruptive multi-stage life may bring us, we will need to be better as masters of our own transitions.
“Human ingenuity has led us to extraordinary new technologies and substantial gains in healthy life expectancy. Yet … the answers to the question we have posed will be solved with social ingenuity.”
Continuous advance of technology and longevity
One of the great powers our two authors have is the ability to draw linkages between factors that are now shifting our society, and a prime example of that is both the continuous advance of technologies and longevity. By extension, this particular linkage recasts our notion of work and careers, wealth and health. What we do, where and how we work and for how long we choose to work. All this in mind the question left for us is: in what ways will we as individuals, employers, educators and governments reshape our society?
To answer that, The New Long Life poses leaning forward questions and threads many plausible possibilities around all this transitioning we will undoubtedly face regardless of age. Human questions is where the book begins and then nourishes our minds sprinkling ideas at us, somewhat like fish food for thought, right through each chapter. This is what makes this book together with the first, one masterful opus. Thus, my recommendation is to begin with a read of The 100-Year Life. (Reviewed by Mark here.) Continue Reading…
It’s no secret that the world of digital marketing is continually changing, and every individual marketing channel in it is also rapidly changing all the time. Meaning, if you want to utilize digital marketing to grow your business effectively, you’ll need to stay up-to-date with the current trends.
Although some digital marketing parts stay relatively the same, like how search engine optimization works and the importance of email marketing, there are also significant changes and even brand new channels that can significantly change the game.
In creating any digital marketing strategy, however, it is essential to focus on creating a strong fundamental that you can easily expand to other digital marketing tactics; these fundamental tactics can act as a vital building block for your business, so even when you’d need to adopt a new trend, you can easily integrate it with this existing fundamental.
That said, here are the fundamental digital marketing practices in 2020 and onwards:
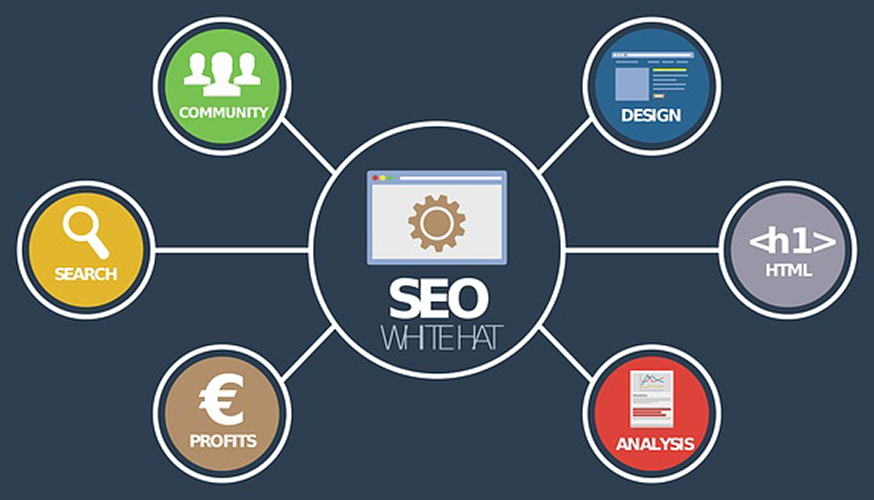
1.) Content Marketing and SEO
In this age of social media, content is king.
Whether you can be successful in your digital marketing or not would ultimately depend on whether you can attract and engage enough audience through your content:
You generate leads by attracting prospects with valuable content.
You nurture leads by using content to educate your prospects about your product/service and establish your credibility via consistent content quality.
You convert leads into customers by using content to convince people to buy
So, content should be the backbone of your overall digital marketing strategy, and SEO (Search Engine Optimization) would be the primary way for people to find your B2B brand.
However, since more businesses are now focusing on content marketing, the competition in attracting the audience’s attention with content is now much tighter. Simple and informative, educational content that worked in 2017 simply won’t cut it anymore these days, as readers now expect the highest quality of information and authoritative data.
Also, consumers now expect various forms of content in textual blog posts and white papers and videos, podcasts, infographics, and other mediums. Diversifying your content is very important and offers more personalized and interactive content for each audience, which will bring us to the next point below.
2.) Conversational and Personalized Marketing
The rise of various AI and machine learning technologies has provided us with more ways to implement highly-customized and conversational marketing tailored for each prospect.
One of such technologies is the chatbot, which has been popular among many businesses in recent years. A 2017 survey by Gartner has predicted that 47% of organizations will implement chatbots for customer service in the years to come.
Chatbots can allow businesses to implement personalized marketing with different implementations. For example, in a sales inquiry conversation, the chatbot can ask for preliminary questions about the prospect’s preferences, available budget, and so on, so when the chatbot finally passes this prospect to a human sales rep, the process would be much more seamless for both the sales rep and the prospect.
According to Fractional CMO Mark Evans, conversational and personalized marketing channels can help marketers create highly-targeted marketing campaigns and gather more information about your prospects and customers.
3.) Video Marketing
Video is technically a part of content marketing, which we have discussed above. Still, in the past half-decade, video marketing has grown to be a powerful digital marketing channel that deserves its attention. Continue Reading…
Building a company from scratch and being your own boss are the dreams of many. However, it is small businesses that have it the hardest, and you’ll need to bring your A game in order to survive the first year of operation. There are many ways that a small business may stack the deck in its favor, however. Here are the tips you need to know in order to keep your business from going under.
Maintaining Cash Flow
Businesses strive to make money, but a business owner must also cover his or her overhead expenses in order to stay in business. Therefore, one needs to maintain one’s cash flow in order to continue to compete. This is especially pertinent when it comes to invoices, as invoices can be great for consumers while being a detriment to smaller businesses.
An invoice factoring company can help you maintain cash flow by buying your invoices from you at a slight loss in exchange for immediate payment. While this isn’t much an issue for established, successful companies, small businesses can benefit tremendously from this practice.
Reducing Costs
Another important way to strengthen your cash flow is to simply reduce the costs of some of your necessary experiences. In some cases, you can outright eliminate expenses, as well. For instance, you can try to find better prices within your supply chain, or you can even buy directly from manufacturers in order to cut costs. In such cases, you need to be sure that you’re not losing too much in terms of quality or reliability, however. Continue Reading…


 Posted By
 Recently I previewed Fred Vettese’s completely updated and revised edition of Retirement Income For Life. I’m giving away an extra copy of the book and asked readers to enter to win by sharing when they took (or plan to take) CPP. The results were interesting.
 Posted By
 Posted By