Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Pros and Cons of Vacation Timeshares  

By Becky Williams

(Sponsored Content)

If you are like nearly everyone, the time that you spend on vacation represents some of the most pleasant and days of the year. You may spend a good deal of time trying to decide what will be the most amazing type of vacation you can take. One option you may want to focus on is obtaining a vacation timeshare. There are a number of significant benefits associated with a vacation timeshare.

A timeshare may not be for everyone and there are some factors that may make this type of vacation property not the perfect choice for you. However, by weighing and balancing the pros and cons of timeshare ownership, you will be able to make an informed, educated decision as to whether this type of vacation property makes the most sense for you. You will be able to find a vacation timeshare that is perfect for you today and into the future as well.

Guaranteed, reliable vacation

A primary benefit associated with a timeshare is that you have a guaranteed, reliable location to spend your precious vacation days. You do not have to spend an inordinate amount of time trying to find an ideal place to spend a vacation. You need only undertake that task one time when you select a vacation timeshare property the first time.

With a vacation timeshare, you know precisely what to expect. You will never again face a situation in which you are uncertain about what your vacation destination and lodgings really will be like. The reality is that this type of uncertainty, which is completely eliminated with a timeshare, has been a major reason why so many people have experienced vacation disasters.

An ideal location for you

Another key benefit of going the timeshare route when it comes to a vacation property is that you will have a destination and location that is ideally suited to you. There is a significant array of different vacation timeshare options in many, many locations across the United States and around the world.

On a related note, you can enjoy another benefit of getting a vacation timeshare. Many timeshare companies offer you the ability to swap your timeshare location for a particular year. In other words, you can trade your timeshare location with someone else at a different location. This provides you with both reliability and consistency as well as a degree of flexibility should you elect to try something different one year.

Entertaining family, friends, and colleagues

Although your main purpose in purchasing a timeshare is to be able to have a set vacation location for yourself and your immediate family, other people in your life can benefit from the timeshare experience as well.

For example, you may not have the need to use your timeshare for a particular period of time set aside to you. As a result, you can offer your timeshare to extended family members, to friends, and to work or other types of colleagues. Often, the owner of a timeshare will donate a stay to a charitable organization. The stay is auctioned off to raise money for the organization. In short, there really is a tremendous amount you can do with a timeshare, not only for yourself and your immediate family but for a broad spectrum of other people who may be important in your life as well. Continue Reading…

The touchpoint: on being “Packaged” out from the Corporation

By Kevin Press

Special to the Financial Independence Hub

Since being restructured out of my 14-plus-year, rather comfortable position with a global insurance company, I’ve been asked one question more than any other.

Did you see it coming? The answer in my case is yes. I suspect that’s true for most 50- or 60-somethings who’ve found themselves accepting an invitation to “the touchpoint” from their boss, only to find that it’s been moved from their office to HR at the last moment.

Of course, if you’re anything like me (which is to say that you go to work every day like a Jimmy Stewart character in a Hitchcock movie) then nothing comes as a surprise.

I had two thoughts in quick succession when I received my summons. First, what day is it? Tuesday. Dreaded dead-man-walking Tuesday.

Second, how many documents can I email home between now and zero hour? (Nothing sensitive of course, for the record.)

It’s at this point that things began to turn a bit darkly comic. On my walk to HR, I’m stopped to commiserate with a colleague about the dumb email she just got from her boss. Smile and nod.

Young HR person hands me “The Package”

Turn the corner and my fears are realized. The boss is sitting with a too-young member of the HR team, both sporting the kind of sympathetic look that makes you wish you’d forgotten your glasses. I’m told I’ve “had a good run,” which makes me feel a good deal older than my 52 years. Continue Reading…

Retired Money: Whether you’re a stock or a bond may determine when to take CPP/OAS

When to take CPP/OAS? My latest MoneySense Retired Money column passes on a fresh perspective on the old topic of whether you should take CPP or OAS early or late. You can find the full piece by clicking on the highlighted text here: Why aggressive stock investors should consider taking CPP early.

One of the main sources cited in the piece is fee-for-service financial planner Ed Rempel, who has contributed guest blogs to the Hub in the past. See for example Should I take CPP early? Some Real Life Examples or Delay CPP and OAS till 70? Some case studies.

Ed Rempel

When he recently turned 60, Rempel opted himself to take CPP himself because of course he considers himself primarily a “stock” when it comes to investing (using the concept from Moshe Milevsky’s book, Are you a stock or a bond?). He figures he can get good enough returns by investing the early CPP benefits that he will more than make up for the higher payouts CPP makes available for waiting till 65 or 70. Same with OAS, which he figures even balanced investors should take as soon as it’s on offer at age 65.

The corollary of this is that if you consider yourself primarily a fixed-income investor, then you should probably take CPP and perhaps OAS too closer to age 70. Compared to taking CPP at 65, taking it at 70 results in 42% more payments, while OAS is sweeter by 36% by delaying the full five years.

The MoneySense piece also quotes retired financial advisor Warren Baldwin, who chose to take CPP himself by age 66. Like Rempel and most financial advisors, Baldwin has a healthy exposure to equities. But he also cites a couple of other reasons for his decision. Baldwin, (formerly with T. E. Wealth), figures the value of the CPP fund to pay you the pension at age 65 is at least $250,000: more if you factor in its inflation indexing. The latter is an important consideration, especially for those (like Yours Truly), whose Defined Benefit pensions are not indexed to inflation.

Baldwin took his own CPP at 66, a year after his final year of full-time employment income. He did so “mainly for the cash flow and portfolio maintenance.”  But Baldwin has other reasons too. “I do not want to leave the CPP too long into the future in case the government changes the terms on it or the rate of income tax might rise … Look at how many changes they have made in the last 20 years.”

If a retiree’s marginal tax bracket jumped from 35% to 45%, Baldwin says deferred CPP would face a heavier tax load, while if benefits are taken earlier they would be taxed at more modest rates. And if retirees also have significant sums accumulated in RRSPs and RRIFs, the extra income might push up their Marginal Tax Bracket.

CPP survivor benefits also need to be considered

Warren Baldwin

Finally, Baldwin considers the “estate value” of CPP. “If two spouses have the maximum CPP and one dies, the survivor will not get much from the ‘survivor-ship’ aspect of CPP … So, if the ‘value’ of the CPP at 65 is in the range of $300,000, then if you die before you collect, there is quite a loss. Continue Reading…

The 4% Rule conflates Asset Accumulation with Income Stream

De-accumulation blogger Edward Kierklo

By Edward Kierklo

Special to the Financial Independence Hub

Nothing has worked more effectively for the financial industry to justify asset accumulation or AUM (Assets Under Management) than the theoretical underpinnings of the 4% “rule” or “guideline.”

There are innumerable articles on how individuals will require one million dollars or more for retirement based on this dubious principle.

Certainly it is crucial to save but to focus on any particular threshold misses the point that what counts in retirement is a regular, dependable stream of income for a lifetime.

Motley Fool does not debunk the 4% rule explicitly but offers lots of caveats in this piece.

Take this recent article on Marketwatch saying that one million is not enough.

Balancing lifestyle and longevity

There are two factors in retirement to balance: lifestyle and longevity. Any 4% or otherwise rule is irrelevant if longevity is uncertain. Most people want to maintain a certain quality of life in retirement as well as living healthy.

Here is a hypothetical question: would you take Social Security if it were offered as a lump sum or continue to collect it monthly for the rest of your life (with the bonus of inflation adjusted payouts)? Continue Reading…

Are all Pension incomes created equal?

Image Shutterstock

By Ian Moyer

Special to the Financial Independence Hub

Pension incomes are not created equal. They come in all shapes and sizes. They are as varied as the people who have accumulated them and who seek to use them. 

In this seemingly infinite variety, in this mathematical complexity, there is a common thread as far as advisors are concerned: delivering clients the most after-tax income possible. 

CPP, OAS, Defined Benefit Pension, Dividend Income, Interest Income, RRIFs, Part Time Employment Income, Corporate Dividends, TFSAs: These are just a few of the various sources of income individuals may have access to when they exit the workforce.  Upon retirement, decisions about what, when, and how much income to draw upon, move to the forefront.

Tax is key to coordinating multiple income streams

Coordination here is key as each of these sources of income is subject to different tax rates, different tax deferrals and different estate taxes. Tax is key, in other words.

Recent or prospective retirees need more than a competent advisor at this stage. Understanding the tax rates, tax deferral rates and the implications regarding OAS and Income Splitting is one thing. But accounting for these sources of income and the complicated ways in which they interact requires an algorithm.

The specialized software, Cascades, cascadesfs.com, performs these calculations, giving users informed withdrawal strategies. Designed by financial advisors in partnership with software developers, Cascades uses actual tax rates, not average tax rates, projecting for the duration of retirement, including longevity risk.

Because numbers require context to be meaningful, let us consider prospective retirees Bill and Anne Smith.

Case Study: a Couple in their late 60s

Retirement Plan: Bill and Ann are 68 and 67 currently. They have been retired for a few years but still have RRSPs and a LIRA and want to know if they should start using them for income or defer payments until age 71. 

Income Sources: Both have CPP and OAS. Anne has a defined benefit pension from having worked as a teacher. 

Investments: Bill has a healthy RRSP and Anne has a modest RRSP and a LIRA. They have maxed out their TFSAs and each have about $100,000 additionally in individual non-registered accounts. 

Total: 12 different income sources and investment accounts to manage for retirement income

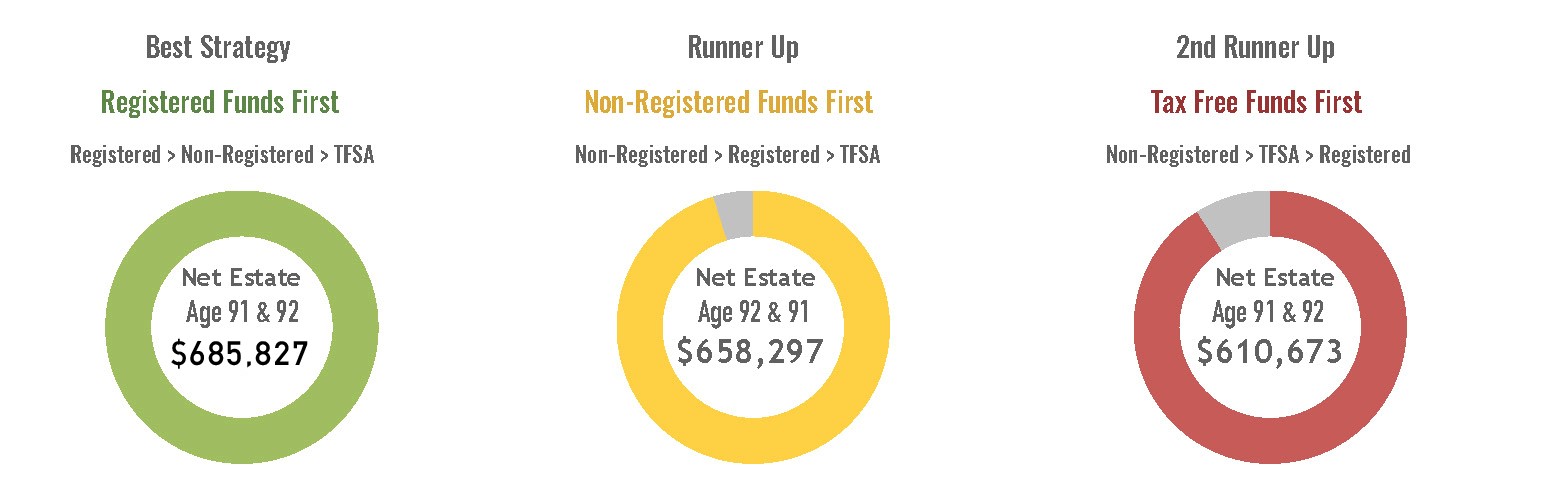
Cascades provides direction in the following way. Users — whether they be Anne and Bill themselves, or their advisors — fill in a detailed online questionnaire, submit their responses and in under ten seconds they have a report. This report (an excerpt is shown at the top of this blog) automatically gives three potential strategies and shows which one works best. For Anne and Bill, drawing down and re-investing their registered accounts first is expected to save them over $75,000 in their estate compared to a complete deferral of their registered money. 

As far as Bob and Linda Sanderson are concerned, on the other hand, a Cascades report advises them to do just the opposite and ultimately predicts a savings of $125,000. Here’s how:

Quite different withdrawal recommendations for this younger couple

Bob and Linda are both 55 and currently working. They plan to retire in 10 years. They have a rental property they maintain that they plan to sell in 15 years and want to know how to plan for the long-term. 


Income Sources: Both will receive CPP and OAS. Bob will receive a small defined benefit pension. Both will earn rental income until sale of the property. Both will receive corporate dividends until age 80 from a holding company. 

Investments: Both have large RRSPs, nearly capped TFSAs, and a small amount of non-registered savings. Additionally, Linda has a small LIRA. 

Total: 18 different income sources and investment accounts to manage for retirement income.

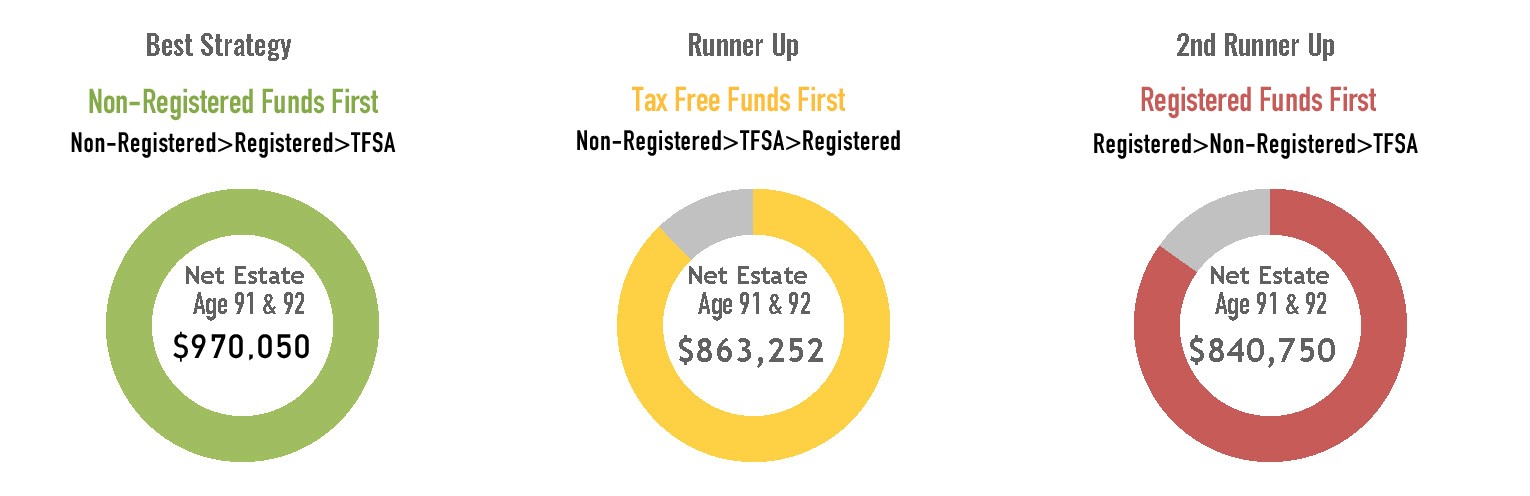
Cascades proposes three withdrawal strategies and highlights the best plan. Using all of their non-registered savings before rolling over registered investments will save Bob and Linda over $125,000 in their estate compared to an early drawdown of their registered money. Cascades software is designed to help users do their due diligence on the matter of retirement planning. The results are specifically tailored to the retirement in question and they are reliable, informed and rigorously defined as they are by Canada’s vast and varied tax laws.

.

Ian Moyer is the founder of Ian C. Moyer Insurance Agency Inc. and Cascades Financial Solutions Inc.