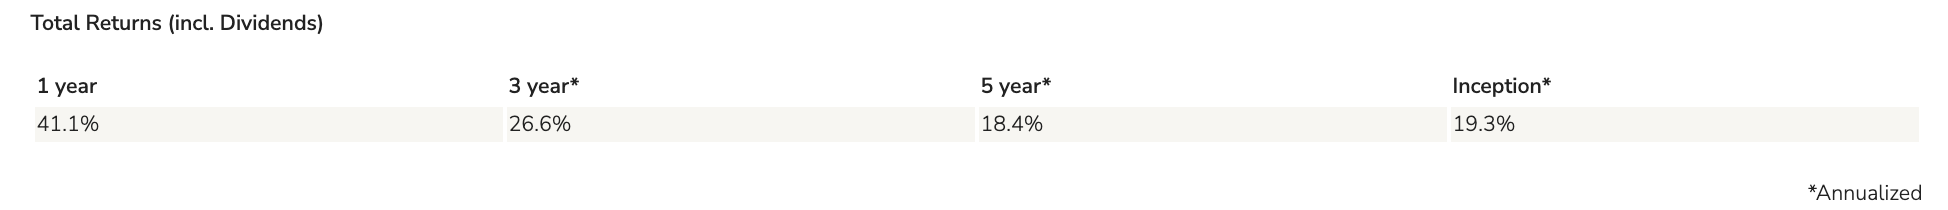
Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Before you Decide: Should I own Individual Stocks?

Image created with ChatGPT by Lowrie Financial


By Steve Lowrie, CFA

Special to Financial Independence Hub

The first investment I ever made was an individual stock. At that time, there were no apps or online accounts available to make this purchase. Instead, I walked into a local brokerage office, opened an account in person, sat across a desk from a stockbroker and asked him to place the trade. By the time I received the confirmation slip in the mail, roughly half of my money was gone.

What stays with me is not the loss. It is that nobody asked me anything. Nobody asked why I believed that company would do well, what would happen to my plans if I were wrong, or how much of my savings I was prepared to put behind a single idea. The order was placed, the confirmation arrived in the mail, and that was the whole of the advice. I am not certain I would have welcomed those questions at the time, since I was young and overconfident, but I have thought about them for more than thirty years and I have asked many people those same questions.

The reason they still matter is that the conversation itself has never changed. It is hard to get through a dinner or a business event without someone describing a stock they bought years ago that has gone up substantially, and what we rarely hear about is all the other stocks they bought that went nowhere. That is not because anyone is being dishonest. It is simply how memory works. We keep our winners close, we enjoy talking about them, and the disappointments quietly fall out of the story.

The stock name changes. The story never does.

There are good reasons to own stocks. Over long periods they have been one of the most effective ways to grow wealth and protect purchasing power from inflation. So the more interesting question is not whether to own stocks, but how to own them. Should you try to identify a handful of winning companies, or own a broadly diversified pool of them through mutual funds or ETFs? After more than three decades of watching Canadian families succeed and fail at this, my answer is direct: for almost every investor, there is no financial planning reason to own individual stocks. I am not saying you should never own an individual stock. I am saying the decision deserves a good reason. In my experience, most investors have never been asked to supply one.

Why is Picking Winning Individual Stocks so Difficult?

The challenge is not recognizing great companies after they have succeeded. It is identifying them beforehand, when their future is still uncertain and their share price already reflects everything millions of other investors know and expect.

Research by Arizona State University professor Hendrik Bessembinder shows just how difficult that is. In Do Stocks Outperform Treasury Bills? published in the Journal of Financial Economics, he examined the lifetime returns of every U.S. common stock since 1926 and found that the best-performing 4 per cent of listed companies accounted for the entire net wealth creation of the U.S. market above one-month Treasury bills. Slightly more than four out of every seven individual stocks did not even match the return of a Treasury bill over their lifetimes. That deserves a second read, because it means most individual stocks are not merely disappointing. Most individual stocks did worse than holding cash. Nor is this only an American phenomenon. Bessembinder and his co-authors extended the work to more than 64,000 companies worldwide and found the same pattern outside the United States.

The point is not that the stock market is a bad place to be. Over the long run it has rewarded investors generously. The point is that the reward has been concentrated in remarkably few places, which changes what you are actually attempting when you buy a handful of companies. You are not making a modest bet with slightly unfavourable odds. You are trying to locate a very small number of names inside a very large field, in advance, with a share price that already reflects everyone else’s best guess. Bessembinder tested exactly that by simulating single-stock selection repeatedly, and the single-stock strategy underperformed the broad market in 96 per cent of those simulations.

So why does anyone keep doing it? Because nothing ever tells them to stop.

You do not have to lose money for stock picking to fail. You only have to earn less than you would have earned by owning the broad market. An investor can make money every single year, comfortably ahead of any fixed-income alternative, and still be quietly falling behind the entire time. The statements look fine. There is no line item for the return you did not earn, no alert when the gap widens, and nothing that ever prompts a review. It is the most expensive kind of loss precisely because it never announces itself.

A broadly diversified portfolio removes the guessing. You will own plenty of disappointing companies along the way, but you will also own the small number of extraordinary ones, because you own all of them.

If an Individual Stock I bought went up, does that mean it was a Good Decision?

Not on its own, and this is where the first article in this series does the most work. There I made the case that a good decision can produce a bad outcome and a bad decision can produce a good one, and I offered a test for telling skill from luck: could you lose on purpose? In a game of skill you can deliberately play badly and reliably lose. In a game of chance you cannot.

Apply that test to stock picking. If you set out tomorrow to deliberately choose the worst-performing stocks in the market, could you reliably do it? Almost nobody can, and that tells you a great deal about how much skill is actually available in the activity. The answer is the same whether your last pick went up or down. So if you put a significant portion of your portfolio into one company and watched it appreciate, you may well have seen something other investors missed, or you may equally have taken a risk you did not need to take and been lucky enough to have it work out. The return by itself cannot tell you which one happened.

This matters because success changes behaviour. A winning stock reinforces our belief that we have some ability to spot winners, and once we believe that, there is no reason to change what appears to be working. I have watched that sequence more times than I can count, and it almost always runs in the same direction. The winner is rarely the last decision. It is the decision that funds the next, bigger one.

Am I taking a Risk I do not need to take?

Concentrating wealth in a few companies introduces company-specific risk, which we call uncompensated risk in investment jargon. In plain English, it is a risk that can largely be diversified away, so there is no reliable reason to expect a higher return simply for bearing it.

Concentrated portfolios can certainly outperform diversified ones, sometimes by a great deal, and that has never been in dispute. The question I would ask is a different one: do you need to take that chance to get where you are going? If a diversified portfolio already gives you a reasonable probability of accomplishing your goals, then any additional risk that could jeopardize them should clear a very high bar. In my experience, very few of them do.

Is a Canadian Portfolio as Diversified as it looks?

There is a second concentration problem that most Canadian investors never notice, and it sits underneath the first one. The Canadian market is not a balanced market. It is dominated by financial services, meaning the large banks and insurers, and by resources. Rocks and trees, as it is often described. Entire sectors that make up a large share of global markets, including technology, health care and consumer businesses, are only lightly represented here. So a portfolio invested entirely in a Canadian index is already a concentrated bet, even though it holds hundreds of companies and carries the word diversified on the label. Continue Reading…
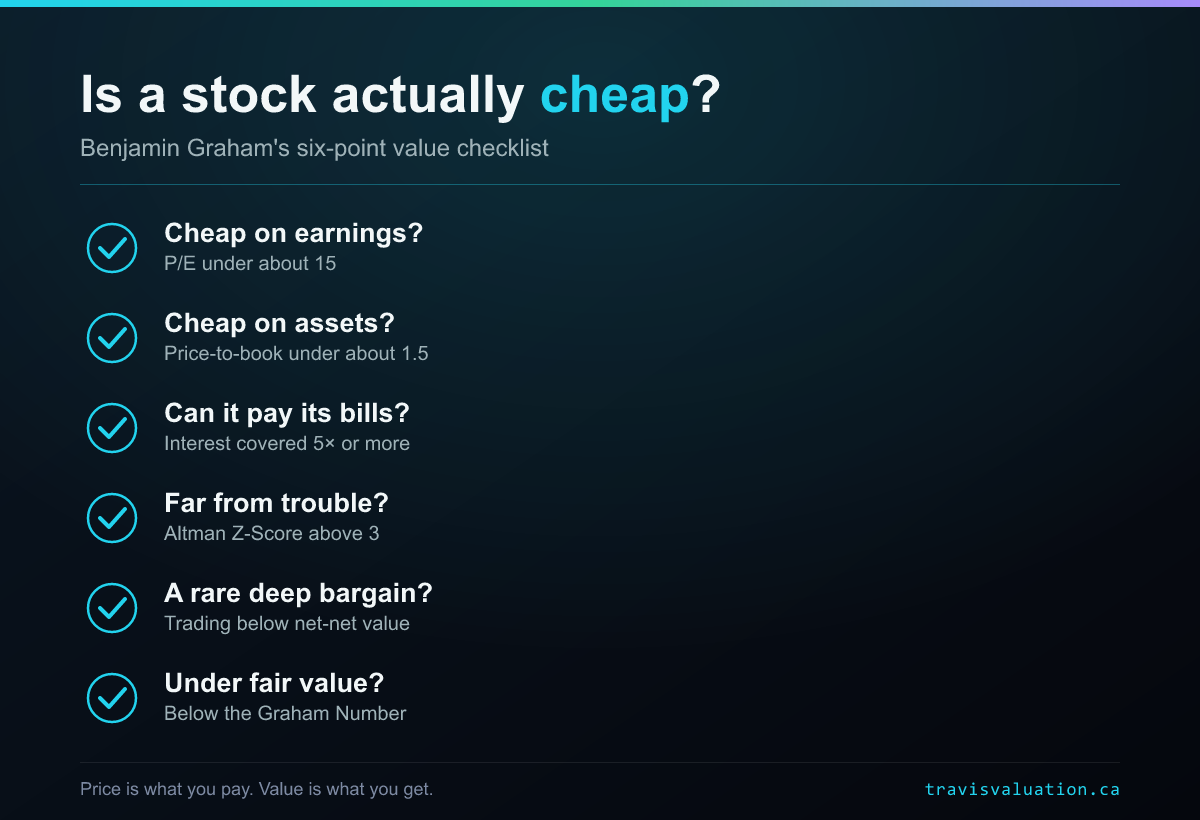
How to tell what a Stock is actually Worth: A Beginner’s Value Checklist

Run this checklist automatically on any stock at travisvaluation.ca

By Curtis Travis

Special to the Financial Independence Hub

Nearly a century ago, Benjamin Graham — the man who taught Warren Buffett — put the whole game in one sentence: “Price is what you pay; value is what you get.”

The trouble is that your brokerage app shows you the price in giant letters and says nothing at all about the value. So, most of us end up buying the number that’s flashing, not the business behind it.

The good news is that estimating what a business is worth doesn’t require a finance degree, a Bloomberg terminal, or a spreadsheet the size of a bedsheet. Graham built his reputation on a handful of simple, repeatable checks that any patient investor can run. What follows is a beginner’s version of that checklist: six questions to ask before you buy. To keep the math clean I’ll use one example company with rounded figures: a fictional-but-typical Canadian retailer trading at $60 a share. (Real numbers move daily, so when you do this for keeps, pull the current figures first.)

Price is what you pay; value is what you’re hunting for

Before the checks, one mindset shift. A $500 stock isn’t “expensive,” and a $5 stock isn’t “cheap.” Cheap and expensive only mean something relative to what you get: the earnings, the assets, and the safety behind the share. Every check below is really the same question asked five different ways: am I paying less than this business is worth?

Check 1: Is it cheap relative to its earnings? (the P/E)

The price-to-earnings ratio is the first thing to look at. Take the share price and divide by earnings per share (EPS). Our retailer earns $5 a share, so at $60 its P/E is 12.

Graham liked to see a P/E under 15. A P/E of 12 means you’re paying $12 for every $1 of annual profit: or, flipped around, an “earnings yield” of about 8%. That’s a reasonable starting point. Anything north of 25–30 means the market is pricing in a lot of future growth, and you’re paying today for profits that may or may not show up.

Check 2: Is it cheap relative to what it owns? (the P/B)

Earnings can be lumpy, so Graham cross-checked price against the company’s book value:  roughly, what would be left for shareholders if the company sold its assets and paid off its debts. Divide price by book value per share. Our company’s book value is $40 a share, so its price-to-book is 1.5.

Graham considered 1.5 a sensible ceiling for a defensive investor. Below 1 means you’re buying the assets for less than their stated worth: rare, and worth a closer look. Well above 3 means little of what you’re paying is backed by tangible assets; you’re buying expectations.

Check 3: Can it actually pay its bills? (interest coverage)

A cheap stock that can’t service its debt isn’t a bargain:  it’s a trap. Interest coverage tells you how comfortably a company covers its loan payments: take operating earnings (EBIT) and divide by annual interest expense. Our retailer covers its interest 8 times over.

As a rule of thumb, above 5x is comfortable, and below 2x is a flashing yellow light: a bad year could put the company in a squeeze. This one check quietly eliminates a lot of “value traps” that look cheap only because they’re fragile.

Check 4: How close is it to trouble? (the Altman Z-Score)

In the 1960s, professor Edward Altman combined five financial ratios into a single distress-predictor called the Z-Score. You don’t need to compute it by hand, but you should know how to read it:

Above 3.0 — financially healthy. 1.8 to 3.0 — a grey zone; tread carefully. Below 1.8 : elevated risk of serious financial distress.

Our example lands around 3.2: solid. The Z-Score is a wonderful “sniff test” precisely because it’s hard to fool: a company can dress up one ratio, but rarely all five at once.

Check 5: The rare, deep bargain (net-net / net current asset value)

This is Graham’s most famous trick, and his most demanding. Add up only a company’s current assets — cash, receivables, inventory — then subtract all its liabilities. Divide by shares outstanding. If the stock trades below that “net current asset value,” you’re theoretically buying the ongoing business for less than nothing. Continue Reading…

Covered Call ETFs: Why Total Return matters

High yield doesn’t equal better returns: Learn how covered call ETFs really work and why Total Return matters before you invest.

Getty Images, courtesy BMO

By Jimmy Xu, BMO Global Asset Management

(Sponsor Blog)

Covered call ETFs have become a popular solution for investors seeking cash flow, particularly in today’s uncertain market environment. With distribution yields that are often meaningfully higher than traditional equity ETFs, they can appear attractive at first glance.

But focusing on yield alone can be misleading.

To properly evaluate covered call ETFs, investors need to look beyond the potential yield and focus on Total Return: and understand how different strategies are implemented.

What are Covered Call ETFs?

Covered call ETFs generate returns by holding a portfolio of equities and selling call options1 on some or all of those holdings.

This strategy produces three sources of return:

  • Dividends
  • Net stock price appreciation from the equities held
  • Option premiums2 from the calls sold

In exchange for that additional return generated from the option premiums, investors give up some upside potential if markets rise strongly: because the ETF may cap some upside participation at predetermined prices.

The result is typically higher cash flow with lower volatility, but more muted upside in strong markets.

The problem with Focusing only on Yield

One of the biggest misconceptions about covered call ETFs is equating high yield with strong performance.

In reality, yield is only one component of return. What ultimately matters is Total Return: the combination of dividends, premiums and equity price appreciation.

A strategy that pays a 10% yield but delivers little or no equity capital growth may lag a lower-yielding strategy over time; investors may also experience the net asset value (NAV) decline over time as distributions erode the initial investment. Conversely, a covered call ETF that balances premium generation with participation in market upside can potentially deliver stronger total outcomes.

That’s why evaluating these ETFs requires a broader lens asking questions such as: how much upside is being sacrificed? How sustainable are the distributions? What is the long-term return profile?

BMO’s Covered Call Approach: A more active Framework

Not all covered call strategies are built the same. BMO’s approach differs in two key ways:

  1. Active Option Management

Rather than mechanically selling calls on a fixed percentage of the portfolio, BMO takes a more active approach: adjusting the following based on timing and market conditions:

  • The percentage of the portfolio covered
  • Strike price selection (how far “out of the money” calls are written)

This allows the strategy to balance cash flow generation with participation in equity upside, particularly during stronger markets.

  1. Partial Coverage vs. Fully Covered

Some covered call ETFs write options on nearly the entire portfolio, maximizing distributions but limiting growth potential.

BMO strategies uses a range of partial coverage, meaning a portion of the portfolio remains uncovered which preserves the ability to participate in rising markets while still generating cash flow.

Our June 2025 Enhancement

In June 2025, BMO refined its covered call approach to further emphasize potential total return outcomes.

While the specifics vary by ETF, the changes broadly reflected:

  • A more flexible coverage range, rather than static coverage targets
  • Greater emphasis on out-of-the-money3 call writing, allowing for more upside participation
  • A continued shift toward actively managing the trade-off between cash flow and potential growth

The goal was clear: move away from maximizing yield alone and toward delivering a more balanced cash flow & growth profile over time.

What Investors should Look for

When evaluating covered call ETFs, a few key considerations stand out: Continue Reading…

HDIV: All-In-One Canadian Income & Growth ETF Turns 5 years old

Hamilton ETFs

By Hamilton ETFs

(Sponsor Blog)

Last month marked the fifth anniversary of the launch of the Hamilton Enhanced Canadian Covered Call ETF (HDIV), Canada’s very first modestly levered (or “enhanced”) covered call ETF, and there are many reasons to celebrate this marriage of income and growth strategy.

The idea for HDIV was born out of one question: can covered call ETFs be improved? Designed to provide higher monthly income, covered call ETFs have been a rapidly growing segment of the ETF market for several years, but the reality is the strategy does cap your potential upside in exchange for the tax-efficient income it provides.

We thought of a game-changing way to help mitigate this yield/return trade-off: add modest 25% leverage to generate higher monthly income and participate in more upside growth potential.

HDIV Growth and Performance

HDIV has grown to assets under management (AUM) of ~$1.8 billion since inception in July 2021, making it our second-largest ETF after the Hamilton Canadian Financials YIELD MAXIMIZER™ ETF (HMAX).

HDIV’s growth in assets has been impressive, and the fund has also delivered strong performance. Since inception, HDIV has delivered an annualized total return of 19.3%, outperforming the S&P/TSX 60 and the S&P 500 index over the same period[1].

HDIV Performance Highlights:

  • Annualized total return (including dividends) of 19.3%, versus 15.2% for S&P/TSX 60 and 15.6% for S&P 500 (CAD).
  • Outperformed the S&P/TSX 60 in calendar years 2022, 2023, 2024 and 2025 by 3.7%, 1.8%, 2.1% and 4.7%, respectively[2].
  • 14 distribution increases for a total distribution increase of 64% since inception[3].
  • Attractive yield, currently 9.99% — versus 2.29% for S&P/TSX 60[4].


What does $100,000 invested in HDIV since day 1 look like?

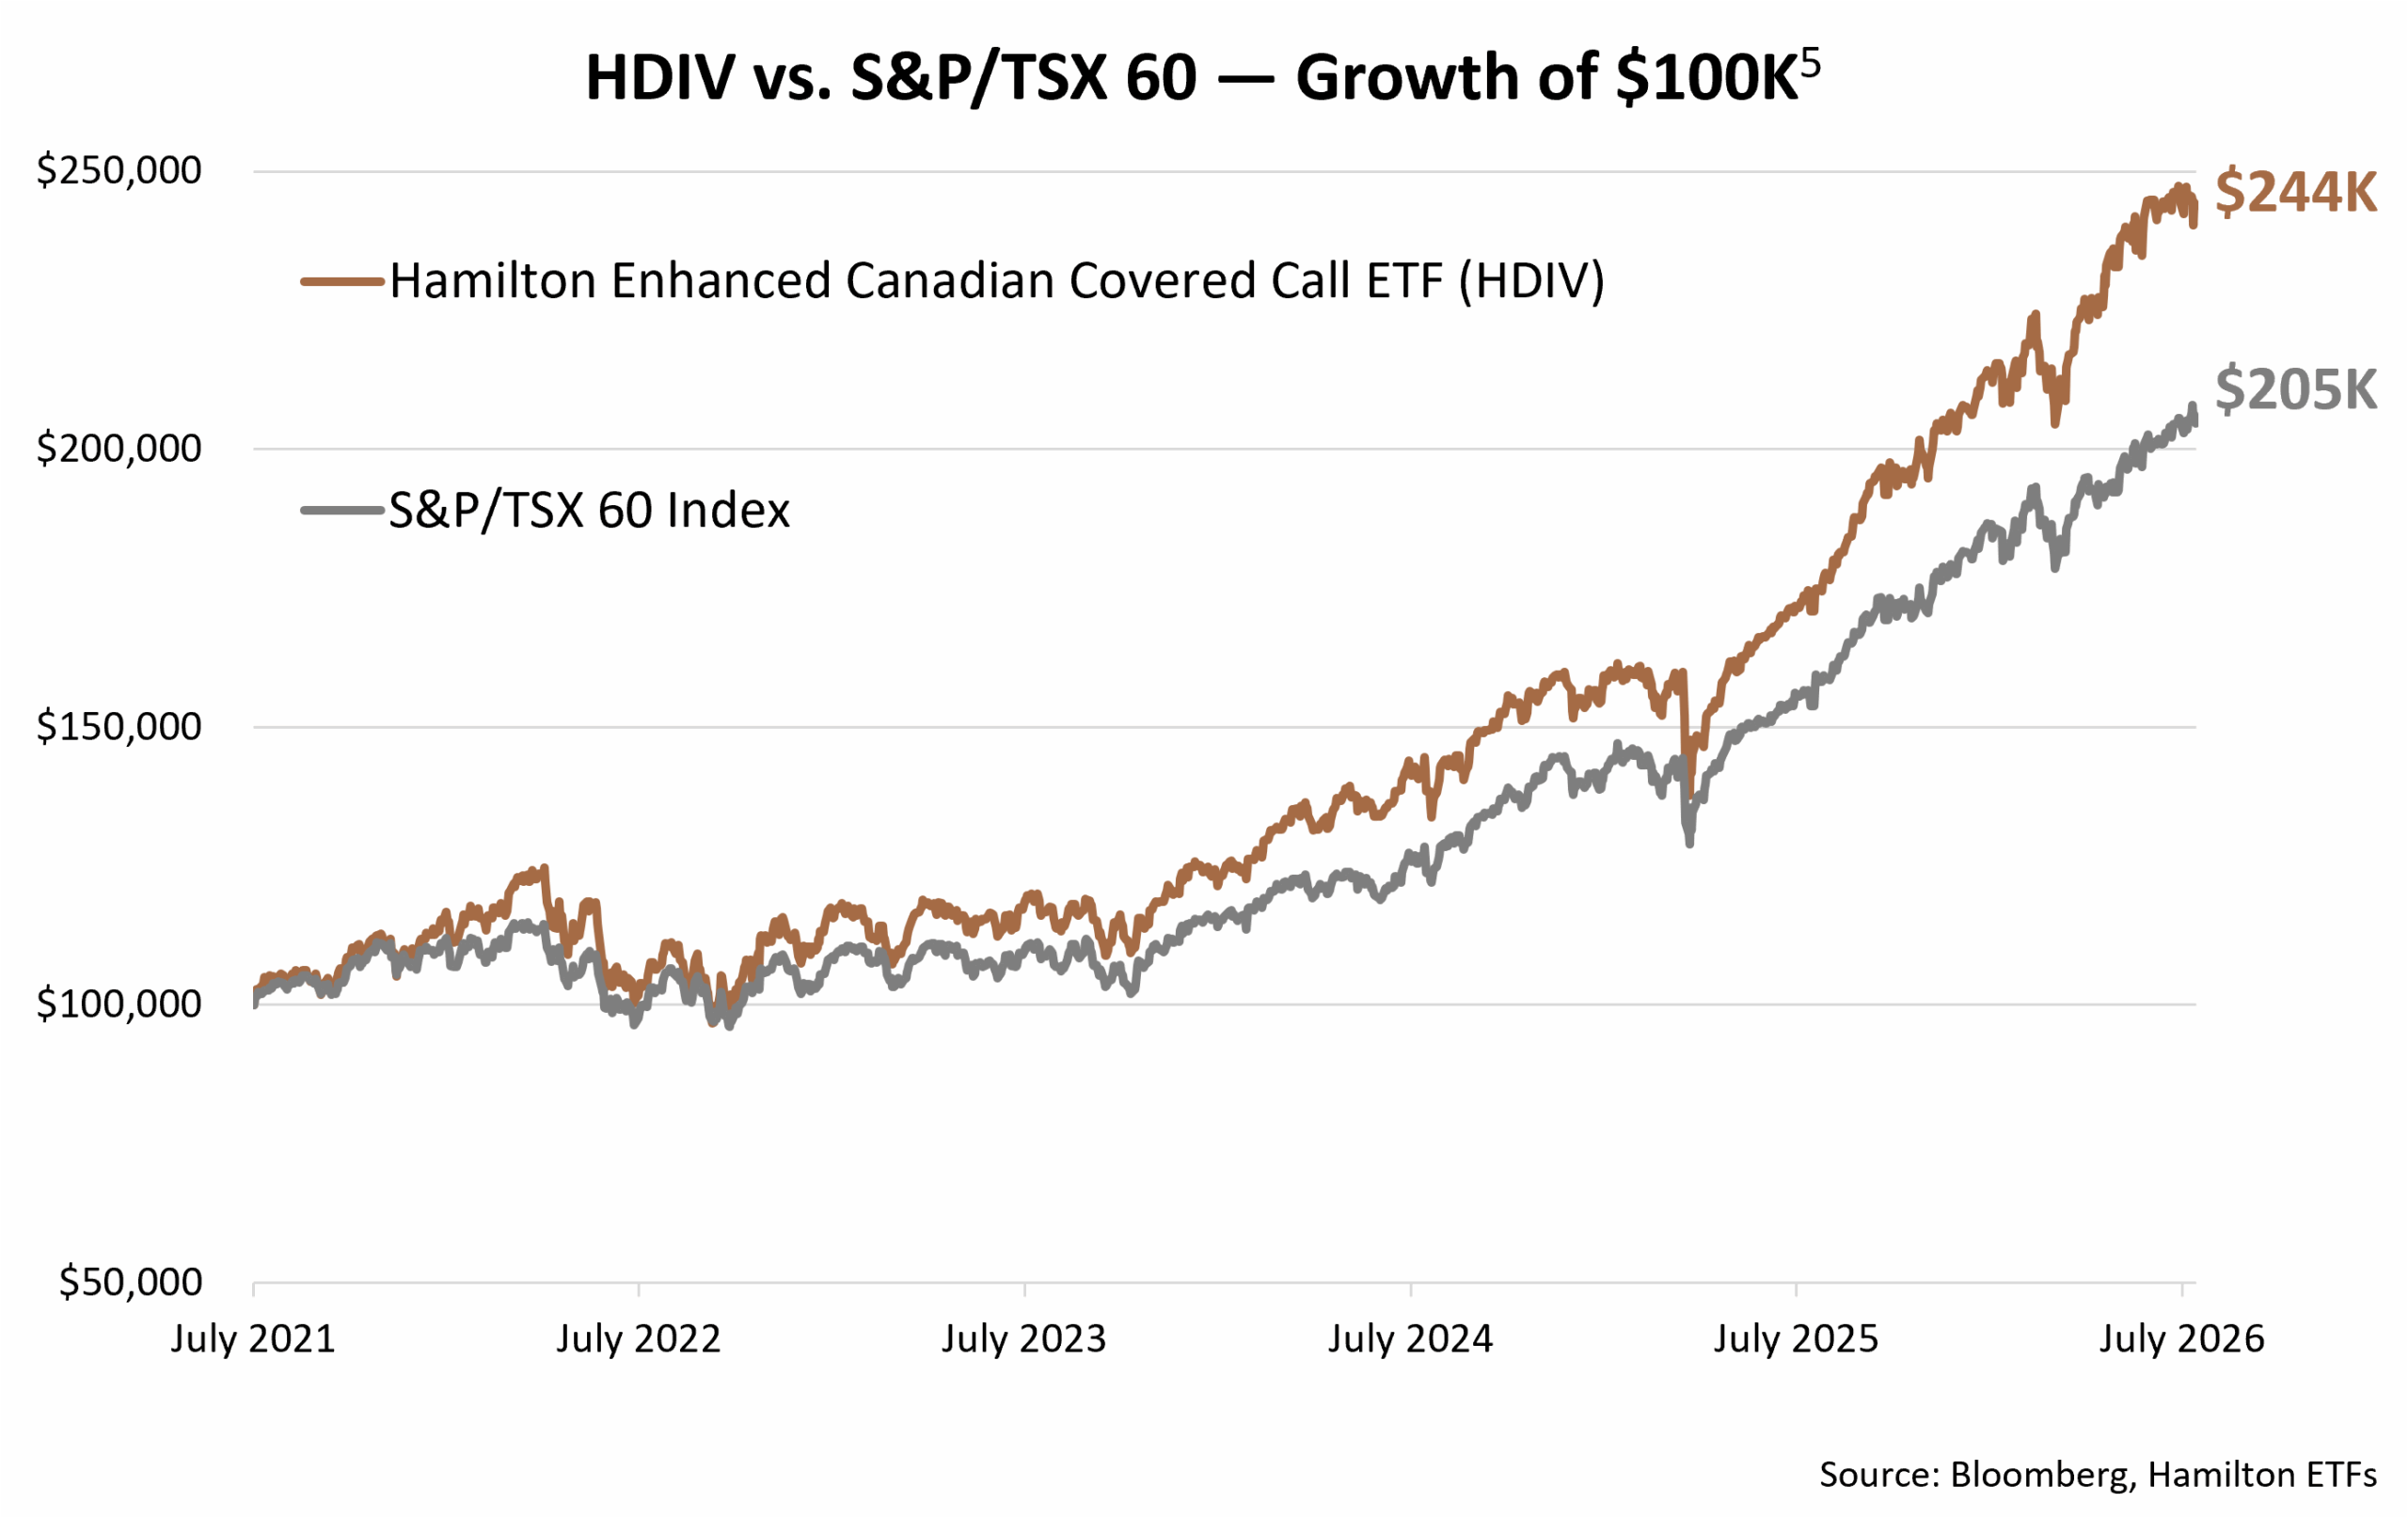
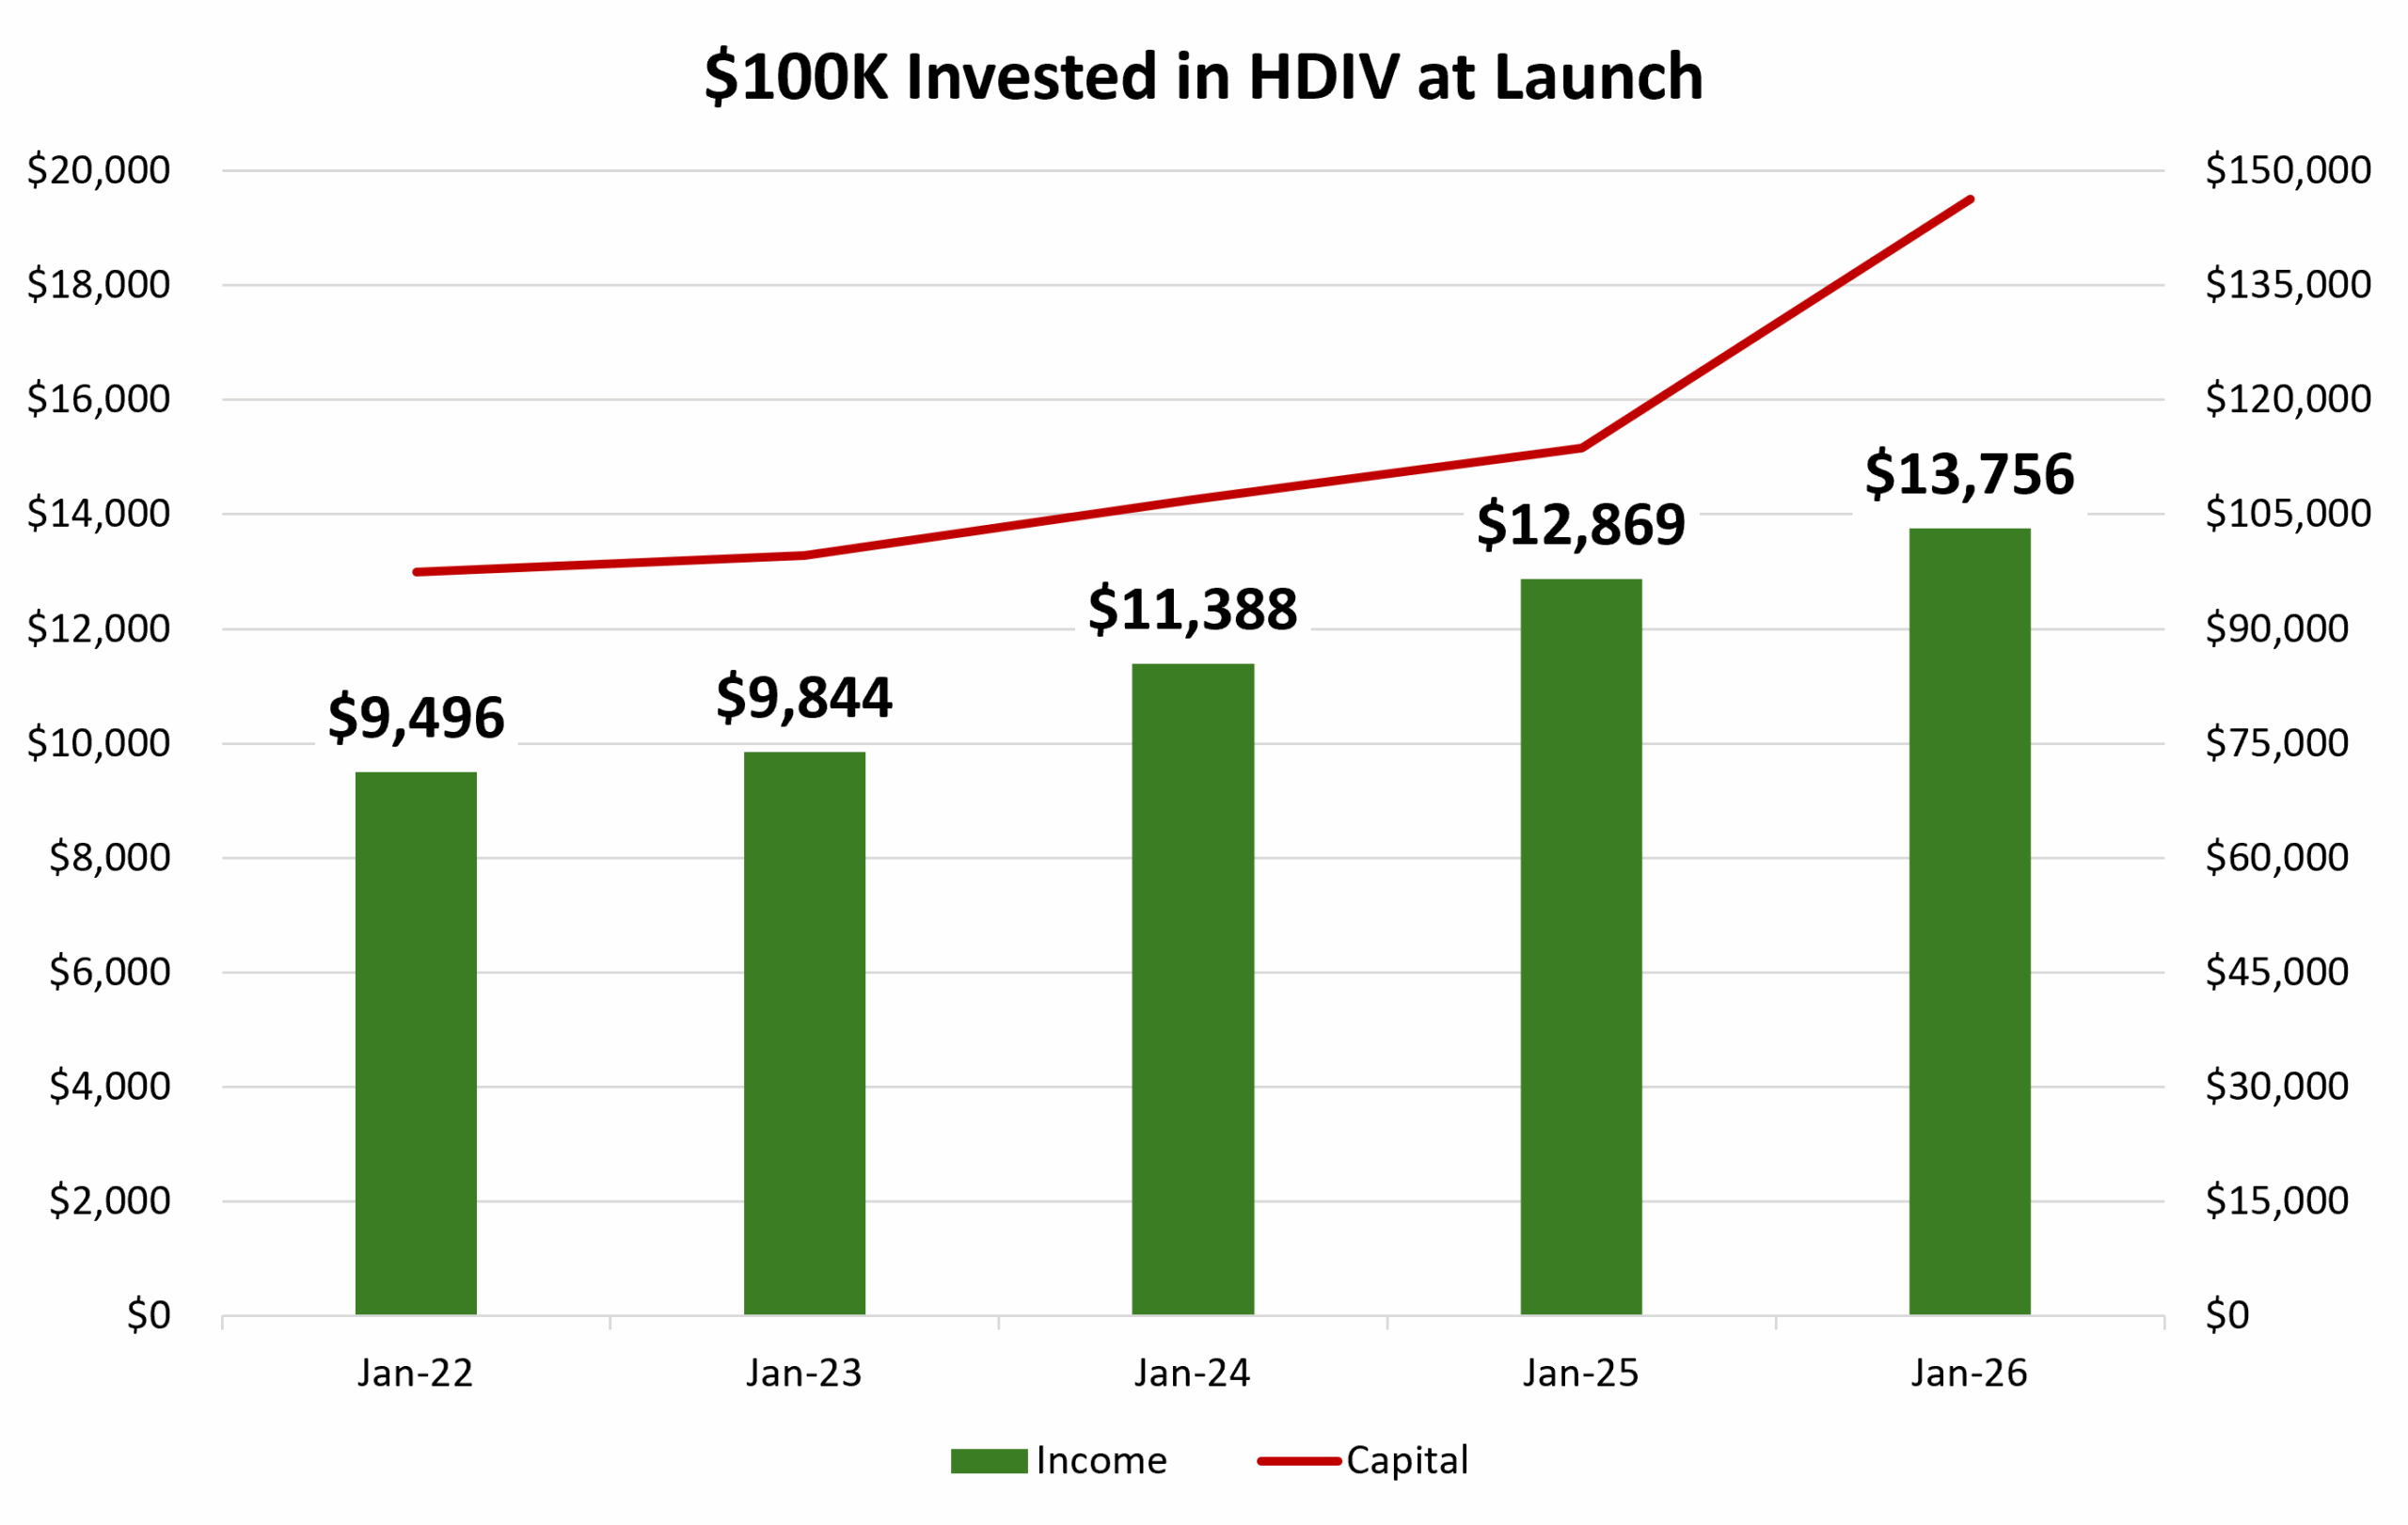
If you invested $100,000 in HDIV at launch, your investment would be $244,000 with reinvested distributions, as seen in the chart above. Assuming you did not reinvest your distributions, your invested capital grew from $100,000 to $144,875 and you received $56,950 in cash. The chart below shows your total annual income from HDIV and capital growth over five years. So you did not just receive cash flow; your capital appreciated as well.

What has driven HDIV’s performance?

Every aspect of our ETFs is carefully thought-out and tested with the intention that they be long-term responsible investments, and HDIV is no exception. Two structural features have been central to HDIV’s success: modest leverage and broad sector diversification.

Enhanced Structure

HDIV has an enhanced structure with modest leverage of 25%, achieved by borrowing at relatively lower institutional rates. How does this work? For every $100 you invest, HDIV borrows an additional $25, investing a total of $125 in its portfolio and amplifying the fund’s overall yield and growth potential.

Of course, investors should keep in mind that leverage can work both ways, amplifying growth during market rallies as well as losses during downturns. While leverage does add risk and volatility to your portfolio, HDIV only has a modest amount.

Broad Sector Diversification with Blue-Chip Holdings

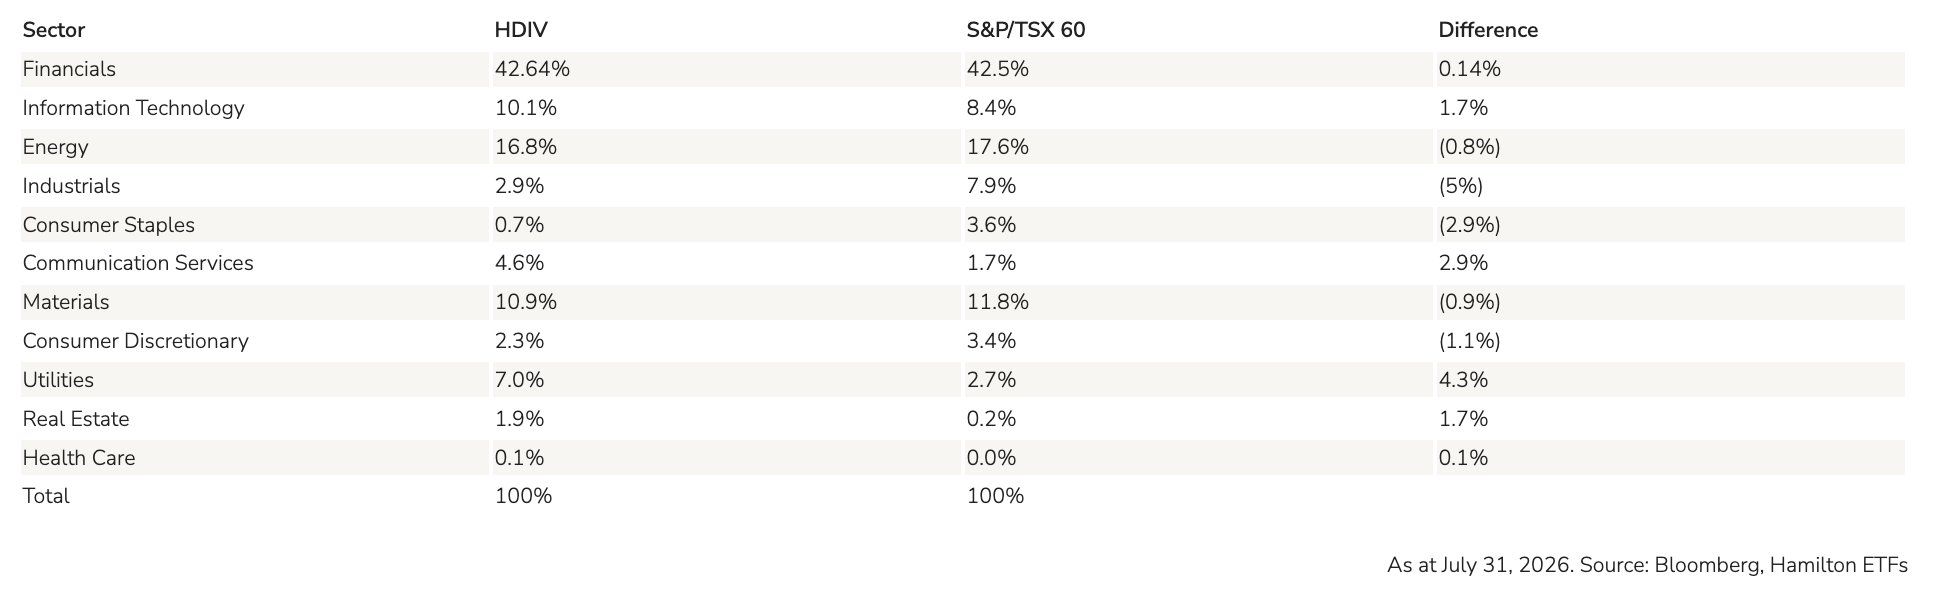
HDIV is an ETF made up of 10 sector-focused, blue-chip covered call ETFs from our YIELD MAXIMIZER™, Enhanced Growth and DayMAX™ suites. Their weightings have been chosen with the aim of giving HDIV a sector mix broadly similar to that of the S&P/TSX 60.

HDIV’s focus on high-quality stocks is clear when you examine its underlying holdings, which are primarily leading large-cap companies with strong fundamentals. Around 44% of HDIV’s underlying holdings are the largest Canadian financial stocks like the Big Six banks and Canada’s largest insurance company by total assets, Manulife Financial[6]. Energy and technology giants account for over 30% of the fund[7].


We also believe HDIV’s underlying holdings are an improvement in the breadth of the S&P/TSX 60 index. Certain Canadian sectors, like energy and technology, are heavily concentrated in a very small number of large-cap stocks. HDIV addresses this lack of diversification by including leading U.S. companies. For example, HDIV holds market leaders like Apple and Microsoft through the Hamilton Technology YIELD MAXIMIZERTM ETF (QMAX) and the Hamilton Enhanced Technology DayMAXTM ETF (QDAY).

The Hamilton ETFs advantage with covered call strategies

As a member of the Hamilton ETFs line-up, HDIV’s underlying covered call strategy is managed by our options team, which has 60+ years of combined experience and is led by Chief Options Strategist Nick Piquard.

Five years in

Five years after HDIV’s launch, we believe the results provide a tangible answer to our original question: can covered call ETFs be improved? HDIV has paired strong total returns with growing monthly distributions and broad diversification, clearly resonating with investors who have helped grow the ETF to more than $1.8 billion in assets. Its first five years have, in our view, demonstrated how an enhanced covered call structure can combine capital growth with a stream of monthly income.

Trivia

The AI investment boom is so big, it’s reshaping economies. What 19th century technological breakthrough triggered an even greater U.S capital spending spree (as a percentage of GDP)?

Hint: The two biggest holdings in Hamilton Utilities YIELD MAXIMIZER™ ETF (UMAX) are involved in this industry.

Answer: Railways.

Disclaimer

Certain statements contained in this article may constitute forward-looking information within the meaning of Canadian securities laws. Forward-looking information may relate to a future outlook and anticipated distributions, events or results and may include statements regarding future financial performance. In some cases, forward-looking information can be identified by terms such as “may”, “will”, “should”, “expect”, “anticipate”, “believe”, “intend” or other similar expressions concerning matters that are not historical facts. Actual results may vary from such forward-looking information. Hamilton ETFs undertakes no obligation to update publicly or otherwise revise any forward-looking statement whether as a result of new information, future events or other such factors which affect this information, except as required by law.

The S&P 500 Index and the S&P/TSX 60 Index (“Indices”) and associated data are a product of S&P Dow Jones Indices LLC, its affiliates and/or their licensors and have been licensed for use by Hamilton ETFs © 2026 S&P Dow Jones Indices LLC, its affiliates and/or their licensors. All rights reserved. Redistribution or reproduction in whole or in part are prohibited without written permission of S&P Dow Jones Indices LLC. For more information on any of S&P Dow Jones Indices LLC’s indices, please visit www.spdji.com. S&P® is a registered trademark of Standard & Poor’s Financial Services LLC (“SPFS”) and Dow Jones® is a registered trademark of Dow Jones Trademark Holdings LLC (“Dow Jones”). Neither S&P Dow Jones Indices LLC, SPFS, Dow Jones, their affiliates nor their licensors (“S&P DJI”) make any representation or warranty, express or implied, as to the ability of any index to accurately represent the asset class or market sector that it purports to represent and S&P DJI shall have no liability for any errors, omissions, or interruptions of any index or the data included therein.

Commissions, management fees and expenses all may be associated with investments in exchange traded funds (ETFs) managed by Hamilton ETFs. Please read the prospectus before investing. The indicated rates of return are the historical annual compounded total returns including changes in per unit value and reinvestment of all dividends or distributions and does not take into account sales, redemptions, distribution or optional charges or income taxes payable by any securityholder that would have reduced returns. Only the returns for periods of one year or greater are annualized returns. ETFs are not guaranteed, their values change frequently, and past performance may not be repeated.


[1] Based on total annualized returns since inception on July 19, 2021. As at July 31, 2026. Source: Bloomberg

[2] Source: Bloomberg

[3] Distributions are not guaranteed, may fluctuate and are subject to change and/or elimination.

[4] Current annualized yields as at July 31, 2026. The yield calculation excludes any additional year end distributions and does not include reinvested distributions. Source: Bloomberg, Hamilton ETFs.

[5] Source: Solactive AG, Bloomberg, Hamilton ETFs. Data from July 19, 2021 to July 31, 2026.

The graph illustrates the growth of an initial investment of $100,000 in HDIV vs the S&P/TSX 60 Index with annual compounded total returns. The graph is for illustrative purposes only and is intended to demonstrate the historical impact of the compound growth rate. It is not a projection of future performance, nor does it reflect potential returns on investments in HDIV. Investors cannot directly invest in the index. All performance data assumes reinvestment of distributions and excludes management fees, transaction costs, and other expenses which would have impacted an investor’s returns.

[6] As at July 31, 2026

[7] As at July 31, 2026


Implementing the FIRE Approach to Car Ownership

Pexels: Melvin CJ

By Dan Parks

Special to Financial Independence Hub

Transportation is a necessary expense, but it’s also one of the highest ongoing costs for many households.

If you’re pursuing Financial Independence, Retire Early (FIRE), choosing the right car is only part of the equation. The way you buy, finance and own your car can also affect how much money you have available to invest.

Here are ways to apply FIRE principles to car ownership without sacrificing reliability or everyday convenience.

Start with the Total Cost of Ownership

A low monthly payment doesn’t necessarily mean you’ve found the right car for your FIRE plan. Instead of focusing on what fits your budget today, think about what the vehicle will cost over the entire time you expect to own it. You’ll want to look outside of the purchase price and estimate the expenses you’ll face throughout ownership.

According to AAA’s 2025 study, the average cost of owning a new vehicle driven 75,000 miles over five years is $11,577 per year, or about $965 each month. That estimate includes:

  • Financing
  • Depreciation
  • Fuel
  • Insurance
  • License, registration and taxes
  • Maintenance, repair and tires

Depending on your situation, you may also want to account for parking, tolls, accessories, home charging equipment for an Electric Vehicle or any upgrades you plan to make after purchase. Looking at the full cost of ownership gives you a stronger basis for comparing vehicles. A car with a higher purchase price may still cost less to own over time if it holds value well, uses less fuel and requires fewer repairs.

Buy a Car that serves your Purposes

Once you know what you can comfortably afford, choose a vehicle that fits your everyday life. Think about your commute, the number of passengers you usually carry, local weather and road conditions and any work or family responsibilities your car needs to handle. It’s also important to keep reliability in mind, since a well-built car can help you avoid unexpected repair costs and stay on the road for many years.

As your income grows, your vehicle budget may grow too. Before committing to a more expensive model, consider how it fits with your long-term FIRE goals. Many people in the movement use the Rule of 25, which estimates the amount needed for retirement based on annual spending and a 4% maximum portfolio withdrawal rate. Many also aim to withdraw only 3% to 4% of their savings each year, adjusted for inflation.

Every recurring expense influences that calculation, so choosing a reliable vehicle with reasonable ownership costs can help you stay on track and enjoy dependable transportation.

Treat Financing as a Financial Decision

How you pay for your car deserves the same careful thought as choosing the vehicle itself. If paying cash still leaves you with a healthy emergency fund and keeps your investment goals on track, you can avoid interest charges altogether. Financing can also fit your FIRE plan if it helps you manage your cash flow and supports your long-term financial priorities.

If you decide to apply for a loan, check your credit score and credit history. Lenders commonly group borrowers into FICO score tiers. Generally, a score of 670 or higher is considered good, and a better credit profile can help you qualify for a lower interest rate. That can reduce the total amount you repay over the life of the loan, giving you more money to invest. When comparing lenders, evaluate the interest rate, loan term and total repayment amount so you understand the full cost of borrowing.

Maximize the Value of every year you own the Car

A car becomes more valuable to your FIRE journey as it continues to serve you reliably. Extending its lifespan allows you to spread the purchase price and depreciation across more years. This helps you reduce your average transportation costs over time. For many people, keeping a well-maintained vehicle longer can free up money that would otherwise be used for another large purchase.

Reaching that point takes consistent care, though. You need to follow the manufacturer’s service schedule, replace worn parts before they fail and address small issues promptly to help your car stay dependable. A modern car from a brand with a good reputation for reliability may reach 200,000 miles or more when serviced according to the recommended intervals. You can also reduce ongoing costs by reviewing your insurance each year, comparing quotes and adjusting your coverage when your circumstances change.

Review Car Ownership like any other Investment Decision

Your car shouldn’t stay on autopilot after you buy it. Just as you review your portfolio from time to time, your vehicle deserves a regular financial check-in to make sure it still supports your FIRE goals. So, once a year, look outside routine expenses and assess the bigger picture. Analyze how much you’re spending on fuel, insurance, maintenance and repairs, then ask whether your current vehicle still matches your lifestyle.

A longer commute, a growing family or changes to your work could all influence what you need from a car. Plus, increasing repair bills or declining reliability may suggest it’s time to explore another option. Making these evaluations regularly helps you avoid costly decisions driven by habit or impulse. Regular reviews also help ensure your transportation costs continue supporting your long-term goals.

Driving toward Financial Independence

Implementing the FIRE approach to car ownership begins before you receive the keys and continues throughout the vehicle’s life. Always look at the total ownership costs, choose a car that fits your needs, finance carefully and review your expenses regularly so that you can keep transportation costs aligned with your financial goals. Those intentional decisions can free up more money to invest and bring Financial Independence within closer reach.

Dan Parks is a senior writer at Modded.com. Based in Washington, D.C., Dan has a proven track record of distilling complex subjects into accessible narratives across various fields. His expertise in clear communication and meticulous research makes him a valuable contributor to discussions on personal finance and investment strategy, helping readers navigate intricate topics with ease. Dan is dedicated to providing readers with well-researched insights to foster financial literacy and independence.