Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Bad Retirement Spending Plans

Image courtesy Pexels/Feyza Nur Demirci

By Michael J. Wiener

Special to Financial Independence Hub

A recent research paper by Chen and Munnell from Boston College asks the important question “Do Retirees Want Constant, Increasing, or Decreasing Consumption?”  The accepted wisdom until recently was that retirees naturally want to spend less as they age.  This new research challenges this conclusion.

What we all agree on is that the average retiree spends less each year (adjusted for inflation) over the course of retirement.  However, averages can hide a lot of information.  The debate is whether this decreasing spending is voluntary or not.  However, it’s important to recognize that the answer is different for each retiree.  Some don’t spend less over time, some spend less voluntarily, and some are forced to spend less as their savings dwindle.

I’ve been saying for some time that not all spending reductions by retirees are voluntary and that this affects the average spending levels across all retirees.  I’ve discussed this subject with many people, including a good discussion with Benjamin Felix, who was good enough to point me to the new Chen and Munnel research.  (Larry Swedroe also discussed this research.)

Research Findings

“On average, household consumption declines about 0.7-0.8 percent a year over retirement.  However, consumption for wealthy and healthy households is virtually flat, declining only 0.3 percent a year over their retirement.  Thus, at least in part, wealth and health constraints help explain the observed pattern of declining consumption.”

“Retirees likely prefer to enjoy constant consumption in retirement.  The results suggest that a retirement saving shortfall exists since consumption declines are larger for households without assets.”

Resistance

Some commentators want to believe that it is safe to assume declining spending in a retiree’s financial plan.  They dismiss involuntary reductions in observed retirement spending as insignificant.  However, this new research makes it clear that retirees’ preferred spending levels are much flatter than the observed spending data.  (For the record, Ben Felix says he assumes flat inflation-adjusted spending in his clients’ retirement plans.)

The idea that we’ll want to spend less as we age is seductive; it means we don’t have to save as much for retirement, can retire earlier, and can safely overspend in early retirement.  What’s not to like?  The problem is that average retirement spending data shows spending declines right from the first years of retirement.  Does it make sense that people still in their 60s suddenly want to just sit around inside their homes?  It’s plausible that retirees tend to become homebodies deep into their retirements, but not in the early years. Continue Reading…

Vanguard Home Bias study says Canadians should raise global stock exposure to 70%

Vanguard Canada has released an interesting study on home country bias around the world, and makes the familiar case that most Canadian investors are woefully overweight Canadian equities and underweight the rest of the world. You can find the full report (PDF), by clicking here.

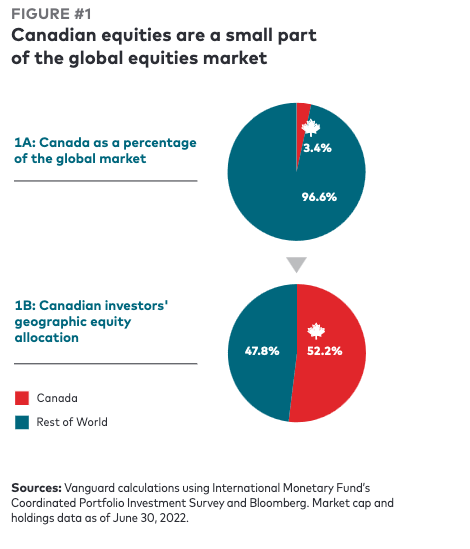
The report is written by Bilal Hasanjee, CFA®, MBA, MSc Finance, Senior Investment Strategist for Vanguard Investments Canada. He points out that Canadian stocks account for only 3.4% of the total global stock market as of June 30, 2022, but as the chart to the left shows, the average Canadian investor is more than 50% in domestic (Canadian) equities. That’s a whopping overweight position of 15 times!

“There are good reasons to have some overweight to Canada for domestic investors, including future return differentials, preference for the familiar, favourable tax considerations, the need to hedge domestic liabilities and currency risk,” writes Hasanjee, “However, Vanguard believes the optimal asset allocation for Canadian investors is 30% vs 70% allocation to Canadian versus international equities, based on our research …”

In other words, it’s okay to be overweight Canada by a factor of nine (30% versus 3.4) but most of us still need to boost our foreign content by roughly 50%: from 47.8% to 70%.

Home Country bias is hardly unique to Canada

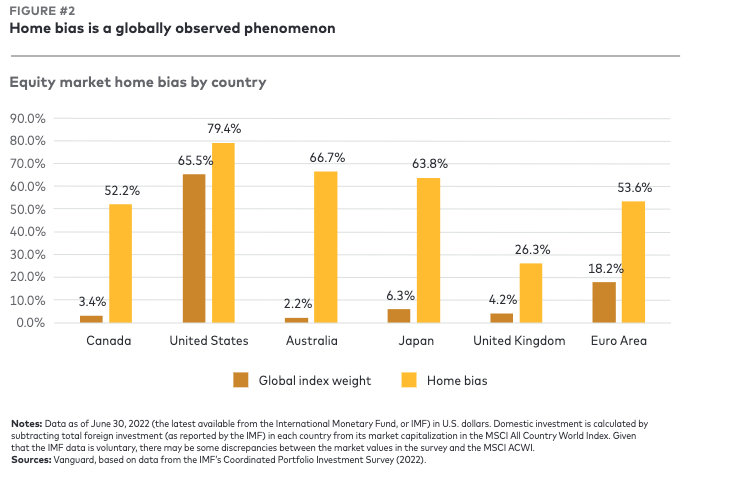
Home country bias is hardly unique to Canada, the report says: it’s certainly the case in the United States and many developed countries, as Figure 2 demonstrates:

Americans are also overweight their home market —  the United States — but they can get away with it, as more than half the global market capitalization is in American stocks, plus many of those are blue-chip corporations that have the world as their market. If anything, Interestingly you can see from the above that Australia, which is similar to the Canadian stock market in being focused mostly on energy/resources and financials, suffers even more than Canada from home country bias. Continue Reading…

TIARA: There Is a Real Alternative

Designed Wealth Management

By John De Goey, CFP, CIM

Special to the Financial Independence Hub

By now, you’ve likely heard the term FOMO: the Fear of Missing Out.  You’ve likely also heard the term TINA: There Is No Alternative.

Taken together, these handy little pop culture acronyms explain a good deal of what has gone on in capital markets over the past three years or so. I’d like to take this opportunity to push back a little on the second one.  Based on current valuations, there may not be a sensible alternative to stocks, bonds, and real estate, but there may well be an alternative in …. wait for it…. alternatives.

Alternative assets are varied and the term ‘alternative’ could mean different things to different people. The asset class is known on a non-correlated basis by offering opportunities in such varied assets as infrastructure, liquid alternatives, structured notes, and hedge funds.  While I personally dislike the last option due to high fees, illiquidity, and opaque reporting, depending on client objectives and risk tolerance, I believe there’s often a strong case that can be made for adding alternatives to your portfolio.  As such, here’s a new term: TIARA. It stands for: There Is A Real Alternative.  You’re not stuck with having to only choose between some combination of stocks and bonds. [Editor’s Note: John De Goey coined this term.]

A third major Asset Class

In the past half decade or so, many more traditional asset allocation strategies have changed significantly as bond yields have declined.   The asset class that has been gaining the most traction is alternatives. Continue Reading…

Should you Dump your All-Equity ETF?

By Justin Bender, CFA, CFP  

Special to Financial Independence Hub

In our last blog/video, we introduced the all-equity ETFs from iShares and Vanguard. These ETFs make it easy to gain and maintain exposure to global stock markets with the click of a mouse, eliminating the hassle of juggling several ETFs in your all-equity portfolio.

Vanguard and iShares don’t offer their services for free though.

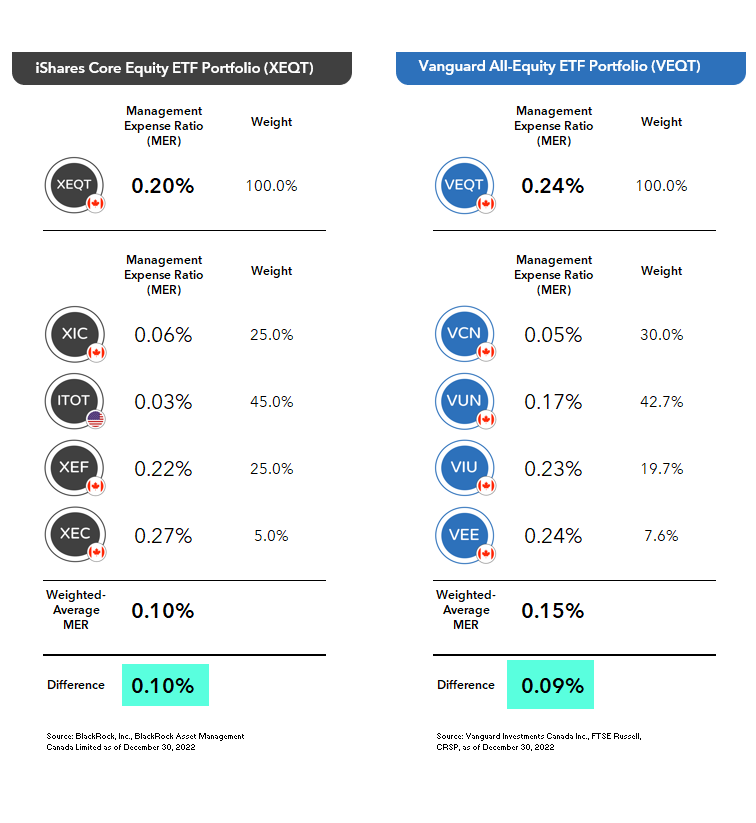
The MERs for their all-equity ETFs are slightly higher than the weighted-average MERs of their underlying holdings. Consider this modest surcharge as the price of admission for their professional asset allocation and rebalancing services. In my opinion, that’s a bargain for most investors.


Then again, there are those who might prefer to squeeze every last penny out of their portfolio costs. If that’s you, you may want to try skipping the value-add of an all-equity ETF, and simply purchase the underlying ETFs directly, in similar weights. If you take on the task of rebalancing back to your targets each month when you add new money to your portfolio, you should be able to mimic an all-equity ETF for a lower overall MER.

That’s the goal anyway. But it’s still going to take time, money, or both to keep your asset allocations on track each month. Let’s look at three potential strikes against trying to reinvent an all-equity ETF on your own, as well as one potential play that may serve as a suitable compromise.

Strike One: The potential cost savings are minimal.

For example, let’s say you’ve got $10,000 to invest. Instead of investing it in the Vanguard All-Equity ETF Portfolio, or VEQT, you could divide it up among VEQT’s component funds. The estimated cost savings might let you rent an extra movie each year, but are the savings really worth it? The extra time you’ll need to spend on rebalancing may not leave you much time to even enjoy your movie.

For larger amounts, the fee savings start adding up, but only if you can buy and sell ETF shares at zero commission as you rebalance. If not, you can forget about it.

Strike Two: Managing a portfolio of four ETFs (instead of just one) will be more difficult.

Sticking with our VEQT example, a DIY investor would either need to visit Vanguard’s website monthly to collect the individual ETF weights within VEQT, or use the market cap data from the FTSE and CRSP index fact sheets to determine how to allocate each of the underlying ETFs. They would then need to calculate how many ETF units to buy or sell across various accounts to get their portfolio back on target, and place multiple trades to get the job done. Continue Reading…

Canadians losing confidence in Retirement plans and stressed about running out of money

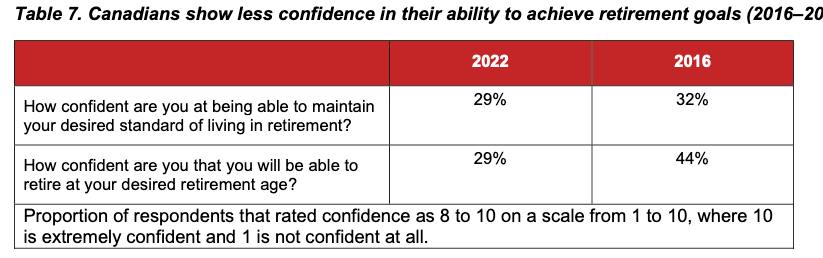
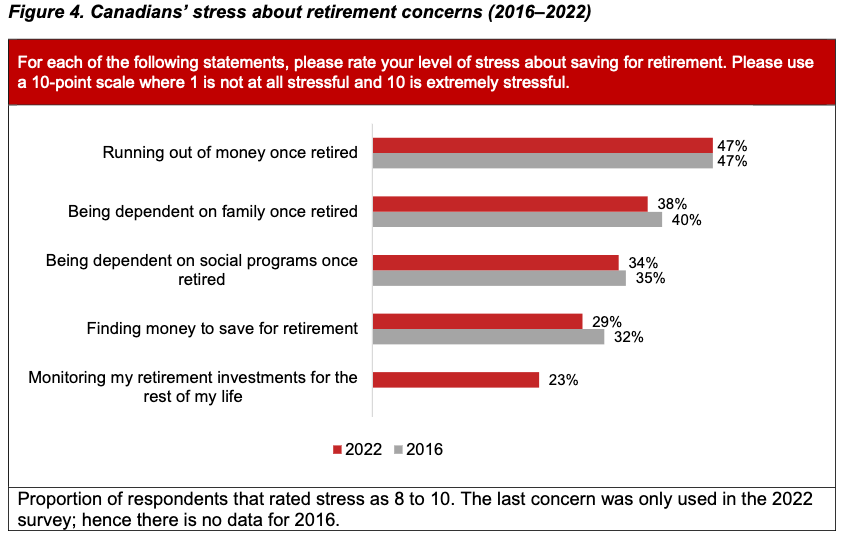
Canadians have lost confidence in their ability to retire on time and debt-free, according to a new report by the Canadian Public Pension Leadership Council (CPPLC). As a result, almost half of those polled by Pollara Strategic Insights are stressed about the prospect of running out of money in Retirement, as the graphic from the report illustrates below:

You can find the full report, which runs roughly 40 pages, by clicking on its highlighted title here: The Pensions Canadians Want: Perceptions of Retirement (2016–2022).

A press release issued Monday says the report comes from a Canada-wide survey conducted in 2022 similar to an earlier survey by the CPPLC on retirement perceptions prepared in 2016.

An introduction recaps the three major pillars of the Canadian retirement income system: government-sponsored CPP/OAS/GIS; Workplace Retirement Plans and Personal Savings (primarily RRSPs/TFSAs/non-registered savings).

However, a minority of Canadians currently have access to the workplace pension plans of Pillar 2: only 39.7% as of 2021, according to Statistics Canada. Worse, Pillar 3 savings are not making up for that gap: the report cites a Bank of Montreal finding that the average RRSP account balance is $144,613. That is not enough to fund an average yearly spending level of $64,000 (2019 average) over a retirement that may last 20 or 30 years. It also finds that not everyone is using TFSAs: those who do tend to older and married, with higher incomes and education.

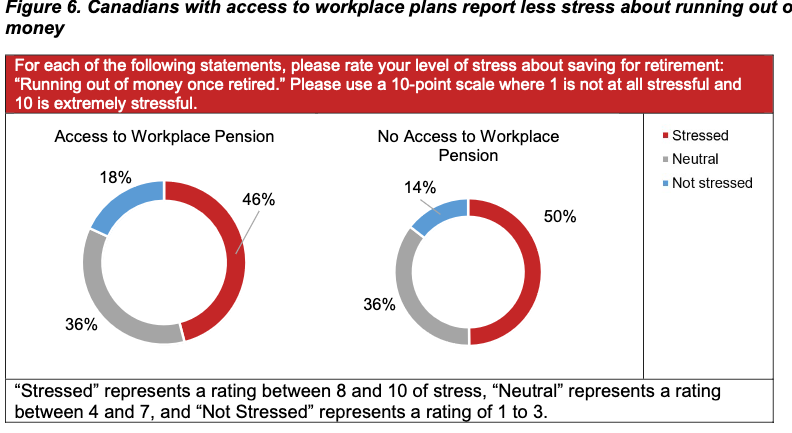
As you can see from the graphic on the right, those with Employer Pensions (especially classic Defined Benefit plans) experience somewhat less stress than those who do not. (Actually, I’m surprised the gap isn’t wider!).

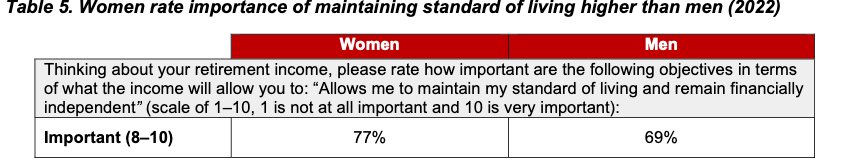
As you might expect, given that they tend to live longer, women are more stressed than men about running out of money: a majority (53%) are stressed about running out of money once retired, compared to 41% of men.

Women also report more uncertainty about managing retirement savings themselves. And they rate the importance of maintaining standard of living higher than men, as shown in the graphic below:

Four key Observations

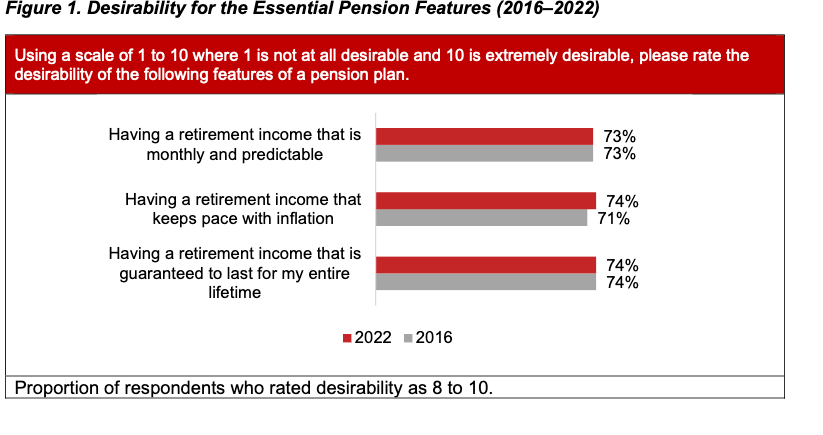
1.) Canadians consistently show preferences for predictable, inflation-adjusted, and lifetime
guaranteed retirement income

2.) Canadians continue to place importance on maintaining their standard of living in retirement

3.) Fewer Canadians are confident about managing their savings or that they will reach their
objectives and retire when they want

4.) Canadians are less confident they will be debt free in retirement and continue to report low
knowledge of retirement income sources

Three major recommendations

1.) Increase access to collective plans: leverage homegrown expertise to increase participation in
workplace pension plans by encouraging the growth of sector- and broader-based public sector
plans. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.