Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Mortgage Brokers vs. Banks: Which is better?

By Alyssa Furtado, RateHub.ca

Special to the Financial Independence Hub

Shopping for a mortgage can be a challenging task. Much like when you buy a car, it can be hard to get clear information. Mortgage rate comparison websites like RateHub.ca can help you learn about your options in general terms. But when it actually comes time to apply, a mortgage agent can give you objective advice and get you the best mortgage rate.

Canadians have two main options when looking for a mortgage: banks and mortgage brokers. When you talk to a mortgage advisor at a bank, you have the ability to negotiate directly with someone at that financial institution. When you work with a mortgage broker, he or she will work with a number of different lenders and negotiate on your behalf.

These are two different approaches to the same thing. But which option is better?

Each has benefits and drawbacks

To answer this question, we need to dive in to the benefits and drawbacks of each. Let’s start at the bank.

When looking for a mortgage, you can expect the mortgage advisor to be quick and responsive. You’ll have the option of convenient face-to-face meetings, and many banks even have mobile salespeople who will come to your home to discuss your mortgage needs. Continue Reading…
6 ways to attract Millennial homebuyers

By Emma Bailey

Special to the Financial Independence Hub

Millennials may eschew many traditional values, but members of this demographic remain committed to one primary tenet of the “American Dream” — homeownership.

While a large number of young people have put the brakes on buying a new home because of student-loan debt, mortgage restrictions and a sluggish job market, the largest bunch since the baby-boomer generation is beginning to enter the real estate market en force. The sheer size of this group and the fact they were born and came of age in an era of rapid technological innovation puts them in a position to transform both the real estate market and what is desirable in a home.

To keep pace, real estate agents and home sellers alike are having to alter the way they market and present homes in order to attract millennial homebuyers. Does your property have what it takes for millennials to take notice?

Walkability and Amenities

The millennial generation places a higher value on “experiences” than they do on material goods. In this demographic, a home is typically perceived as a base for the rest of one’s life, rather than the center of it. Instead of a classic house in the suburbs with a white picket fence, millennials are more likely to prefer property in an urban setting within walking distance of local attractions. There is also a larger interest in non-traditional and mixed-use properties, such as warehouses that have been converted into lofts.

Convenience

In an effort to save money and reduce their ecological impact, many millennials are forgoing cars in favor of alternative transportation. As a result, millennial buyers tend to prefer home shopping in locations that have easy access to public transportation and a minimal commute to work. If your property is close to a metro system or even a local bike-share hub, you can expect younger individuals to reach out with interest.

Connectivity

Continue Reading…

3 common mistakes by first-time homebuyers & how to avoid them

By Sean Cooper

Special to the Financial Independence Hub

You’ve probably heard it plenty of times: buying a home is the single biggest financial transaction of your lifetime. But purchasing a home can also be a great long-term investment — when it’s done right.

Buying a home for the first time can either set you on the right financial path or be a drain on your finances. It completely depends on how you go about it, and is why time is well spent reading great resources, such as the LowestRates.ca first-time homebuyer’s guide.

I wrote about the most common mistakes first-time homebuyers make in my new book, Burn Your Mortgage. Here are some highlights:

1.) Buying “Too Much” House

The simplest way to eventually be mortgage-free is to not take on a massive mortgage. The lower your mortgage, the less time it takes to pay off.

Getting pre-approved for a mortgage tells you how much home you can afford. But just because the bank says you can spend up to $800,000 on a home doesn’t mean you should. The word “can” is key here, and is what many homebuyers overlook. You don’t want to spend so much on a home that it’s a drag on your finances. Otherwise you could find yourself “house rich, cash poor,” with little money to save, let alone have fun with. Instead of your castle, your home could feel like a prison, with your mortgage a life sentence. By buying a home you can comfortably afford you maintain the financial wiggle room to deal with a financial emergency, such as losing your job or suffering severe damage to your home.

2.) Forgetting to Budget for Closing Costs

Closing costs are referred to as the transactional cost of real estate and are often overlooked by homebuyers. They’re anything but a drop in the bucket though, typically adding up to between 1.5% and 4% of a home’s purchase price. Common closing costs include home inspection, real estate lawyer fees, land transfer tax and appraisal fees.

Continue Reading…

Choosing between Income Protection Insurance and a Savings Account

By Cathy Habas

Special to the Financial Independence Hub

If you became seriously sick or injured today, would you be able to afford all your bills? Think about not only your medical expenses, but also your monthly payments: utilities, mortgage, car, insurance, loan repayment, etc.

Health insurance might pay for your hospital bills, but if you’re unable to work for an extended period of time, would you feel the pain of lost income?

Most of us certainly would. Fortunately, income protection insurance is designed to help us carry on without too much disruption.

What Is Income Protection Insurance?

In exchange for a monthly premium, you get peace of mind through income protection insurance. If you were unable to work due to an injury or illness, income protection insurance essentially replaces your income.

Specific details will depend on each policy, but in general you can expect to claim your income protection insurance more than once. That means you can benefit from the payouts any time you get sick or injured, and not just the first time you experience a major setback.

Continue Reading…

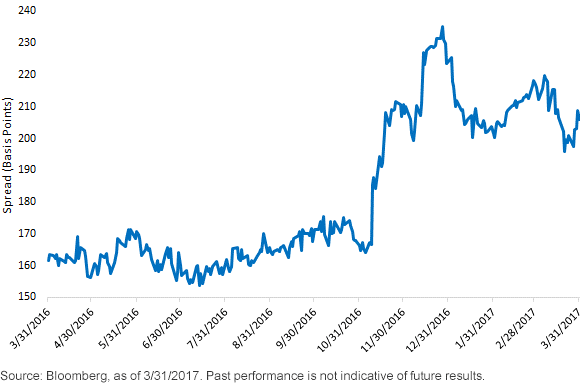
Do global bond yields matter any more?

U.S. 10-Year vs. 10-Year German Bund

By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Do global bond yields matter anymore? Following the results of Election Day and the subsequent response in the U.S. bond market, this was certainly a valid question. Indeed, with U.S. Treasury (UST) yields ascending rather visibly, a key investment force (relative yield advantage vs. the rest of the G7 universe) that had helped keep UST yields in check, if not push them even lower, seemed to fall off the fixed-income radar.

With the first quarter of 2017 now in the books, and the markets almost five months removed from the U.S. election, we thought it would be useful to provide some insight as to where the UST 10-Year yield resides now, and consider whether the relative yield advantage still exists.

While it has not always been a one-way street to the upside, G7 10-year yields have all risen to varying degrees, with the one notable exception being the UK, where gilts have actually seen a decline of 6 basis points (bps) since November 7. Italian 10-year yields fall on the other end of the spectrum, as the 10-year has experienced an increase of 61 bps, while the gain in France has been pegged at 50 bps. To put this in some additional perspective, the rise in the UST 10-Year was +56 bps. Rounding out the 10-year yield tallies: Canada +41 bps; Germany +18 bps and Japan +12 bps.

It should also be noted that the experience thus far in 2017 seems to have been a bit more country/region specific and not just the kind of broader move in global rates that investors have witnessed before. To be sure, here in the U.S., Treasury yields have been responding to developments in Washington D.C., such as the Fed pushing up its first rate hike three months earlier than expected and continued political headlines in the first few months of the Trump administration.

Continue Reading…