Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

David Chilton’s interview with me on his The Wealthy Barber podcast

As those who follow me on social media may already know, financial guru David Chilton interviewed me on his popular The Wealthy Barber podcast, which dropped Tuesday on YouTube.com. You can find the full 39-minute clip here: try 1.5x speed if you’re pressed for time!

David is a good interviewer and got me to confess a few things I might not have coughed up otherwise. Mostly, we chatted about personal finance in Canada, retirement and retirement planning and — a particular concern for David — the plight of young Canadians priced out of the Canadian real estate market. This included a discussion of our own family’s situation and how the “Bank of Mum and Dad” may be enlisted to supplement down payments scraped up by some combination of TFSAs, the RRSP Home Buyers Plan and the new First Home Savings Accounts (FHSAs) that David is quite enthusiastic abøut.

Naturally we talked about Retirement. David himself is retiring at the end of this year soon after he turns 65, so he will have “beaten” me to Full Retirement by roughly eight years. I wrote about his looming Retirement recently in my MoneySense Retired Money column, which was also flagged here on Findependence Hub.

A Who’s Who of Canadian Personal Finance
I was David’s 71st interview on the podcast since he launched it two years ago: he says he plans to keep it going at least until the end of this year. As I comment in the interview, his many guests constitute a veritable “Who’s who” of Canadian personal finance, with a handful of Americans thrown in.

Glad to be part of it and to join such luminaries as Ben Felix, Preet Banerjee, Rob Carrick, Fred Vettese and many more. As David notes, a lot of his guests are younger newer voices known as “Finfluencers,” a group I also wrote about in Retired Money earlier this summer.

We also discuss other more “seasoned” financial commentators, including Bruce Cohen, Ellen Roseman, Jim Daw, Mike Grenby and other pioneers of the genre. Some of those veterans’ names came up in another Retired Money interview I did after Rob Carrick retired a year ago from his full-time job at the Globe & Mail.

The financial novels spawned by The Wealthy Barber

With an estimated 4- to 5- million copies of his books sold worldwide, it’s no surprize that Chilton’s pseudo-fiction financial format spawned many imitators. I fondly recall Jim Daw (retired from the Toronto Star) cracking a joke about the many financial novel knockoffs inspired by The Wealthy Barber. Rather than a “branch” of personal finance literature, Jim quipped in his review of my own Findependence Day that this specialized field consituted merely a “twig” of the genre.

While much of the interview was perforce about investing and retirement, good interviewer that he is David manages to coax some confessions about my own lifestyle and choices. For example, I tackled headon the fact that the title of my own similarly titled The Wealthy Boomer was not initially conceived as a ripoff of Chilton’s far more commercially successful The Wealthy Barber: that title was just a description of the possible demographic target for the book’s publisher.

We also talked about 12 Good Years, the blog that blogger Fritz Gilbert originally ran on his Retirement Manifesto blog. That article make she case that new or aspiring retirees should strive to make the best of the years between ages 60 and 72, whether for strenuous travel or demanding hobbies, physically or mentally. Continue Reading…
Vanguard Canada launches its first actively managed domestic Fixed Income ETF

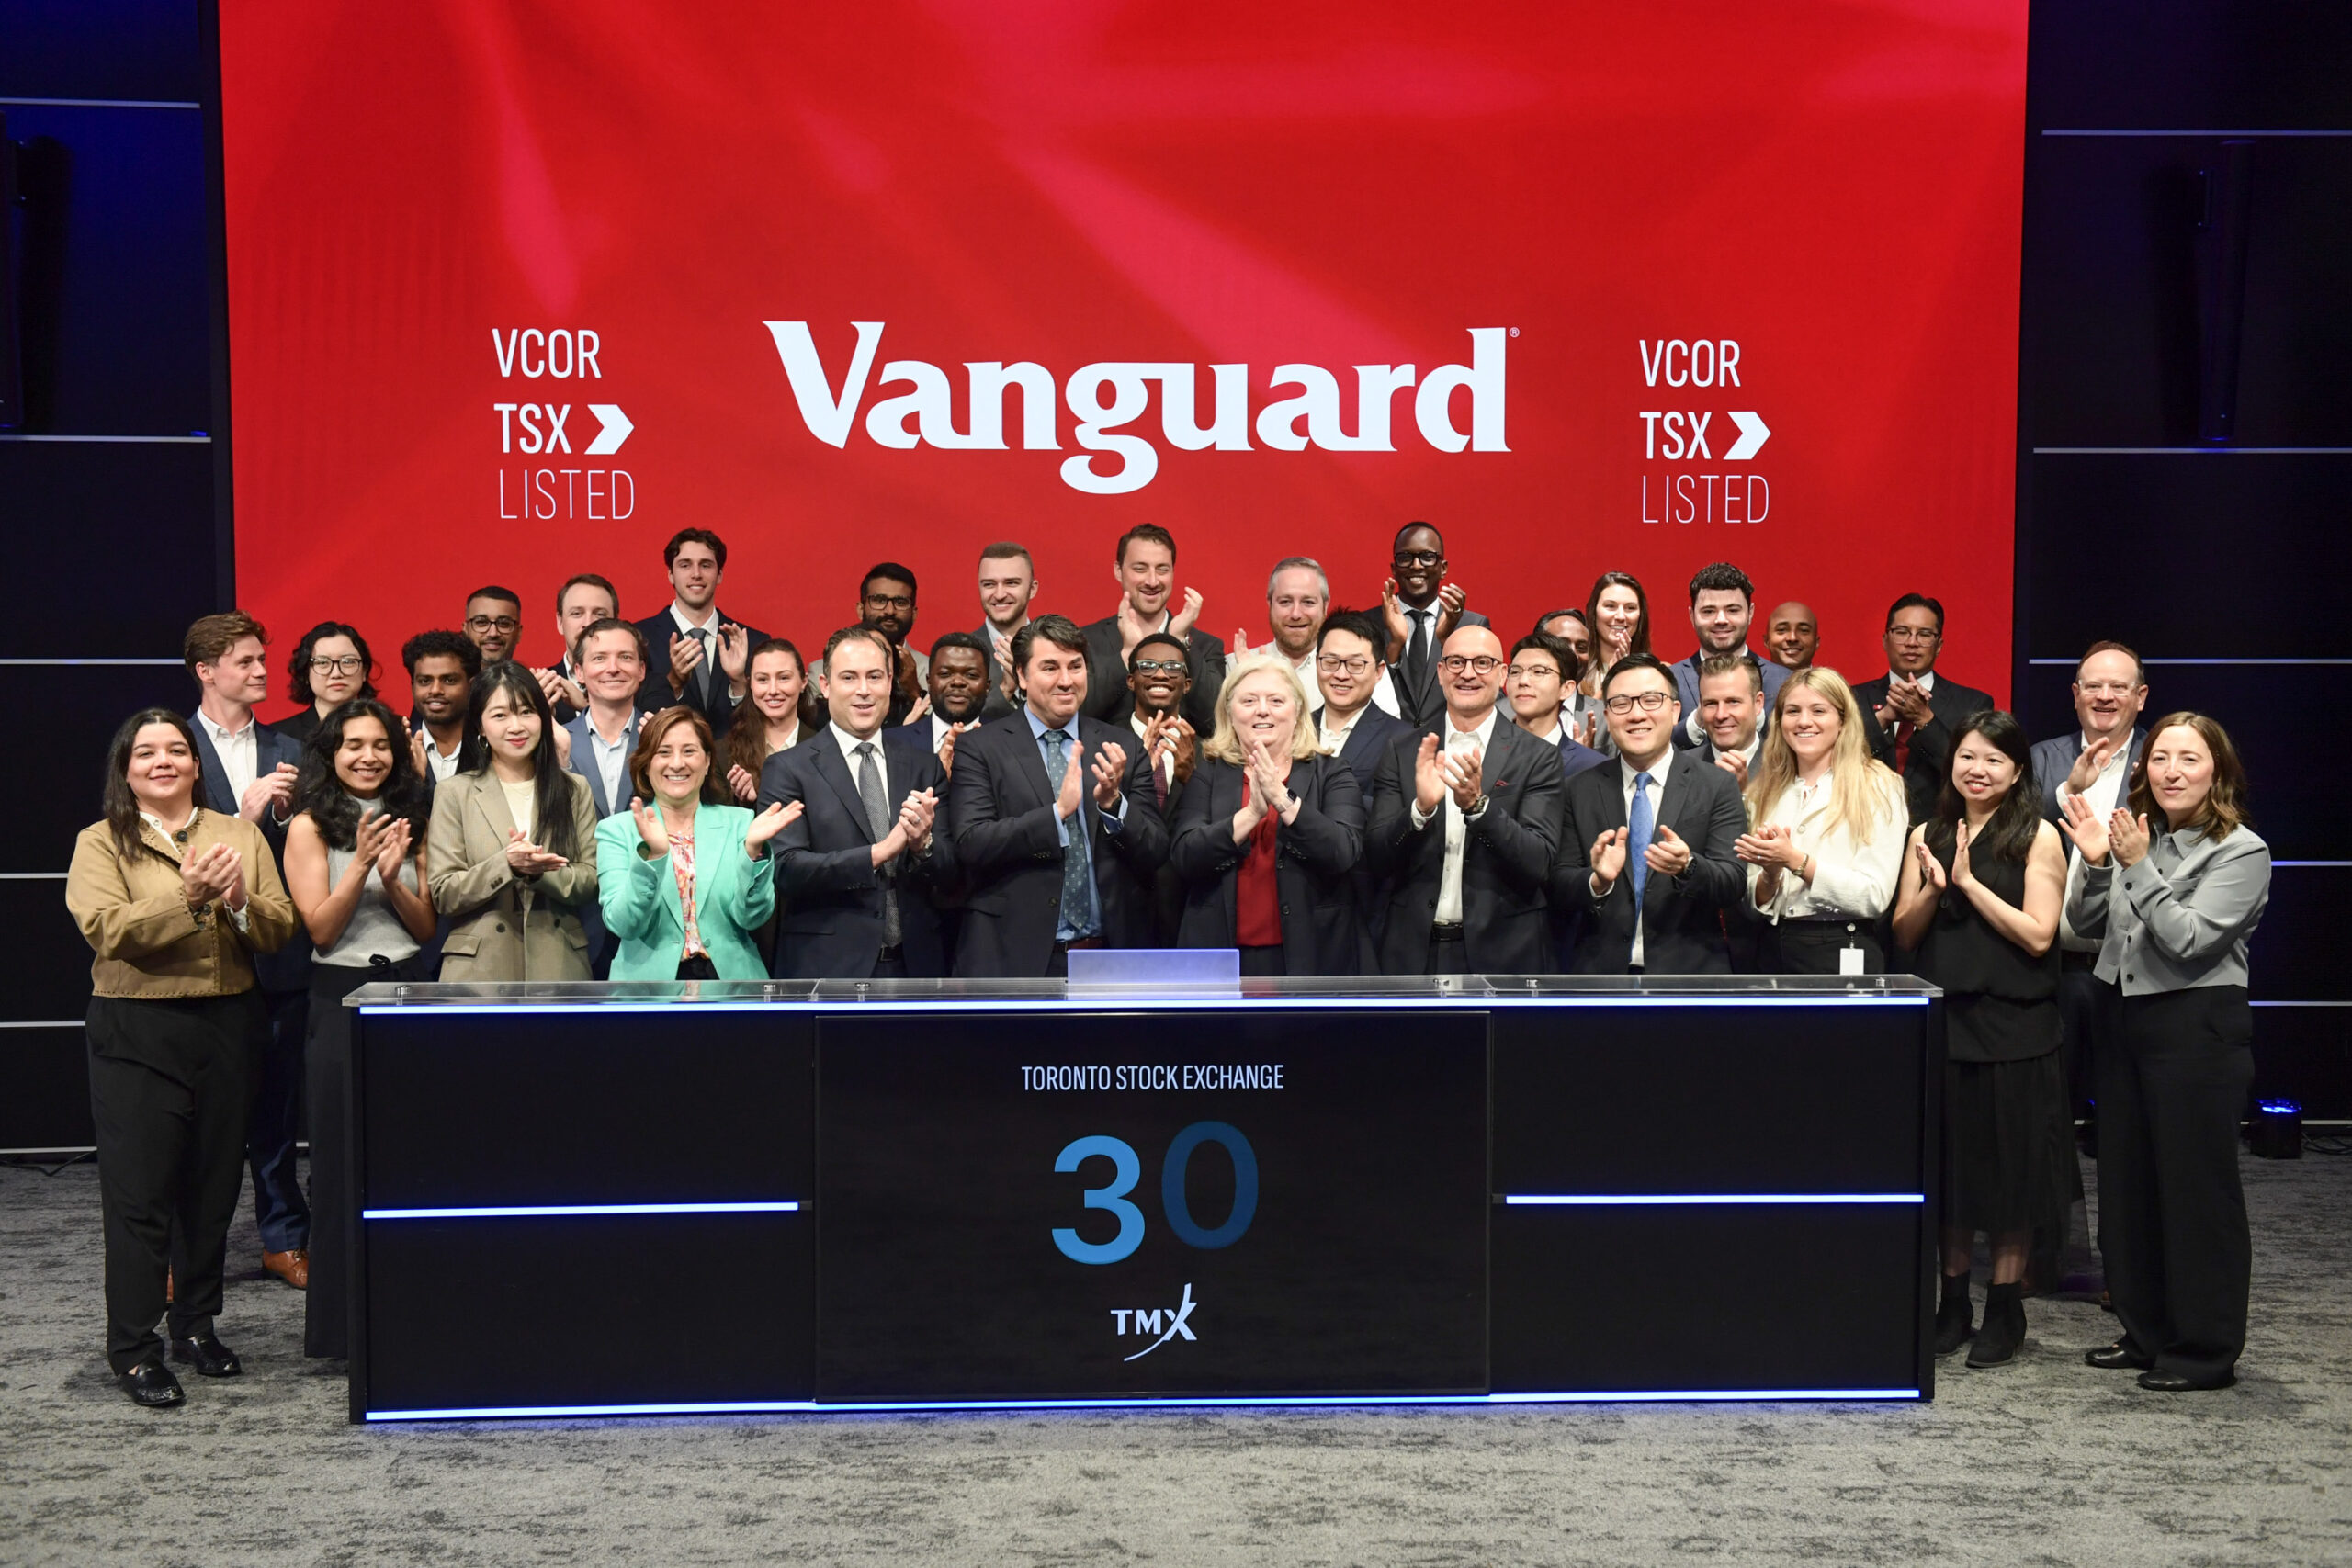
Vanguard Canada opens Toronto Stock Exchange on Sept. 9, 2026. Photo courtesy TMX Group.

Yesterday, Vanguard Investments Canada Inc. announced the launch of what it says is its first actively managed fixed-income ETF: the Vanguard Global Core-Plus Bond ETF (TSX: VCOR). VCOR began trading on the Toronto Stock Exchange on Wednesday (Sept.9, 2026), where Vanguard opened trading for the day (as shown on left.)

The new ETF was a major focus of one of two major presentations at Vanguard Canada’s annual Global Insights Forum, held in Toronto at the Royal York Hotel. The other was billed as Megatrends, AI and Market Implications.

In a press release, Vanguard Capital Management CIO and Global Head of Vanguard Fixed Income Group Sara Devereux described VCOR as being part of the firm’s push to make Vanguard’s specialized fixed-income capabilities accessible to more investors. She said it “combines the resources of our global investment platform, a disciplined active process, and broad diversification across fixed-income markets in a single ETF.”

It aims to provide investors and their financial advisors with an “actively managed, single-ticket fixed-income solution at a low management fee of 0.25%.” While the “core” allocation is to investment-grade bonds, it also invests in global rates, credit, and securitized markets,  along with a “plus” component that allocates to higher-yielding bonds.  Depending on markets, investors can expect allocations of between 20% and 50% for investment-grade credit; 0 to 20% U.S. treasuries/agency; 10 to 35% mortgages; 5 to 20% Emerging Markets debt and 0 to 20% high-yield corporates. The fund seeks to hedge its U.S.-dollar currency exposure back to the Canadian dollar and plans to pay monthly distributions.

Sal D’Angelo, Head of Vanguard Canada, said active ETFs have experienced significant growth in Canada and now account for roughly a third of Canadian ETF assets: “We continue to see strong advisor and investor demand for active global fixed-income solutions that offer broader diversification and access to a wider opportunity set.”

Bonds becoming more important for financial advisors as well as their clients

Dan Shaykevich/Linkedin

At the Forum on Wednesday, the new ETF was the focus of a presentation by Vanguard principal and senior portfolio manager Dan Shaykevich (pictured on right). Fixed income is once again playing a central role in investor portfolios, he said. As Canadian financial advisors prepare for CRM3 (Client Relationship Model Phase 3), it will also play a more important role for advisors too. The fund taps one of the world’s largest Fixed-Income money managers: Vanguard’s global fixed income team manages US4.2 trillion in assets under management, including C$30 billion in Canadian Bonds.  It’s supported by more than 20 portfolio managers, 35 traders, 50 credit researchers and at least eight quantitative analysts.

Generally speaking, financial advisors tend to spend more time with clients on equities than on Fixed Income, Shaykevich said, “even though Fixed Income may be 20 to 40%” of advisors’ money under management.

Marketing materials distributed at the event included an insert on Fixed Income Investing reminding investors that bonds can complement the growth potential of equities by providing stability, generating income and supporing diversification.

The insert lists several already existing Canadian Index-based Fixed Income ETFs. They include: Continue Reading…

Time for Core (Plus) Bond Portfolios Again?

By Christy Tan and Lukasz Labedzki, Franklin Templeton Institute

(Sponsor Blog) 

Investment Implications

We see growing evidence suggesting that investors should consider moving from a short-duration bias toward core (plus) bond portfolios. This is largely predicated on the fact that valuations have become more attractive across fixed-income sectors, with all-in yields approaching compelling levels. Our guidepost remains 10-year Treasury yields near the upper end of their recent range. We continue to believe that this is a market for an active, selective approach.

Please see our sector views below.

Central banks: We have a new Federal Reserve (Fed) chair, and if we take him at his word, it feels
like a new environment has begun. The rhetoric is hawkish, reinforcing that the 2% inflation target is
by no means soft. Importantly, there’s also a strong push for no forward guidance, with the market
invited to react to incoming data as it sees fit. That likely means a higher-volatility environment and,
all else equal, a higher risk premium demanded by bond investors. As a result, all eyes are now on
the data. If the data fails to confirm moderating inflation, the market will demand Fed action. If the
data does confirm it, the market can justify a pause. In both cases, longer duration can perform
well. The risk is the Fed policymakers talking but not acting when needed: that would make the
bond market angry. We see the risk-reward of extending duration as improving and are happy to do
so at certain yield levels.

US Treasuries: Our view is that 10-year Treasury yields will remain broadly range-bound, which
means the closer they get to 4.75%, the more attractive it becomes to move into intermediate
duration. We believe it is reasonable to begin extending duration around those yield levels.

Developed markets credit: Historically elevated investment-grade bond issuance that the market
needed to absorb widened spreads from their tights to levels closer to fair value, while the broader
fundamental backdrop remains healthy. Supply should also slow in the second half of the year. In
the high-yield space, spreads have also widened somewhat. We remain biased toward higher-rated
issuers in high yield. All-in yields are attractive and provide resilience across a range of scenarios.

Emerging market (EM) debt: While it has been the best-performing fixed-income sector
year-to- date, we think it’s time to be more selective. In local-currency EM debt, Latin America
has been the top performer (as we highlighted), and we expect this to continue. As a stronger US
dollar remains a risk, in our view allocations should be balanced with US dollar-denominated EM
debt, which is less sensitive to currency moves.

Euro bonds: As mentioned previously, we believe German Bund yields (Europe’s benchmark
government bond yields) will remain broadly range-bound. They closely track expected mone-
tary policy, which has recently been driven largely by gas prices. With Bund yields above 3.1%, we
find them attractive for medium-term investors. Hedged yields for US dollar-based investors are
on par with US Treasuries, meaning there is little opportunity cost to global diversification.

Performance Snapshot

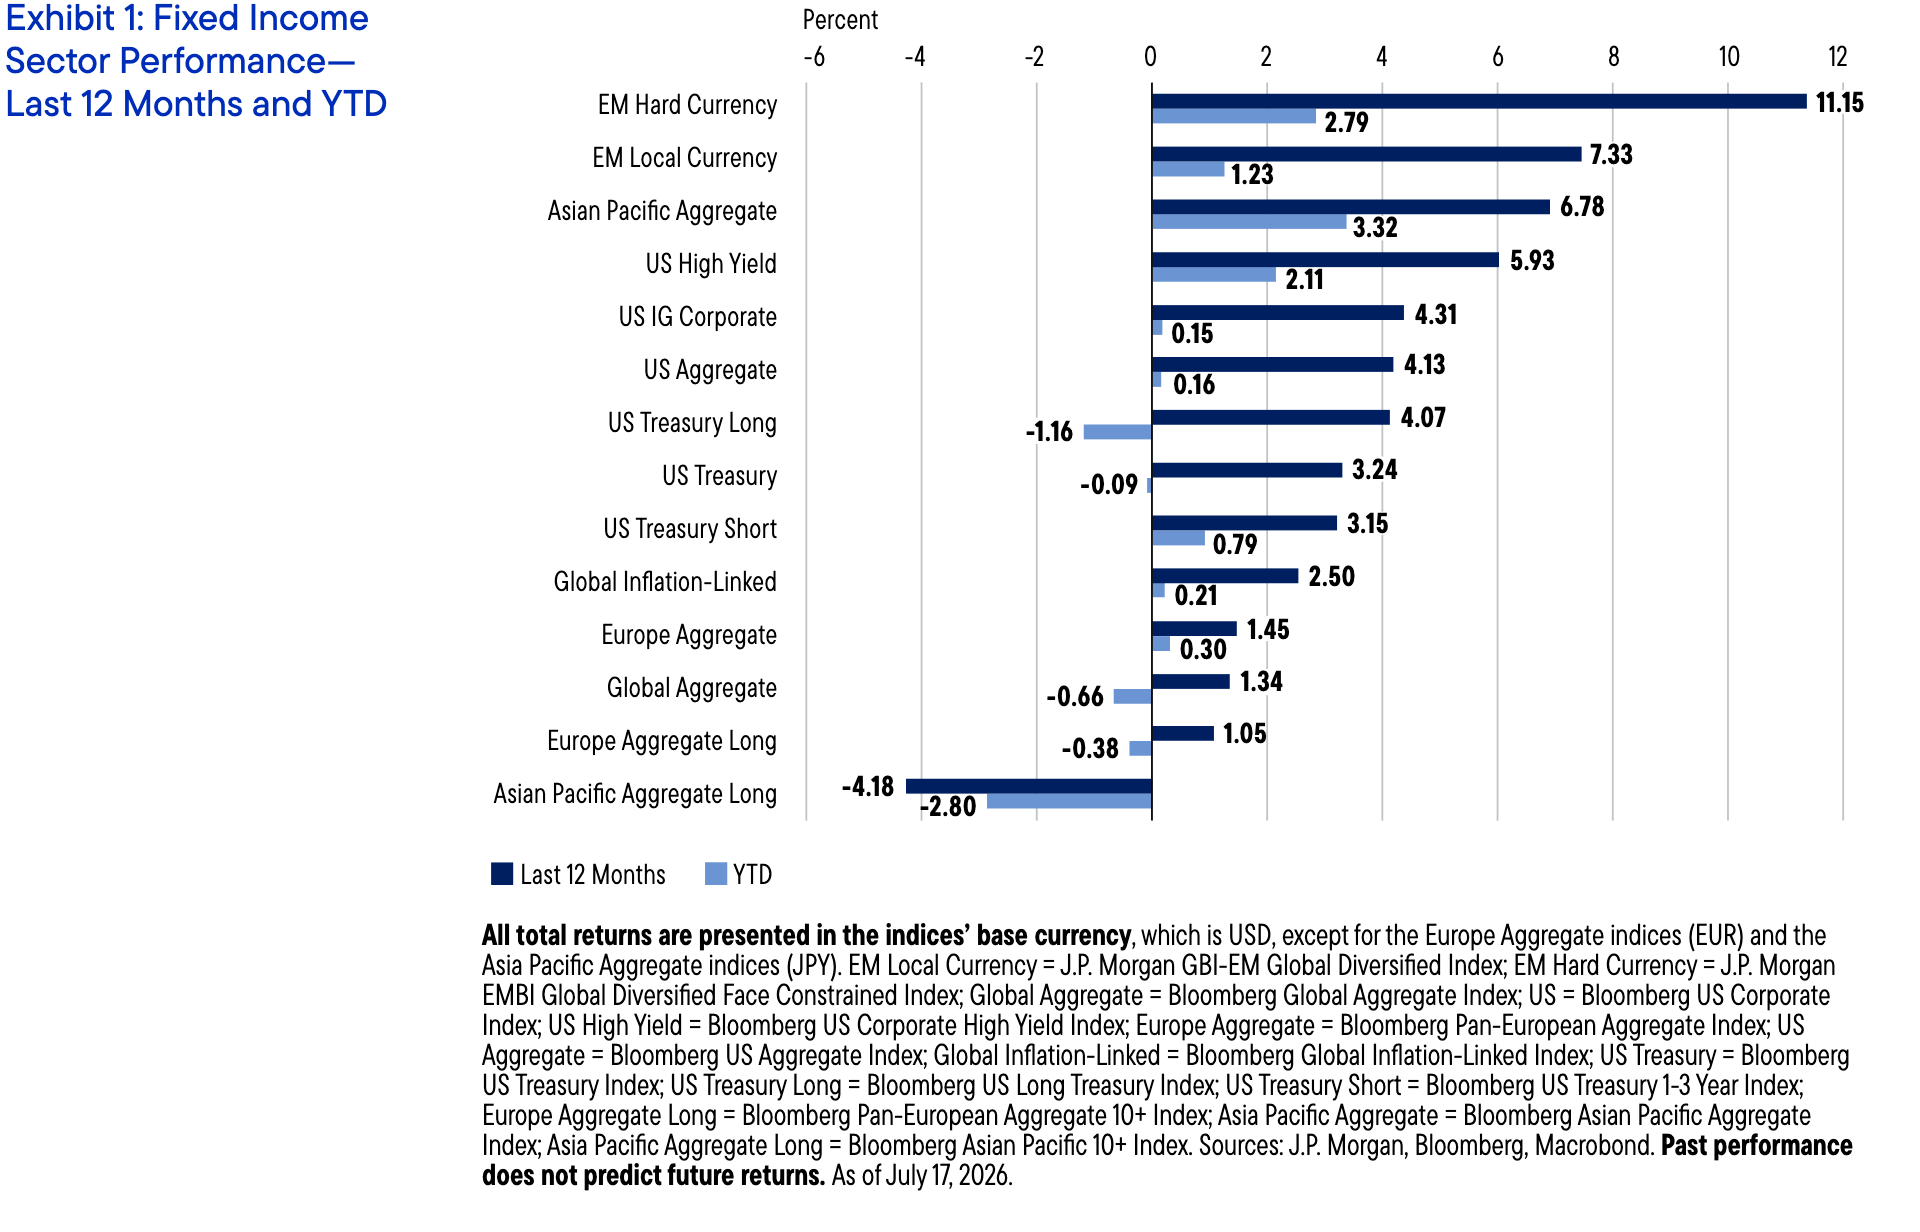
Global fixed-income performance has remained largely uninspiring this year, with the Bloomberg
Global Aggregate Index still slightly underwater. Relative performance has been stronger in
emerging market debt, particularly US dollar-denominated debt. The picture is more nuanced in
local-currency EM debt, which we discuss later. US high yield has also outperformed. Within
higher-quality fixed income, US short-duration strategies have also held up relatively well. These
are essentially the sectors we have been highlighting throughout the year.


US Treasuries

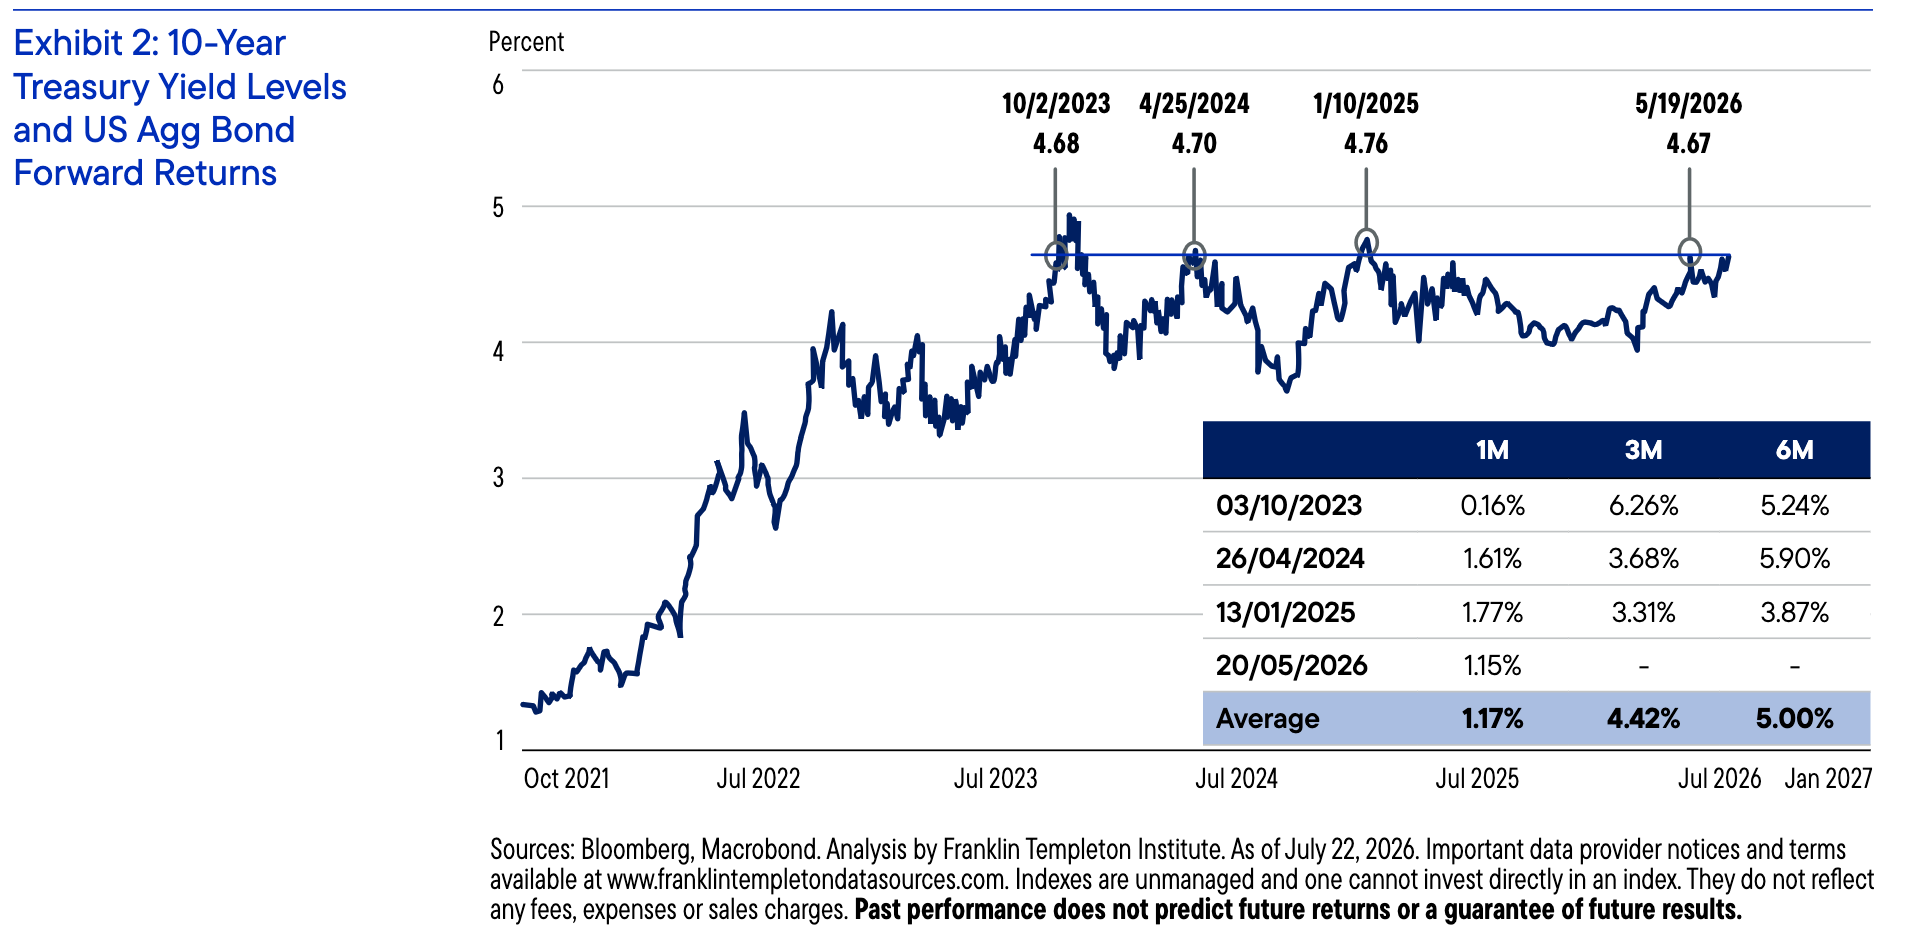
We believe benchmark 10-year Treasury yields will remain broadly range-bound, and investors should take advantage when yields are close to the upper end of that range (~4.75%). Recent history (Exhibit 2) suggests this strategy has worked well and remains our playbook for the second half of 2026.


Of course, yields could move higher, but at these levels we view the risk-reward as favorable and do not see a high risk of yields moving significantly above the recent range over the coming months. The main reason is that a lot is already priced in: the market expects more than two Fed hikes over the next 12 months,1 while the current term premium (the risk premium in bond jargon) is close to 70 basis points (bps),2 versus a recent high of around 90 bps. A meaningful move above 5% in 10-year Treasury yields would likely require a further significant repricing of both monetary policy expectations and the term premium.

The major risk is that the Fed turns more hawkish than in our base case. We acknowledge this risk, but we also think that realized hikes could, in fact, cause longer-duration bonds to catch a bid, as they would demonstrate a strong commitment to fighting inflation and could lead to a repricing of growth expectations.

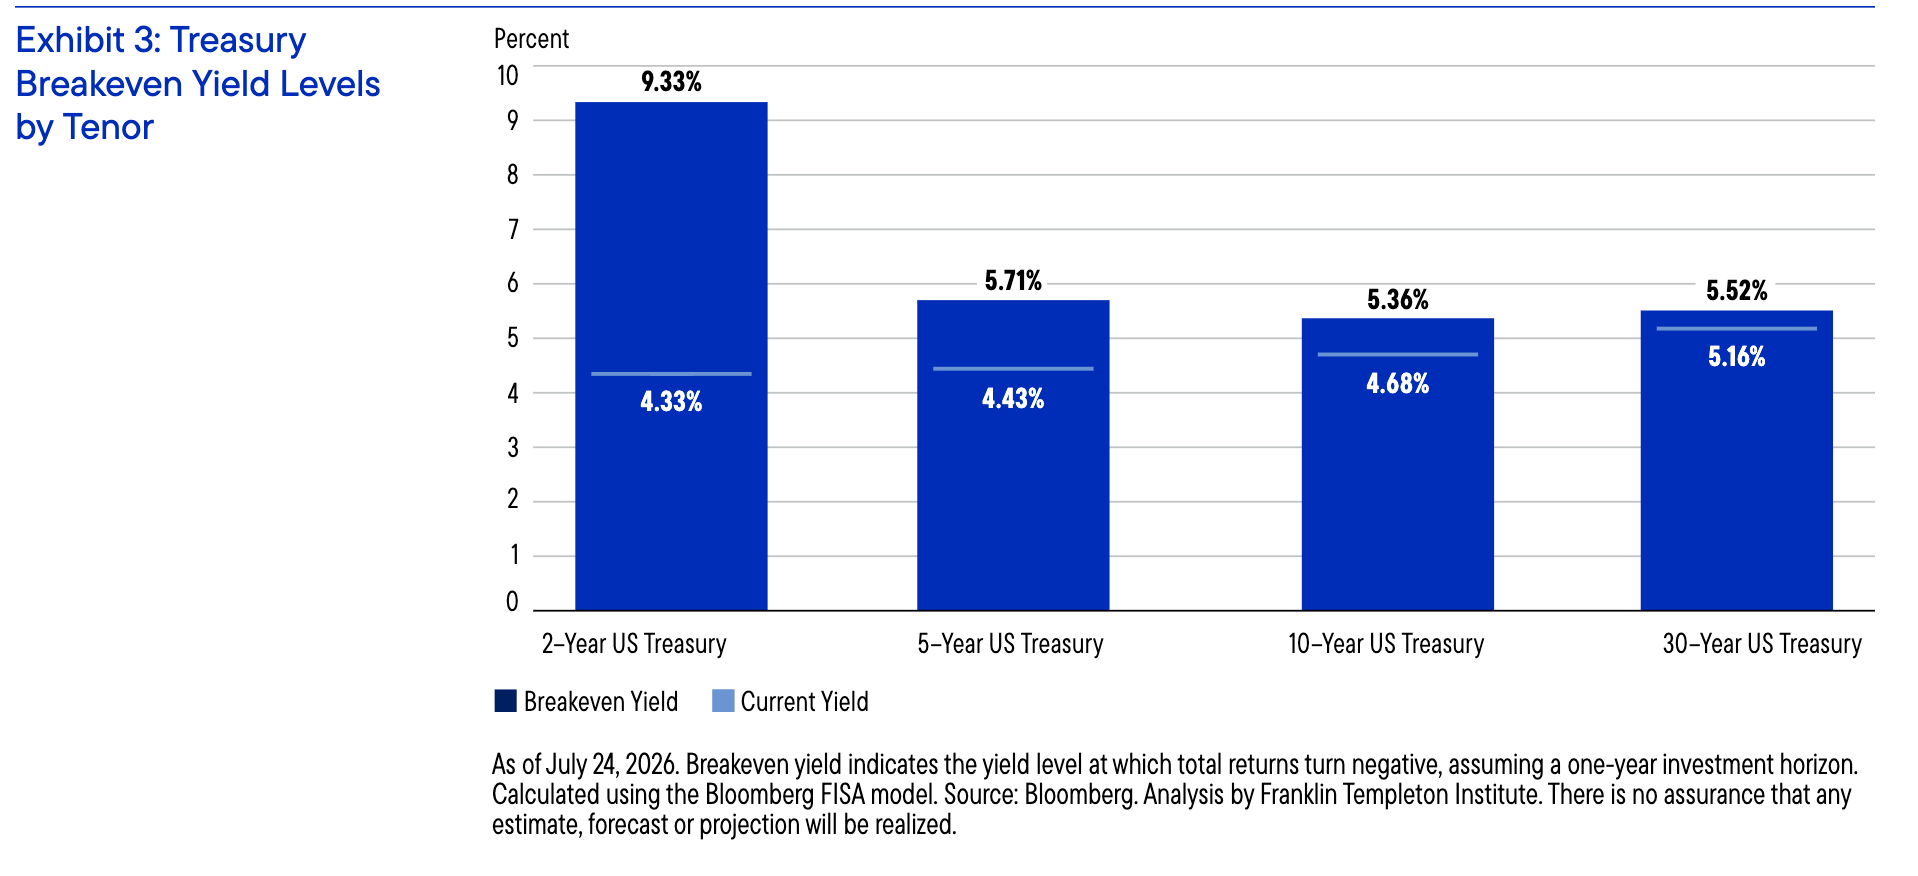
For conservative mandates, we continue to view short-duration bonds as a portfolio pillar. They are highly resilient across scenarios: two-year Treasury yields would need to rise above 9% before investors started losing money, assuming a one-year investment horizon (Exhibit 3).

Developed Markets Credit

The major story in credit markets lately has been investment-grade (IG) bond supply, driven in part by hyperscaler borrowing. More than US$1.2 trillion3 of IG issuance came to market through the first six months of the year: well above historical norms (Exhibit 4). Continue Reading…

Canadian Kids picking up on their Parents’ Money Stress, new Vanguard Survey finds


Even when parents try to shield their children from financial worries, a new study suggests kids are hearing more than parents realize.

As the cost of living continues to squeeze Canadian households, a new survey from Vanguard Canada suggests the strain isn’t confined to parents’ bank accounts; it’s also shaping how their children think and feel about money too.

The survey of just over 1,000 Canadian parents of children under 18 found that households that talk openly about money raise more financially literate kids, while households that avoid the subject may be doing more harm than good.

The Instinct to Protect backfires

Many parents try to keep financial stress away from their kids. Among parents who describe themselves as financially stressed, more than two thirds said they feel pressure to hide their worries from their children, and roughly a third said they avoid discussing money at home altogether.

But the survey suggests that instinct doesn’t work the way parents hope. Seven in ten financially stressed parents said their children overhear money conversations anyway. In fact, those children were found to be nearly five times more likely to feel anxious about money than their peers.

Sal D’Angelo, Head of Vanguard Investments Canada, said children pick up on far more than parents assume, even when adults try to keep financial matters private. He framed early financial education as key to helping the next generation build healthy money habits.

 A Literacy Gap that starts early and closes late

The survey also points to a timing problem. Households where money is discussed regularly produce children with markedly stronger grasp of core concepts like banking, debit and credit, which is nearly three times higher comprehension according to the findings.

Yet the majority of parents said substantive money conversations don’t begin until their child is between 15 and 18 years old, well after attitudes toward money have already started to form. Continue Reading…

How to think about a Mortgage Renewal Offer before you Sign

Image courtesy of FairRate Canada

By Andy Atchison, FairRate Canada

(Special to Financial Independence Hub)

Getting a mortgage renewal letter seems pretty straightforward. Your lender gives you a new rate and payment, you sign it, and you’re done.

At least that’s how it looks.

What I started wondering was: how does the average homeowner actually know if the offer they’re getting is any good?

I’m not a mortgage broker or financial adviser. I’m just someone who started digging into this and realized it’s surprisingly difficult to get a simple answer. You can search mortgage rates online in about 30 seconds. The problem is that the rate you find isn’t necessarily comparable to the renewal offer sitting in front of you.

There can be different conditions, different mortgage types, different equity requirements and all sorts of other details attached to an advertised rate. So if your bank offers you 4.89% and you find 4.24% online, that doesn’t automatically mean your bank is ripping you off.

But I’d certainly want to know why there’s a difference.

The rate is a starting point

Obviously the interest rate matters.

A difference that looks fairly small on paper can make a noticeable difference to your payment, especially with a large mortgage balance.

But there are other things worth looking at too.

What are the prepayment privileges? What happens if you need to break the mortgage early? Is it portable? Are there fees or restrictions? And if another lender has a lower rate, what would it actually cost and involve to move the mortgage?

Those details aren’t nearly as exciting as finding a lower rate, but they can matter.

There’s nothing wrong with staying with your bank

I think this part sometimes gets lost.

Switching lenders isn’t automatically the smart move. Continue Reading…