Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Have you considered Shared Housing during Retirement?


By Steve Barker

(Sponsored Content)

Anyone who is approaching the age of retirement or planning for their eventual retirement is likely to give a lot of thought to just how much they’ll need to enjoy their golden years. While affordable life insurance policies are something else to add to the retirement list, so, too, is whether it would be a good idea to look into living with other people in shared housing: not only to reduce living expenses, but for a host of other reasons as well. Ready to learn more?

High cost of living combined with diminished resources

No matter where you live, chances are good that the cost of living has gone up in the past couple of years, a trend that is likely to continue. While you can control how much you save for retirement, you cannot control how expensive everything from food to medication will be when you’re ready to retire. Additionally, there may not be government or federal financial resources available when you reach the age of retirement, cutting off another source of income. Living with roommates can help immensely in cutting down the cost of living without the need for you to go to great financial and personal lengths to make your living situation work.

You have a built-In social circle

Many seniors grow lonely as they age because they aren’t able to get up and about as much as they used to when they were younger. When you live with people you get along with, being social is as easy as walking down the hall. Elderly individuals who have mobility issues don’t have to worry about making special transportation arrangements to spend time with other people, and being social can be mentally and emotionally beneficial for everyone, no matter their age or health.

Share common house chores

Keeping an entire house clean can be quite a task even for married seniors. Rather than hiring house cleaning services, which can drain your retirement funds, you may find it’s better to divide the chores between the people you live with. Besides saving money, chores allow you to move around and keep somewhat active, which senior citizens need to remain healthy. Continue Reading…
5 ways Real Estate boosts Financial Independence

By Sia Hasan

Special to the Financial Independence Hub

Gaining financial independence is one of the most difficult propositions. Life is expensive, particularly if you live in a metro area, which is where most of the higher paying jobs are located. As a result, most people save only small amounts of their paychecks or none at all. Clearly, this is not the path to financial independence (aka “Findependence.”).

Thankfully, you don’t have to make a massive salary to become financially independent. There are several methods for building wealth, including starting a business, investing in securities, and investing in real estate. Even if you do the first two already, you need to consider these five ways of increasing your financial independence through real estate.

Real estate investment offers the highest returns for the lowest risk when compared to starting a business or investing in stocks. The reason is that real estate offers five surefire ways to grow your money, known by the acronym IDEAL. By setting a long-term plan to benefit from these five methods of making money in real estate, you are on your way to financial independence.

The IDEAL investment

IDEAL stands for income, depreciation, equity growth, appreciation, and leverage. To succeed in making real estate work as an investment, you need to look beyond your principal residence. Though owning your own home provides appreciation and tax benefits, most people can’t produce income from their principal residence, owners of duplexes and people who rent out spare rooms aside.

1.) Income

When you purchase a rental property, you generate income, provided that you collect enough rent to exceed expenses. With a cash purchase, this is easy. If you finance the purchase, you need to analyze the numbers carefully. Provided you finance the right rental property, you earn a much higher rate of return on the financed property than if you purchased it with cash.

2.) Depreciation

To increase your rental income profits, you need to bone up on the IRS depreciation rules. Because the property is a business investment, you get to deduct all depreciation off of your profits. This saves thousands of dollars in income taxes every year. Continue Reading…

6 smart ways to clear Credit Card Debt as quickly as possible

By Shiv Nanda

Special to the Financial Independence Hub 

Credit cards can be a saving grace in time of financial need, but if abused can ruin your financial health. Most Americans have a love-hate relationship with their credit cards and the stats seem to agree.

Total US credit card debt is over $830 Billion.

 Of the more than $1 Trillion of revolving debts, Americans are carrying the vast majority of debt in 2018.

 Let’s break down these troubling credit card debt statistics by category:

Studies have found an average of 39% of credit cardholders pay their credit balances in full. And only 29% make low or minimum payments. This is an alarming finding because cardholders who make the minimum payments 20% of the time are the ones with a credit score of 800 and above. While cardholders with credit score of 700 and above are more likely to make full payments towards their credit-card balance. However, there are other factors that contribute to the credit card payment pattern:

1.) Income and Employment

 It is quite surprising that high income doesn’t guarantee freedom from debt. Ironically, the debt seems to be increasing with increase in annual income. And the highest credit card balances are seen with people with the highest income.

2.) Age and Gender

Studies reveal that older customers are more likely to pay their credit-card balance in full whereas middle-aged consumers may pay in full or pay the minimum amount due. Middle-aged consumers have high home expenses as they have dependents to take care of. Gender of the consumer is also a contributing factor of credit card debt. Data shows that men and women have a revolving debt of 29.9% with women having 3.7% less than their male counterparts.

3.) Region

Location has proved to be an interesting influence on credit-card debt. The Midwest and the Great Lakes regions seem to have responsible credit cardholders. They have the highest average credit score and lowest average credit card debts: while Alaska seems to have the highest credit card debt and average credit score stuck somewhere in between the high and the low.

6 smart ways to clear credit-card debt ASAP

1.) Have a plan and stick with it

It is essential that you take a stock of the situation. Continue Reading…

Retired Money: How to beat the banks at their own game

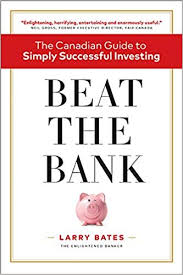
My latest MoneySense column reviews the new book by ex banker Larry Bates, titled Beat the Bank. As the headline suggests, it’s all about how to beat the banks at their own game, which ironically can mean owning the big bank stocks themselves! The full column can be retrieved by clicking on the highlighted text here:  Tips for DIY investors on beating the Big Five banks.

The formal launch date for the book is this Thursday: September 13, 2018. I first met Bates over lunch in March as his manuscript was nearing completion, where he expounded on what he called the “two Bay Streets.” Old Bay Street and its secrets are the focus of chapters 4 and 5, and New Bay Street is chapter 6.

Old Bay Street is not the investor’s friend

Most experienced investors will have encountered Old Bay Street at some point. This is the traditional investment industry: the commission-based mutual fund and brokerage industry, insurance company reps, investment “specialists” in the bank branches and various salespeople who call themselves “advisors.”

New Bay Street = Discount Brokerage, ETFs & fee-for-service planners

The New Bay Street includes providers of low-cost index funds or Exchange-traded Funds (ETFs) or online robo-advisers that automate the purchase and rebalancing of ETFs along with setting asset allocation.

At 62, Bates is well into his own “Victory Lap,” leaving employment for self-employment. Actually, his New Bay Street model isn’t all that new, as it describes models similar to what I myself described back in 1998 in my own financial book, Findependence Day. My version consists of buying ETFs at a discount brokerage and using a fee-for-service financial planner. The same year, similar principles were also described in Stop Buying Mutual Funds!, by Mark Heinzl, now a Globe & Mail stock market columnist.

Dinosaur banks have the lowest T-REX scores

Bates has fashioned something he calls T-REX scores  This is an acronym for Total Return Efficiency Index Score. A T-REX score of 100% would be paying absolutely no fees at all, no matter how long your time horizon.

Mutual funds with 2% annual fees would have T-REX scores of 54% over 20 years and true fees of 46%, but the longer you hold, the worse the performance; thus, over 40 years the T-REX would be 41% and the true fee 59%. Fees of 3% inflict even more damage. This is the basis for his statement that long-term customers of Old Bay Street lose half their money to fees. You can find more at his website at www.larrybates.ca.

The pure DIY model of buying individual stocks or bonds at a discount broker yields the highest scores: a T-REX of 96 to 99%. (Remember, the higher the better, with 100 being perfect).

Continue Reading…

Getting the best bang for your buck with everyday purchases

By Sia Hasan

Special to the Financial Independence Hub

You work hard for your money, so it makes sense that you would want to stretch your dollar as far as possible. If you are like many other hard working adults, you may splurge here and there on a cup of coffee or a matinee movie. However, most of your take-home pay may go toward everyday or typical purchases. These may include food, gas, clothes and more.

It may seem challenging to stretch your dollar in these essential areas, but rest assured that there are several strategies you can employ to get the most bang for your buck. Before you make another purchase on regular or everyday items, consider how these tips can benefit you.

Choose your payment method carefully

The primary payment methods for standard purchases are cash or credit cards. Cash may be in the form of hard currency, checks or a debit card. Many people believe that paying with cash or a cash alternative is a smart option because it helps you avoid taking on expensive debt. It is true that debt can cost you money.

However, if you use credit cards responsibly, a credit card may be a better payment option. Consider that you can make all your regular purchases with a credit card, and you can pay the full balance off each month. Therefore, no interest is accrued, and there is not a cost for using the credit card. You may enjoy the benefit of bolstering your credit score with responsible use of your credit card. Keep in mind that higher credit scores may qualify you for a lower rate on a mortgage, a car loan, insurance rates and more. Therefore, this payment method can yield tremendous savings over time.

Take advantage of Credit Card Rewards

When you make purchases with credit cards regularly, you may also enjoy the additional benefit of earning rewards points. You can begin by searching for a good credit card for average credit and comparing rewards programs or opting into the rewards program on an existing account. Pay attention to the fine print as you compare programs. Some credit card rewards programs, for example, limit the points that you can earn within a specified period of time. Other programs require you to use the points within a certain period of time. These rewards may essentially give you cash back on your purchases, or the points may be redeemed for other items with financial value.

Shop around

Even when you take these steps to stretch your dollar, there may be other ways to save as well. Shopping around is easier to do than ever because of the Internet. Continue Reading…