Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

The (Renewed) Case for GICs

**This is a sponsored post written by me [Robb Engen] on behalf of EQ Bank. However, as always, all opinions are my own.

A guaranteed investment certificate (GIC) is unlikely to spark an exciting dinner party conversation but when stock markets are reeling, like they were earlier this year, investors often seek safe havens to wait out the storm. Cash is king for those who don’t have the stomach to watch their portfolio plunge in value, and GICs at least offer the promise of a modest return.

Back in February 2009, when the global financial crisis had just about reached rock-bottom, 30-year-old me was scrambling to meet the RRSP deadline and bought a five-year GIC. It was a costly mistake in hindsight. The Toronto Stock Exchange surged ahead for the next five years, earning annual returns of 9.52 per cent, while my five-year GIC earned an average annual return of 2.75 per cent.

Instead of turning my $7,000 contribution into nearly $10,000, I only had $7,800 to show for my decision. At the time, though, I thought the GIC was a smart move because I had to make a quick decision on what to do with my contribution, and the stock market still looked downright nasty.

Why invest in GICs?

The truth is there’s nothing wrong with stashing your savings inside the comfort of a GIC. Here are four times when it makes good sense to put your money in GICs:

1.) When your entire portfolio is sitting in cash, waiting for “the right time” to get into the market

If you’re the type of investor who can’t ignore the doom-and-gloom economic headlines, and who’s convinced that a market meltdown is always imminent, maybe the stock market isn’t right for you.

Having your retirement savings constantly sitting in cash and earning nothing is like sitting on the fence and being paralyzed to move for fear of making the wrong decision at the wrong time.

A GIC ladder, which might involve purchasing equal amounts of one, two, three, four, and five-year terms, will maximize your risk-free returns and still give you the option of dipping your toes in the market each year when one of the terms comes due.

2.) When your investing strategy boils down to chasing last year’s winning stocks or mutual funds

If you’re the type of investor who’s constantly looking for the latest fad, you might be falling victim to the behaviour gap – the difference between investment returns and investor returns.

Consider that, according to DALBAR, from 1986 to 2016 the S&P 500 Index averaged 10.16   a year, but the average equity fund investor earned just 3.98   a year.

When you think about our poor investor behaviour, coupled with sky-high mutual fund fees (at least, here in Canada), those investors who just can’t help themselves might be better off parking their savings in the best five-year GIC and earning a guaranteed return. Continue Reading…

Which Robo Advisor differs from the other?

I recently penned the blog What and who are the Canadian Robo Advisors? That blog outlined how, true to the moniker, a robo advisor is an online financial advisor without the human.

Well, let’s say that at times there is no human present. In actuality the robo advisors are all quite human and they all have a unique personality. Think Star Wars and the loveable tin cans known as R2-D2 and C-3PO. They are very different in voice and personality.

Above left is R2 …

And to the right is my robo mascot …

The answer to the question posed in the headline is that all of the robo advisors are different, at times very different from one another. That’s why it’s important to know and understand these differences so that you might be able to find the robo that’s right for you. Getting in the ‘right robo’ might make a difference of thousands to tens of thousands of dollars or more over an investment lifetime.

The ‘robots’ don’t think in a pure sense. In most cases, this is not artificial intelligence at work. The process involves investment concepts and approach(es) and then mountains of computer programming applied so that the robo platforms can follow the direction of the human financial gurus who set the course for each robo advisor.

The Chief Investment Officers and their teams can and do also make adjustments on the fly. Some may react to market conditions. That may seem ironic given that the robo advisors will mostly embrace and use mostly passive Exchange Traded Funds, but they will then get a little more active with regards to asset allocation and types of funds used based on changing market conditions. All said, that will be one of the factors that I track moving forward as we compare the performance of the Canadian robos.

Robos can be passive or active

Some robos are more passive, some robos are very active.

One of the robo advisors, responsive, is considered AI-based as the platform will automatically change the asset allocation (mix of stocks and bonds) based on many market and economic indicators. Continue Reading…

What and Who are the Canadian Robo Advisors?

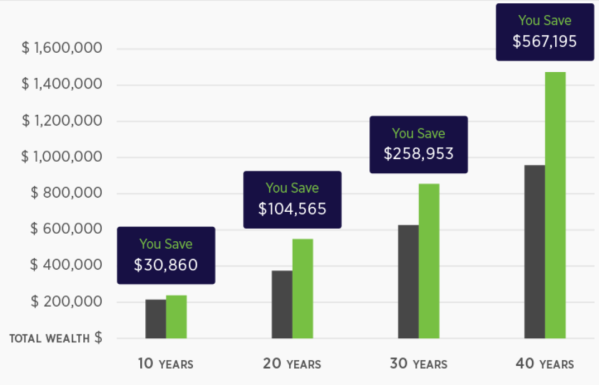
But just because you might need an advisor does not mean you have to pay some of the highest investment fees in the world. And yes the fees are important. We know that the fees typically and greatly impact the returns. From Justwealth the chart at the top is a comparison of the potential portfolio returns impact over longer periods, based on an initial $100,000 investment.

We can see that the effect of high fees paid can become exaggerated over time. Remember you pay investment fees every year, throughout the year, and as your portfolio grows over time you pay more in fees as the fees are based on your portfolio value. That’s a nasty kind of negative compounding.

So just what is a robo advisor?

Yup, just as per the image, a robo advisor is an investment advisor that’s well, not human. But don’t be scared. If you want to talk to a human the companies that offer robo advisory services can also put you in touch with real flesh and blood advisor types.

So if a robo advisor is not human, just what is “it”? A robo advisor is simply an online platform that asks you questions to help you get into the right investment portfolio. A robo advisor will ask the same type of questions as would a human advisor. Based on your answers the robo advisor will put you in the appropriate portfolio.

So what type of questions will the robo advisor ask you?

The robo advisor platform may try and gauge your investment knowledge. There may be questions on your net worth and salary and employment status, basic personal details. Each robo advisor offering has its own nuances and I will dig deeper into that in future articles. But most importantly a robo advisor wants to know …

  1. Your time horizon for the monies that you are about to invest.
  2. Your tolerance for risk (the amount or percentage that the portfolio could decline).
  3. Your objectives for the investment, whether you’re looking for more growth, a more balanced approach or a very conservative approach that might include a lot of bonds and fixed income.

And once again, each robo advisor will have its own methods (robo personality?) for asking those questions and discovering your investment personality and needs. If you want to ‘play around’ with a basic robo question and answer process have a look at Tangerine Investments’ Portfolio Selector Tool. Continue Reading…

7 tips for earning extra money from your Driveway

By Sarah Kearns

Special to the Financial Independence Hub

Do you want to earn a quick extra buck or two with items that are just lying around the house? How about making money off your handyman skills? And, oh, did you know that it’s also possible to earn extra money from your unused driveway space?

If you’re looking to earn some extra cash by running your own business right on your very own driveway, then you might want to consider these seven money-generating tips.

1.) Hold a garage sale

The first thing that comes to mind when you think of earning money from your driveway is the garage sale. Aside from earning a few hundred dollars, you also get to clean out the clutter in your home. A garage sale is also a good weekend family activity and is a great exercise to learn about the basics of entrepreneurship.

2.) Set up a concession stand

Remember those lemonade stands kids put up during summer break? You can set up a concession stand on your own driveway too! It’s even better if your street has lots of foot traffic. Of course, different countries, states, or territories have different laws regarding this; so, always check your local regulations first before you set up.

3.) Rent out your tools

If you have tools that are seldom used, you can rent them out to neighbors and contractors in your area for extra cash. There are websites like ToolMates that let you post your for-rent tools and equipment online. These services let you make some extra money off your tools; which is always better than letting these expensive items just gather dust in the shed.

4.) Start your own handyman business

Since we’re already on the topic of tools, you can also set up your own, independent, handyman business. If you have handyman (or handy woman!) skills like carpentry, ceiling repair, car maintenance, and such, then it might be good to put those skills into work and earn some extra money. Sites like AirTasker allow you to post your services online so that people in your area can get in touch with you whenever they need your skills.

5.) Share your car with neighbors

Now, this is a fairly new concept and companies like Lyft and Uber have taken this innovative idea to the next level. However, if you don’t like driving around that much, it’s also possible to rent out your car to your neighbors when you’re not using it. CarNextDoor is a service that allows neighbors to ‘share’ their cars with each other, thereby offsetting the cost of ownership.   Continue Reading…

Credit Card users tired of complex points programs & value ability to redeem points flexibly: Survey

A J.D. Power survey found President’s Choice Financial are the most popular credit cards in Canada

By Hyder Owainati

Special to the Financial Independence Hub

Canadians value their credit card rewards programs. According to a recent consumer survey from J.D. Power, over 87% of the country’s credit card holders are enrolled in a rewards program, while 48% of those who switched their primary credit card in the past year did so in active pursuit of better rewards.

The survey, which polled over 6,000 credit card holders, also found that of the credit cards Canadians were satisfied with the most, the President’s Choice Financial series of cards took the top spot. American Express credit cards ranked second while Canadian Tire’s credit cards rounded off the top three. The rankings were based on customer responses to questions on a spectrum of factors that included benefits, rewards, credit card terms and customer interactions.

While the study offers an insightful look into consumers’ opinions about credit cards, it’s important to note the results were categorized based on credit card companies and don’t offer a breakdown of the individual best credit cards in Canada.

Take a brand-agnostic approach to credit cards

Consumers in search of the best credit card should adopt a brand-agnostic approach and identify the individual cards that offer the rewards tailored to their lifestyle and personal financial goals. For example, a person looking to minimize their credit debt would make a more informed decision by searching for a low interest credit card rather than limiting their card options to those offered by an individual bank or credit card issuer.

Credit cards aren’t one-size-fits-all. It’s important to never lose sight of the fact that there’s a range of options out on the market – from cash back credit cards and travel rewards cards to student cards and more. While an individual credit card, company or bank may rank high on one category or list, it doesn’t necessarily mean it’s universally the best option for everyone.

Therefore, picking the right credit card should almost always start by analyzing personal spending habits and your financial standing. That’s why at Ratehub.ca, we feature built-in calculators that allow you to compare the credit cards that offer the highest value based on where and how you spend your money.

Ask yourself these questions

A smart way for consumers to identify which type of credit card is best designed to meet their needs is to ask a few self-directed questions: How do I spend my money? How often do I travel? How quickly can I earn rewards? Do I ever carry over unpaid balances from month to month? Do I have any current debts? Continue Reading…