Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

How in sync are global Central Banks?


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Without much fanfare, the U.S. Federal Reserve (Fed) provided its policy guidance late in May. Although no rate hike was implemented [it raised its overnight lending rate by 0.25% at 2 pm today, June 13, at 2 pm: Editor]  the money and bond markets fully expect the U.S. central bank to continue on its tightening path for the remainder of 2018, if not beyond. While the lion’s share of the focus has been Fed-centric on this front, it seems like a good exercise to check in on what the expectations are for the developed world’s other key monetary policy makers.

Heading into 2018, optimism for ongoing global growth seemed to be the norm. Indeed, along with the outlook for continued global growth, discussions were arising on whether central banks would soon turn their attention to any potential increase in inflation. While we still have almost seven months to go in this calendar year, recent data appears to be suggesting a plateauing of sorts on the economic front.

One economic indicator that is widely watched for help discerning economic trends on a global basis are the various Purchasing Managers’ Indexes (PMI) on a country or regional basis. While the levels being posted in the developed world still point toward further expansion, they don’t necessarily indicate a pick-up in growth prospects on the immediate horizon. In fact, the readings for April on an aggregate basis were relatively flat, and in some cases — such as the eurozone, the UK and Canada — have actually slipped a bit from their recent peaks.

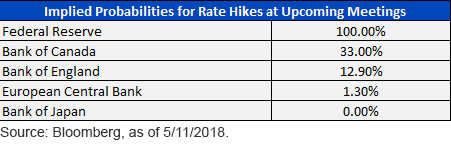
So, what should investors expect in near-term global central bank policy? As illustrated in the table above, expectations for the upcoming policy meetings certainly differ quite a bit. The overarching outlook is for the Fed to raise rates at its convocation on June 13, with the Fed Funds Futures implied probability being 100%, as of this writing. The remaining four developed world central banks — the European Central Bank (ECB), the Bank of England (BOE), the Bank of Canada (BOC) and the Bank of Japan (BOJ)  — all fall in the “no rate hike” camp. Continue Reading…
The reverse mortgage pitfalls you need to know about

Canadian seniors may borrow on their home equity in the form of a reverse mortgage — but should they?

Money lenders are always coming up with innovative ways for you to borrow money. One such innovation is the reverse mortgage. Interest in reverse mortgages is rising with an aging population and low interest rates on savings accounts. As a result, we hear from our Inner Circle members periodically asking whether a reverse mortgage would be a good way to tap into the equity they have built up in their homes.

Reverse mortgages in Canada let homeowners who are 55 years of age or older borrow on their home equity—the minimum age was 60 until a year ago. (For married couples, both spouses must be above age 55). Typically, the loan-to-value ratio is up to 40%. But depending on their age and property, some borrowers may qualify for a loan of up to 55% of the value of their home. The loan and accumulated interest are repaid only after the house is sold or from the proceeds of the homeowner’s estate.

Reverse mortgages are best seen as loans of last resort

Continue Reading…

How to develop a Financial Independence mindset if your parents were reckless spenders

By Alex Lawson

Special to the Financial Independence Hub

Our parents are our first teachers. We learn our values, our habits, life skills, relationship skills, and many other things from our parents, long before we venture out on our own.

One of the things that people pick up on is financial habits, good or bad. If your parents were reckless spenders, chances are you’re already headed down the same path. The good news is that it’s possible to change your mindset and learn to manage your finances so that you don’t make the same mistakes they did.

Separate yourself from them

The first thing you need to do is realize that you are your own person capable of making your own choices. Don’t tell yourself you’re irresponsible with money just because that’s how you grew up. Make the decision to be different and start telling yourself the opposite. Reinforce the idea that you can be financially responsible and independent regardless of how you grew up, and you’ll be able to start making better choices.

Decide on your goals

Many people that had financially irresponsible parents have never been taught to think about the future. Planning for retirement should begin as soon as you leave college. Do you think you’ll want to retire with enough money to live comfortably as you have been, or are you planning on securing complete financial independence by the time you’re 30? The process for saving and investing will be completely different based on your goals. Begin saving aggressively when you’re young so that your money will have more time to grow.

Make saving a priority

If your parents were reckless spenders, they probably didn’t teach you anything about saving. One of the biggest keys to financial independence is learning how to save properly, so that you can be prepared for both unexpected problems and for your future. Build savings into your budget before you even look at what type of housing you can afford. A good rule is to start saving 10% of every paycheck and live off what is left over until you reach the goal of three times your monthly income. Then, when your car breaks down or if you lose your job, you will have an emergency fund to rely on without having to go into debt. Continue Reading…

7 steps to Financial Independence

By Laura Martins

Special to the Financial Independence Hub

Financial Independence (aka “Findependence”) is something that many of us are working towards, but which very few actually achieve. Having a high-paying job alone does not guarantee financial independence. While making more money does make Findependence easier to achieve, the important thing to focus on is what you do with your money, rather than how much you earn.

It’s also important to understand that financial independence will take time and planning. With the right goals and steps in place, Findependence can be achieved, but it’s important to be persistent and patient.

In most cases, financial independence doesn’t mean you won’t work ever again, but it brings freedom so you can enjoy your life and work on the things that matter to you. Here are seven key steps to develop financial independence.

1.) Get to know your money

Before you can begin to work on your financial independence, it’s imperative that you know exactly what your money is doing. You must know how much is coming in, and how much and where you are spending it.

Develop a habit of checking your bank account. Ignoring it is one of the fastest ways to lose track and lose money. It might seem obvious, but developing financial independence means spending less than you earn.

Spend a few weeks or months tracking your finances and create a budget. It’s important that it’s realistic so you can stick to it.

2.) Remove non-essentials

Once you understand your finances, it’s time to find the areas where you can save more. This is one of the hardest parts on the journey to financial independence, but also one of the most important steps.

Look at your spending and assess what you don’t need. In other words, you should try to minimize your non-essential expenses. That might mean cancelling your gym membership, reducing the amount of streaming services you pay for or making more meals at home. While these things might seem small, they will all add up, and after a few months it might make a noticeable difference to your bank account.

3.) Increase your income

Now that you understand your finances and have your spending under control, it’s time to start saving more. Continue Reading…

Shopping for a Mortgage: 4 factors to consider apart from the Rate

By Sean Cooper

Special to the Financial Independence Hub

Shopping for a mortgage in the near future? The mortgage rate matters, but it shouldn’t be the only factor you consider. There are so many factors to consider, yet homeowners often get fixated on this one factor.

When you’re shopping for bread at the supermarket, you most likely don’t just shop for the bread at the lowest price. You consider other factors, such as calories, sugar and nutritional value. So why do so many people do the same thing with their mortgage?

Mortgage rates should be one in a long list of factors. Your likelihood of breaking your mortgage is a lot higher than you think. Even if you get the lowest mortgage rate, if it comes with a hefty mortgage penalty, it’s probably not worth it. Let’s look at four factors to consider besides just the rate.

1. ) Penalties

It’s not a coincidence that mortgage penalties are number one. Mortgage penalties are such an important factor (perhaps more important than your mortgage rate), yet they’re one of the most overlooked factors. Here’s a stat that may change your mind: 6 out of 10 Canadians with a fixed rate mortgage break their mortgage at an average of 38 months in. Why do they break it? For many reasons:  job loss, illness, job relocation and divorce, to name a few.

If you have a variable rate mortgage, the penalties are pretty straightforward: 3 months of mortgage interest. However, if you have a fixed rate mortgage, that’s where things get a little more tricky; and costly. You’ll pay the greater of 3 months of interest or the interest rate differential (IRD). The IRD looks at the mortgage rate your lender is charging today on a similar term mortgage. If mortgage rates are a lot lower today, then that’s when you can be hit with a hefty IRD penalty by your lender.

To avoid a hefty IRD, ask your lender whether the IRD is being calculated using the posted or discounted rate. If it’s using the posted rate, be careful. If you break your mortgage and have a big balance owing, your mortgage penalty could amount to thousands or tens of thousands.

2.)  Portability

To avoid a hefty mortgage, it helps if your mortgage is portable. When your mortgage is portable, you can take it with you. For example, let’s say you’re living in Ontario and you get a job offer in B.C. If you sell your home in Ontario and buy a home in B.C, you can “port” or take your mortgage with you and avoid the hefty mortgage penalty. If the property that you’re buying in B.C. is more expensive, lenders often let you “blend-and-extend” your mortgage, which means you take your current mortgage and blend it with a new mortgage for the additional amount of financing you need.

A word of caution: all portable mortgages aren’t created equal. There are specific conditions that must be met in order for a mortgage to be ported. Sometimes the time window is tight, so ask your mortgage broker for all the details. Likewise, if you think there’s a possibility that you could transfer outside your province, avoid portable mortgages with credit unions. Credit union mortgages can never be ported outside the province you took them out, leaving you stuck paying the hefty mortgage penalty.

3.) Prepayment Privileges

Is your goal to be mortgage-free? Continue Reading…