Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

U.S. Fixed Income: Looking at U.S. High Yield, by Default


Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Has the fixed income arena entered a new phase? While the lion’s share of attention has been given to interest rate developments for quite some time now, another topic for discussion has been where we are in terms of the U.S. credit cycle. Specifically, the debate has centered on whether the corporate bond market has entered the bottom of the ninth inning of the current cycle or whether the time frame is more akin to being in the sixth or seventh inning. Interestingly, in sticking with this baseball analogy, there does seem to be agreement that credit is not in the first few innings.

For this blog post, the focus will be on U.S. high yield (HY), particularly because if one was to see the first signs of stress, the argument could be made that this is the sector where investors should turn their attention. Over the last six months, investors have witnessed two episodes where HY spreads have visibly widened. The first of these episodes occurred during late October to mid-November of last year, when spreads rose 53 basis points (bps).1 The second occurrence was more recent, as HY differentials moved from more than a decade low of 311 bps on January 26 up to 369 bps two weeks later, representing a widening of 58 bps.2

U.S. Speculative-Grade Issuer Default Rate vs. Recessions
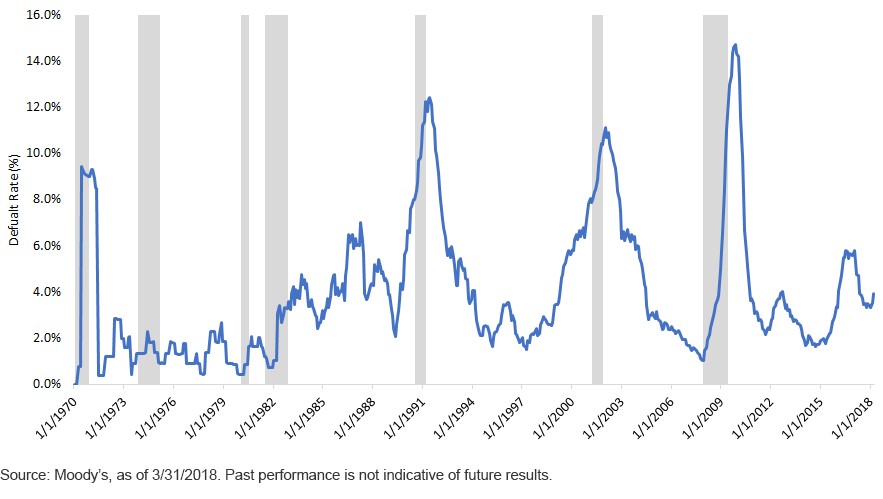
It is interesting to note that in both cases the widening trends were rather brief (two to three weeks) and of similar magnitudes. In addition, both times the sell-off was short-lived, as buyers re-emerged and compressed spreads back down.

Continue Reading…

MoneySense/Surviscor Best Online Brokerages 2018

The sixth annual MoneySense survey of Canada’s one line brokerages (aka discount brokers) is now available. Written this year by me with Glenn LaCoste, CEO of Oakville, Ont.-based Surviscor Inc., you can find the full piece by clicking on the highlighted headline: Canada’s Best Online Brokers 2018.

Qtrade Investor once again narrowly edged out Questrade as the top firm overall:

Best Overall:

  1. Qtrade Investor – 22 pts
  2. Questrade – 21 pts
  3. iTRADE – 14 pts
  4. BMO InvestorLine – 14 pts

12 firms were included, ranging from the many bank-owned discount brokerages to the still-independent Questrade. The report also looks at various categories, including Mobile, ETFs, Design & User Experience, and Fees & Service.

As you go through the separate categories you’ll see both firms often place in the top three spots: five for Qtrade and four for Questrade this time around. Qtrade was first in two categories, second in another two, and third in one; while Questrade was first in one category, second in two categories and third in one.

Methodology

The survey methodology is based on MoneySense-specific categories based on Surviscor’s latest mobile and online reviews. Continue Reading…

How to teach your children good financial habits

Special to the Financial Independence Hub

Teaching your kids sound financial habits when they’re young can help them learn to make wise choices about their money, and ease their reliance on you later.

Alison Tedford blogs about parenting at Sparkly Shoes and Sweat Drops, and at home is a dedicated mom who teaches her eight-year-old son Liam about finances, among other life lessons. We spoke with Alison as well as Jeannette Brox, CFP®, a senior financial consultant with Investors Group in Toronto, who’s affectionately called “The Money Lady” by her clients’ children.

The value of effort versus reward

To help instil a sense of the value of money in Liam, Alison enlists Liam’s help as she works on her blog and manages her social media channels, and ensures that he understands the financial value of each activity. “When he wants something, we tell him it’s the value of a blog post, or a Facebook Live video,” she says. “That way, he understands the value of the item relative to the effort he needs to put into it. Then he can make a judgement call as to whether the money should be spent or not.” When a larger contract comes in for Alison, they discuss how to use the money as a family.

This principle of making money choices can be adapted to your child’s age and situation. For example, a new iPad might be equivalent to 20 “regular” toys. Or, if your child receives an allowance, you can help them understand the length of time it’ll take to save for what they want and what they might need to give up in the meantime. It all adds up to an important money (and life) lesson about short-term compromise to reach long-term goals.

Jeanette Brox, CFP, Investors Group

In Jeanette’s practice, she gets her clients’ kids to start saving monthly at a young age. “It becomes meaningful for them,” she says. “When they get older, they understand the power of money accumulating instead of blowing it on stuff.”

She uses the same “save early and often” approach for children of different ages, although the situations will be different. “A six-year-old is excited when they’re saving to contribute to something they want. When they finally get it, they have pride of ownership.” She’s also helped kids save up for things they may want in their teenage years, such as a car, and advised teenagers who are buying sports equipment to get it off peak season to save money.

Jeanette also encourages kids to save for their own post-secondary education. “Even if parents contribute to an RESP, there may not be enough money to cover all of their university or college expenses.” And she recommends that children cover the cost of their own first year of school. “It makes them more responsible to have made that financial commitment,” she says.

Problem-solving helps form sound financial habits

Alison engages in proactive problem-solving to teach her son responsibility, even in situations unrelated to money. “For instance, it’s a common parenting challenge to have kids come to you with homework that didn’t get done that now has to get done in a short period of time,” she says.

Instead of jumping to do the task for Liam when this happens, Alison points him in the right direction by asking him to troubleshoot how he can help himself and to analyze what got him into the situation in the first place. “We look at contingency planning for the next time, such as setting reminders, tracking deadlines and so on.” Continue Reading…

Toronto vs Chicago housing: An Arbitrage for being under-weight Canadian bank stocks

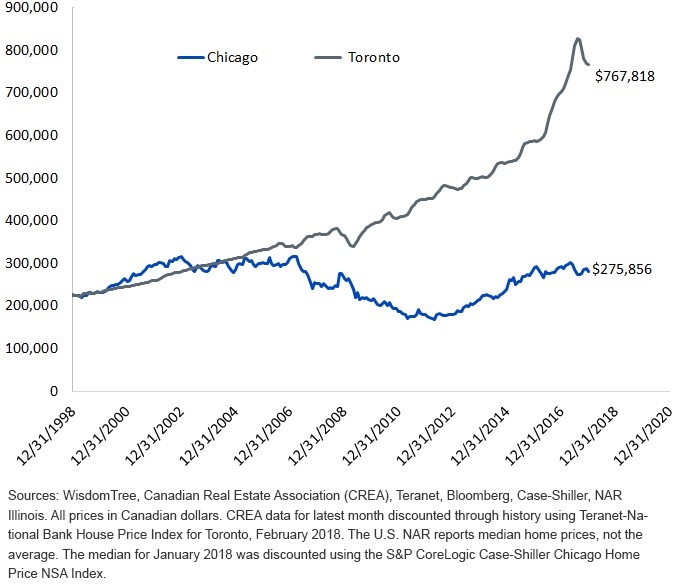
Figure 1: Chicago and Toronto Home Prices
By Jeff Weniger, CFA, WisdomTree

Of the major North American cities that feel most like Toronto, Chicago is clearly the closest fit. It’s Toronto’s sister. Chicago is the third most-populous city in the U.S., behind New York and Los Angeles. According to the U.S. Census Bureau, Chicago proper has a population of 2.7 million, almost exactly the same amount as Toronto.1 Both cities have several million more living in the immediate suburbs. Chicago’s money resides mostly on one side of the city, with most of its poverty found on the city’s south and west sides. Wealthy suburbs span almost to Wisconsin in the city’s “North Shore” suburbs, which consist of some of the wealthiest zip codes in the U.S.

Like Toronto, Chicago is a money centre. It is widely considered to be in that tier of financial hubs that includes Boston and San Francisco, behind the center of it all in New York. Its construction is dense; people take trains and buses to commute into the downtown core. Critically, as far as desirability of property goes, Chicago’s weather is miserable, just like Toronto’s. The two cities are also characterized by left-leaning politics, so there isn’t much of a difference on that front either.

When we engage Torontonians about the U.S. and Chicagoans about Canada, time and again the answer comes back: the city that is most like Toronto is Chicago.

Except in one way.

Chicago homes are one third or half of similar homes in Toronto

There is a major arbitrage just sitting there for anyone who liquidates Toronto property, hops on a 75-minute flight and purchases a mirror-image property for one-third or half the price in Chicago. Yes, Chicago is riddled with violence, but not in the neighbourhoods where someone would spend C$767,818, the average Toronto home price in February.2 In those neighbourhoods, the biggest risk is having a $500 stroller run over your toe.

Just what could C$767,818 get in Chicago?

According to the National Association of Realtors’ (NAR) Illinois chapter:

In the nine-county Chicago Primary Metropolitan Statistical Area (PMSA), home sales (single-family and condominiums) in January 2018 totaled 5,777 homes sold, down 8.0 percent from January 2017 sales of 6,277 homes. The median price in January 2018 was $224,000 in the Chicago PMSA, an increase of 7.2 percent from $209,000 in January 2017.

Converting US$224,000 to Canadian dollars at the January exchange rate of $1.231, that is C$275,856 for the median house in Chicago. Granted, U.S. housing data tends to be measured by the median, whereas the Canadian norm is to take the average, but there is still not much of a comparison; the gap is yawning, and this all started happening only in recent years. Continue Reading…

Debt avalanche vs. debt snowball: When math trumps behaviour

John and Erica Mullen are in their mid-thirties and have two young children at home. Together they earn well over $100,000 per year, but a combination of poor choices and unlucky circumstances have left them buried in debt.

Their substantial income affords them the luxury of not having to turn their life upside down by selling their home and vehicles; however, they will need to make some tough sacrifices in order to dig themselves out of this hole.

Creditor Balance Rate Payment Interest-only
Store credit card $6,800.00 26.00% $200.00 $147.34
Consolidation loan $23,000.00 8.00% $430.00 $153.34
Line of credit #1 $20,000.00 6.34% $105.67 $105.67
Tax bill $1,700.00 5.00% $200.00 $7.09
Car loan #1 $36,000.00 3.90% $460.00 $117.00
Line of credit #2 $16,000.00 3.00% $40.00 $40.00
Car loan #2 $23,000.00 0.90% $317.00 $17.25
$126,500.00 $1,752.67

After a close look at their budget, the Mullens decide they can afford to put $2,000 per month toward their non-mortgage debt. They want to know how best to allocate the extra cash so they can be debt-free faster and pay the least amount of interest.

Two popular debt repayment strategies are the debt snowball and the debt avalanche. Let’s look at each method and apply it to the Mullen’s situation:

Debt Snowball

Dave Ramsey, American author of The Total Money Makeover, suggests an unusual strategy for getting out of debt by using something called the debt snowball method.

With the debt snowball, you’re throwing math out the window, focusing instead on the psychological advantage that comes from making progress with quick, successive wins.

Related: Should you pay off your partner’s debt?

Start by arranging your debts from lowest balance to highest. It feels better to rid yourself of your smallest debt, and the idea is that the snowball effect builds enough momentum so that you’ll be more inclined to stick with the strategy on your way toward debt freedom.

This chart shows how the Mullens would use a debt snowball approach to tackle their debt. Remember, they’re throwing an extra $2,000 per month over-and-above their minimum payments:

Creditors in Original Total Interest Months to Month Paid
Chosen Order Balance Paid Pay Off Off
Tax bill $1,700.00 $7.08 1 May-15
Store credit card $6,800.00 $405.61 4 Aug-15
Line of credit #2 $16,000.00 $301.35 11 Mar-16
Line of credit #1 $20,000.00 $1,572.90 19 Nov-16
Consolidation loan $23,000.00 $2,929.50 25 May-17
Car loan #2 $23,000.00 $390.39 30 Oct-17
Car loan #1 $36,000.00 $3,270.27 37 May-18
 Total Interest Paid: $8,877.10

You can see how the strategy works: the tax loan is killed off in the first month and from there the Mullens can focus on the department store credit card, which will be paid off three months later. Altogether it’ll take 37 months to pay off all their non-mortgage debt and the total interest paid over that time is $8,877.10.

Debt Avalanche

Continue Reading…