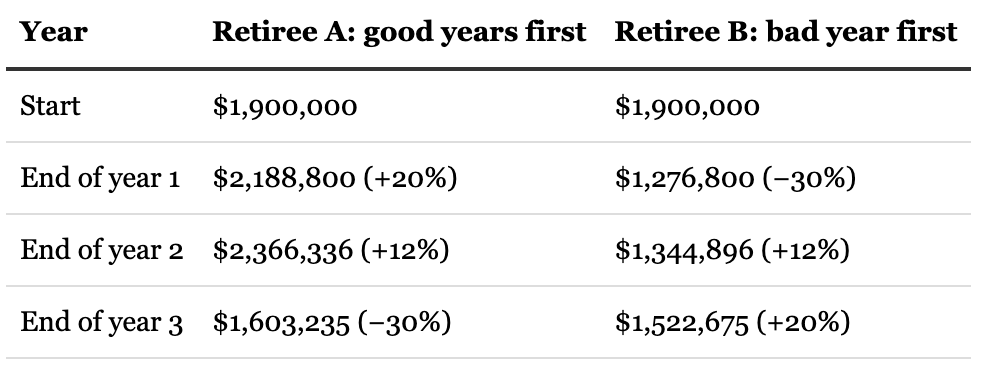Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.
Looking for consistent cash flow without the guesswork? See how Target Cash Flow ETFs are redefining cash flow investing.
Image from Pixabay
By Darim Abdullah, BMO Global Asset Management
(Sponsor Blog)
For many investors, especially those approaching or in retirement, generating consistent cash flow is one of the most important goals in a portfolio. Traditionally, that meant relying on dividends, coupons, or systematic withdrawals. But these sources can fluctuate, making it difficult to plan with confidence.
A newer category of solutions, Target Cash Flow ETFs, has been launched by BMO ETFs to help address this challenge. These strategies shift the focus from simply “earning yield” to delivering a defined cash flow outcome.
What are Target Cash Flow ETFs?
Unlike traditional income funds, where payouts depend on underlying dividends or interest earned, Target Cash Flow ETFs take a more structured approach. They aim to deliver regular monthly distributions based on a predefined annual target (approximately 6% –15% depending on the ETF)1, rather than whatever cash flow the portfolio happens to generate.
This approach aligns with the broader rise of “outcome-oriented” investing where ETFs are built to meet specific investor goals, such as generating cash flow or reducing volatility.
How do they work?
The key difference lies in how distributions are generated.
Traditional cash flow ETFs generally pay out what the portfolio earns (dividends, interest, option premiums).
Target Cash Flow ETFs aim to pay out a set amount, regardless of market conditions.2
To deliver a more regular monthly cash flow, the distribution is built using a blended funding approach. Cash flow may come from the portfolio’s natural sources of return: dividends, interest, and (where applicable) option premiums, and may also include Return of Capital (ROC). ROC doesn’t create an immediate tax liability, but it does reduce your Adjusted Cost Base (ACB) over time, which can affect taxes when the investment is sold. And if ROC isn’t offset by portfolio growth, it can gradually reduce invested capital.
That’s why it’s important to assess the strategy through a total return lens, not just the cash flow. If the portfolio’s total return stays above the distribution yield, the client’s underlying capital can still grow over time; if it’s persistently below the payout, the likelihood of capital erosion increases.
With the above payout breakdown in mind, it is worth noting that the payout levels for the T series solutions were carefully selected after examining the historical long-term returns of the parent portfolios, with the aim of minimizing the return of an investor’s initial capital as much as possible. Over the long term, the objective is for the distribution levels to be supported by the total returns of the underlying portfolios.
BMO’s Target Cash Flow offering
BMO has been an early innovator in this space in Canada3, introducing Target Cash Flow Units (often referred to as “.T series”) across a broad lineup of ETFs.
These units are available on a range of existing strategies including:
Asset allocation ETFs (e.g., all-equity or balanced portfolios)
Covered call ETFs (both dividend and sector focused)
Rather than launching entirely new funds, BMO has added a new .T series of units to existing ETFs, giving investors the ability to choose between traditional distributions and a targeted cash flow approach within the same parent strategy. I
Key Features
BMO’s Target Cash Flow Units are designed to offer: Continue Reading…
Sequence of Returns Risk: Chart by Stefano Starkel
My latest MoneySense Retired Money column touches on a number of blogs that regular readers of Findependence Hub may already have seen, but ties together a few disparate threads that may warrant revisiting. Click on the highlighted headline here for the full article: The CAPE ratio, the 4% rule and retirement anxiety.
The focus is on the 4% Rule, Sequence of Returns Risk early in Retirement, and stock valuations measured by the CAPE Ratio.
The 4% Rule is one of those Personal Finance chestnuts, a topic we explored in Retired Money as recently as late 2025 (here.) My Findependence Hub blog on the 4% Rule appeared late in July here.
Robert Shiller’s CAPE Ratio: the Cyclically Adjusted Price-to-Earnings ratio (CAPE), is a measure of how fairly valued or overvalued stocks may be. The blog on the CAPE Ratio ran late in August here. Both are under my byline: Each contains full raw quotes from a variety of business owners and investment professionals on both sides of the border, gathered on Linked In and a service called Connectively, formerly Featured.com.
A useful primer on the CAPE Ratio was provided by blogger Michael J. Wiener, on his Michael James on Money blog (from early August), also republished here on Findependence Hub in August. He says the CAPE Ratio is “just the current price divided by the average inflation-adjusted earnings over the past decade.” Investopedia defines the CAPE Ratio as “a valuation measure that uses real earnings per share over a 10-year period to smooth out fluctuations in corporate profits.” You can find more on CAPE here on Wikipedia.
See also this recent Findependence Hub blog by Stefano Starkel titled the The Alternative to the 4% Rule isn’t a different number: It’s a different mechanism. There, Starkel argues that “the fragile part of a fixed-withdrawal plan is Sequence-of-Returns risk.” He shows a chart [shown above] that demonstrates how early losses in Retirement can have a dramatically negative impact on returns and thus Retirement income.
Stay Calm
Sure, proper diversification and asset allocation should allow you to Stay Calm, which happens to be the title of a new book published early in September by David Booth: he’s a founder of Dimensional Fund Advisors (DFA), one of the better indexing companies out there. I have finished reading it and plan to review it for MoneySense in the near future.
The main principles of the DFA approach to investing is to keep costs low by minimizing trading and using passive investing vehicles like ETFs, and above all trust the markets over the long term while avoiding picking individual stocks and attempting to time financial markets.
Most Canadian investors know they need to shelter investments from taxes as much as possible but these can be taxed differently depending on which account holds them. Professionals call this Asset Location. Here’s how to optimally place them in the most tax-efficient vehicles.
By Curtis Travis
Special to Financial Independence Hub
Most Canadian investors learn the first rule quickly enough: shelter it. Fill the registered accounts before a dollar goes into a plain taxable one. It is the single most valuable habit in Canadian investing, and if you read this site you have almost certainly done it.
Almost nobody does the second step.
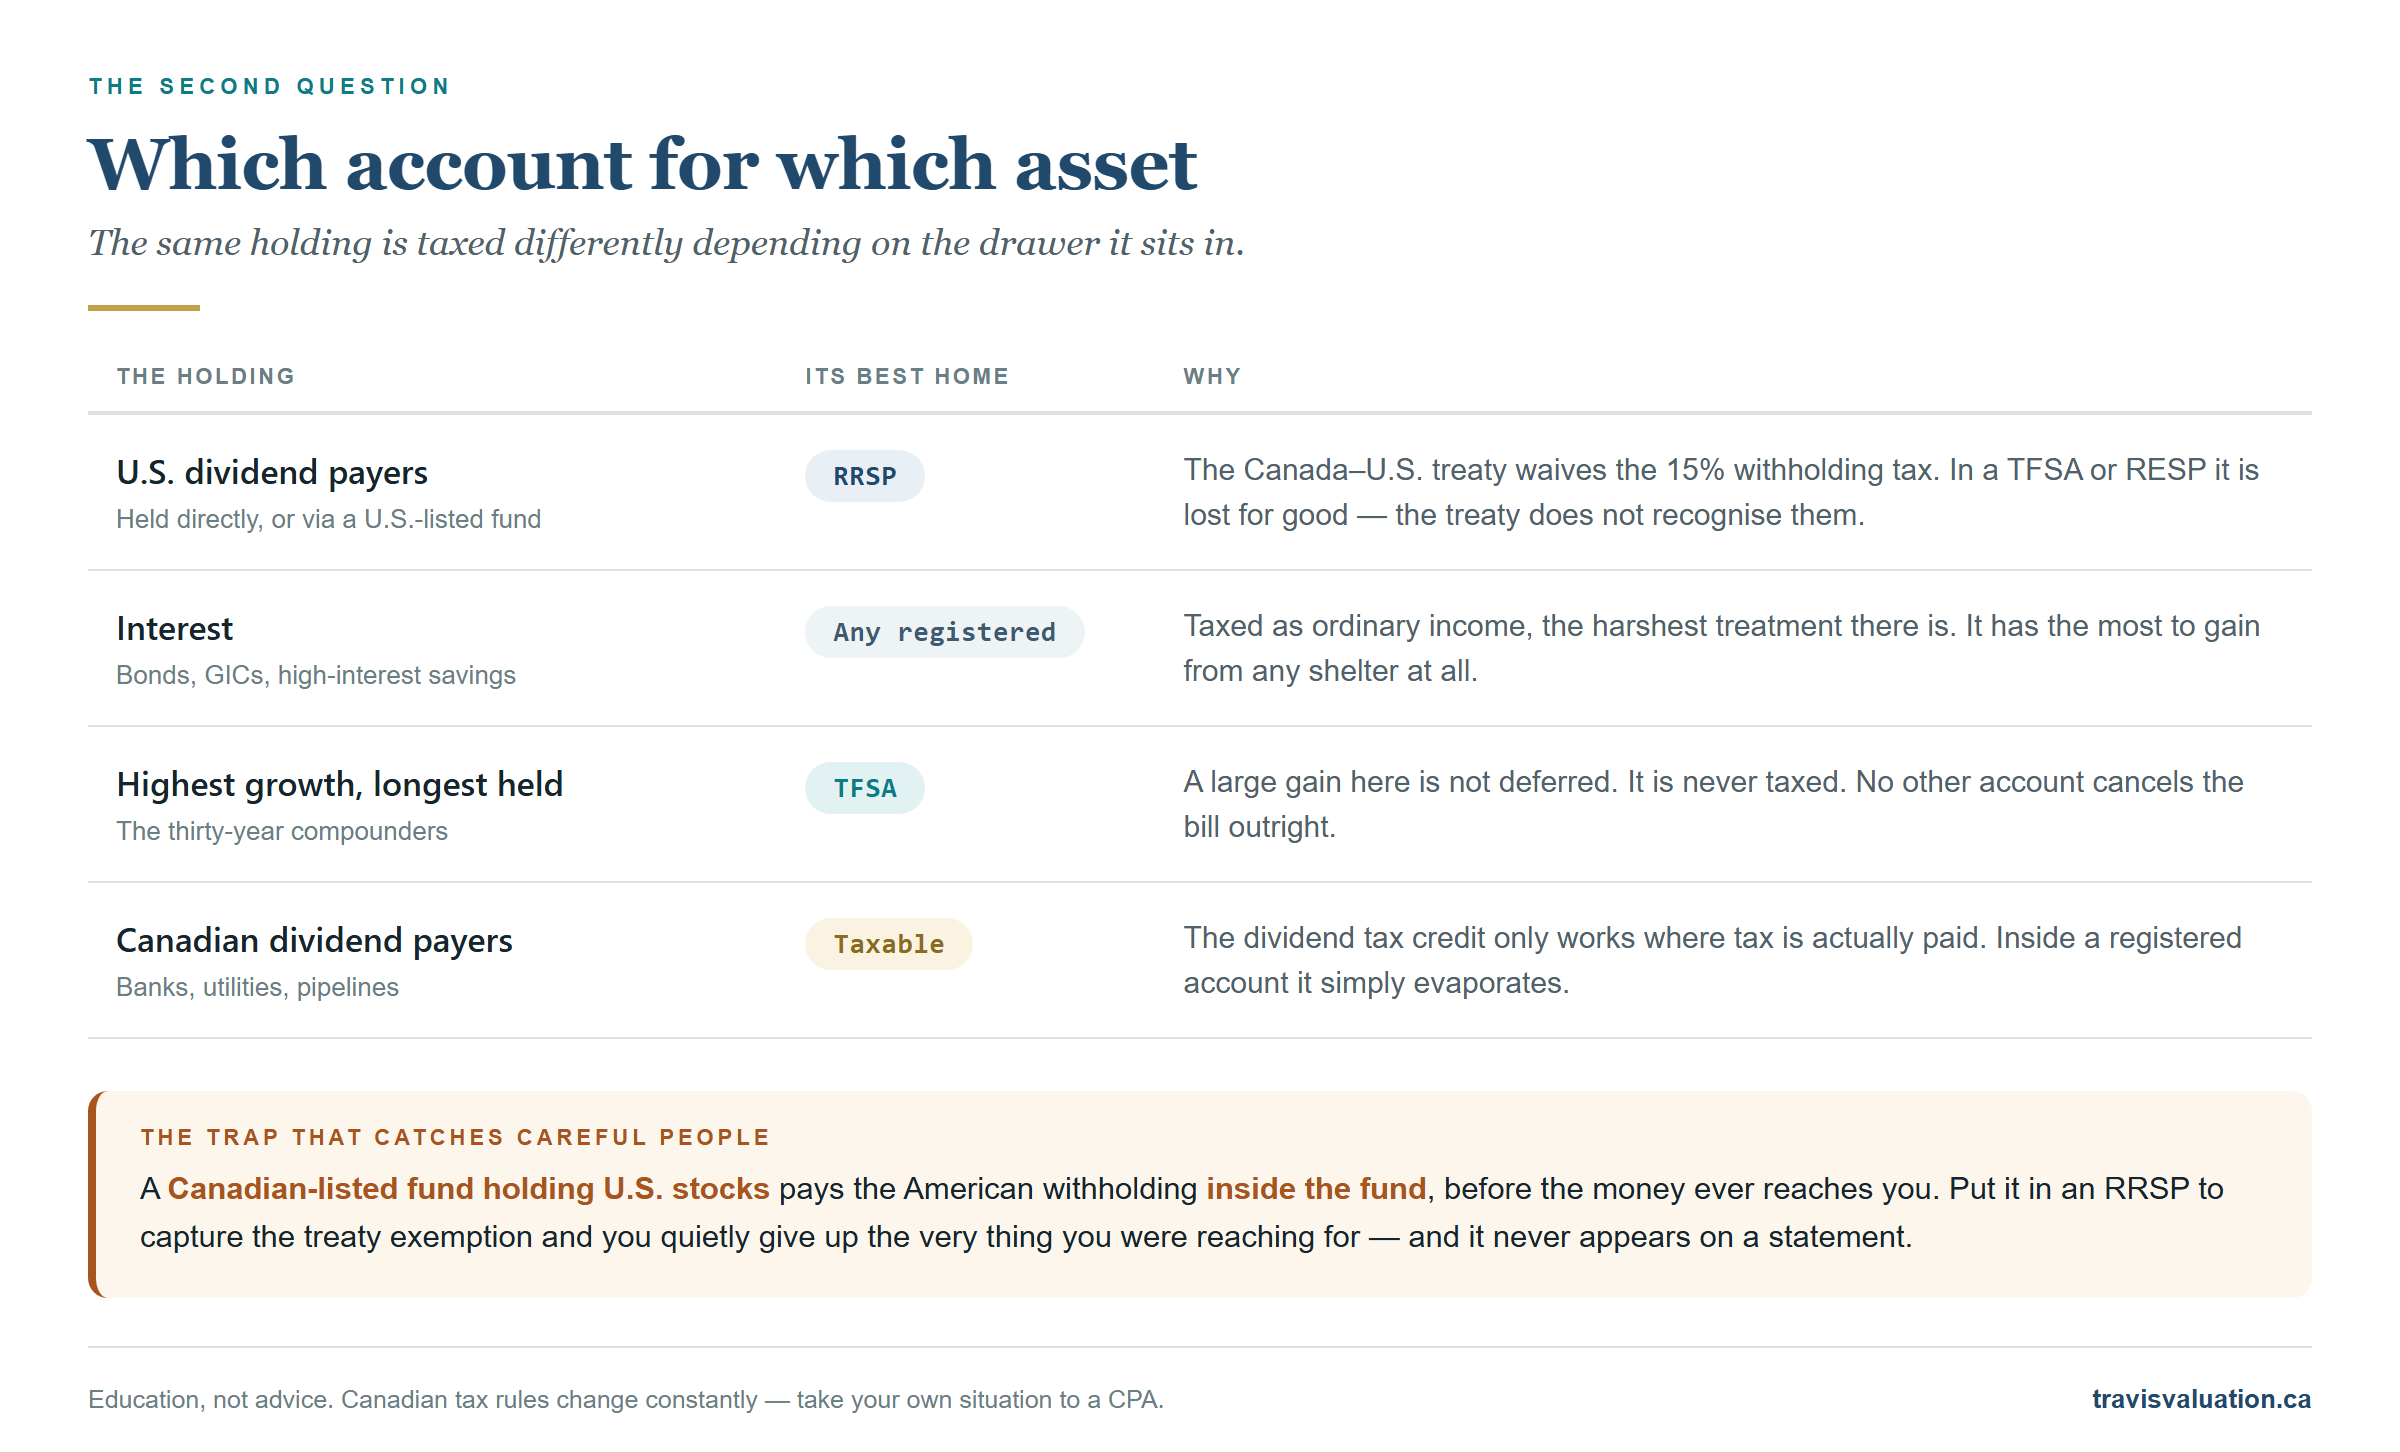
Here it is: the same investment is taxed differently depending on which account holds it. Not the same investment in a different year, or bought at a different price: the identical holding, on the identical day, taxed differently because of the drawer it sits in. Professionals call this Asset Location. It costs nothing but a few minutes of thought, and getting it backwards can quietly cost you thousands over a couple of decades.
Three facts drive the whole thing.
The first is that the dividend tax credit — the break that makes eligible Canadian dividends so gentle in a taxable account — is lost inside a registered account. A TFSA or an RRSP isn’t paying tax in the first place, so the credit has nothing to offset. It simply evaporates.
The second is that American dividends arrive with tax already taken off the top. The United States withholds 15% under the Canada/U.S. treaty. In a taxable account you can generally claim that back as a foreign tax credit. In an RRSP the treaty exempts it entirely. And in a TFSA, an FHSA or an RESP it is gone for good: the treaty doesn’t recognise those accounts, and there is no tax return on which to recover it.
The third is that interest is taxed as ordinary income, the harshest treatment there is. It has the most to gain from any shelter at all.
Line those up and a rough map falls out. Not a clever one: the kind a CPA will refine but not overturn.
American dividend payers belong in the RRSP, where the withholding disappears. Interest-bearing holdings belong in a registered account too, because they are punished worst outside one. Canadian dividend payers are the natural residents of a taxable account, where the credit actually does its work; so when registered room is tight and something has to sit outside, the Canadian banks and utilities are, for most people, the last things that need sheltering. And your highest-growth, longest-held positions belong in the TFSA, where a large gain is not merely deferred but never taxed at all.
That last one is worth sitting with. A TFSA doesn’t defer the tax on a thirty-year compounder. It cancels it.
Now the part that catches careful people.
The RRSP exemption on American dividends only applies when you hold the American shares, or an American-listed fund, directly. A Canadian-listed fund that owns American stocks pays the withholding inside the fund, before the money ever reaches you. In a taxable account that is survivable: the fund passes the tax through on your slip and the credit is still yours. In an RRSP it is simply lost, and you will never see it on a statement.
This surprises people who did everything else right. They bought a Canadian-listed U.S. equity fund, put it in the RRSP because that is where American exposure is supposed to go, and quietly gave up the treaty benefit they were trying to capture.
Where good intentions get expensive
Two more pieces of fine print, because this is where good intentions get expensive.
The RRSP is a deferral, not an exemption. Everything that comes out comes out as ordinary income: capital gains and dividends included. A gain that would have been taxed at the favourable capital-gains rate in a taxable account is taxed in full when it leaves an RRSP. The deduction you took going in is what pays for that. And by the end of the year you turn 71 the account must be wound up, for most people into a RRIF, which from the following year pays you out on a schedule whether you want the money or not.
The TFSA has three habits worth knowing. Room you withdraw comes back: but not until the following January, so a withdrawal and a re-deposit in the same calendar year can quietly push you over your limit. The penalty is a tax of 1% per month on the excess, which is not a rounding error. And a TFSA is for investing: the tax agency has taken the position, and the courts have backed it, that an account run like a day-trading business can have its gains taxed as business income, tax-free wrapper or not. Buy well and sit still and you will never meet that rule. Continue Reading…
As we aim to do roughly every month, today’s blog on Financial Independence taps the expertise of multiple business owners and investment experts on both sides of the border gathered through Connectively in partnership with LinkedIn.
This edition looks specifically at the FIRE movement, which of course is an acronym for Financial Independence Retire Early.
The paragraph reproduced below is how we posed the question.
The subsequent replies chosen are presented almost in full, with links to the source contained in their bios at the end of each section. I’ve added subheadings to speed readers through the content I hope is relevant to them.
What is your take on the FIRE movement (Financial Independence Retire Early)? Do you prefer a different term, do you believe in the FI part but not the RE part? How early is too early to “retire?” How do you define Retirement? Full-stop never work again, or just no longer being a corporate salaried employee. Any favorite FIRE blogs or podcasts you subscribe to or recommend?
“Most FIRE folks I’ve encountered don’t actually stop working; they stop working for someone else.”
Ah, the FIRE movement: where twenty-somethings eat rice and beans for a decade so they never have to attend another Monday morning meeting. I love the “FI” part with my whole heart. Financial Independence isn’t a trend; it’s just smart adulting. Building an emergency fund, crushing high-interest debt, investing consistently: that’s timeless wisdom dressed up in a catchy acronym.
The “RE” part, though? That’s where I raise a legal eyebrow. Retiring at 32 sounds thrilling until you realize you’ve got 50+ years of healthcare costs, inflation, and “what if the market tanks in year three” anxiety ahead of you. I’ve seen too many bankruptcy filings from people who front-loaded their optimism and back-loaded their income planning. So my official stance: FI, yes. RE, only if your math is bulletproof and you have a contingency plan tighter than a loan shark’s payment schedule.
How early is too early? There’s no magic number, but if you’re retiring before you’ve stress-tested your plan against a recession, a health crisis, and at least one kid’s emergency root canal, you’re retiring on hope, not strategy. I’d rather see someone retire at 45 with a fortress of a financial plan than at 35 with a house of cards.
As for defining “retirement”, I don’t buy the full-stop-never-work-again version. Most FIRE folks I’ve encountered don’t actually stop working; they stop working for someone else. They pivot to consulting, passion projects, or that Etsy shop selling hand-painted rocks. That’s not retirement—that’s career emancipation. And frankly, that’s healthier. Purposeless days can be as damaging to your well-being as an unpaid credit card is to your credit score.
Favorite resources? I keep an eye on “ChooseFI” for community-driven inspiration and practical steps, and “Mr. Money Mustache” for someone who’ll bluntly tell you to stop buying lattes and start buying index funds. But I always tell people: read these for motivation, not gospel. Your debt situation, your state’s laws, and your risk tolerance are yours alone—no blog can litigate your specific financial life like a good advisor (or attorney) can.
Bottom line: chase Financial Independence like it’s your job. Just make sure “Retiring Early” doesn’t quietly become “Filing for Bankruptcy Early” instead. — Loretta Kilday, DebtCC Spokesperson, Debt Consolidation Care
“I prefer the term Financial Autonomy.”
Financial Independence is the ultimate risk management strategy, yet the “Retire Early” label often misdiagnoses the goal as an escape from productivity rather than an acquisition of professional autonomy.
I prefer the term Financial Autonomy because it reflects a shift in capital allocation rather than a cessation of value creation. After two decades overseeing financial strategy and delivery operations, I have found that high-performing leaders rarely want to stop contributing; they simply want to stop answering to inefficient structures. Retirement should not be defined as a full-stop end to work, but as the pivot point where professional activity is driven entirely by intellectual curiosity rather than financial necessity.
The math of independence must be approached with the same discipline as a corporate balance sheet. Many proponents of early retirement rely on withdrawal models that fail to account for long-tail risks like global healthcare inflation or currency volatility across a 50-year horizon. It is too early to step away until a portfolio has been stress-tested against at least two distinct economic cycles. True independence requires ensuring that passive cash flow exceeds lifestyle burn even during prolonged periods of market stagnation.
Durable financial planning relies on economic history and financial biographies rather than the fleeting trends of modern hustle culture. Understanding how capital markets and labor value have shifted over the last century provides a more stable framework for long-term planning. The objective is to reach a stage where you are no longer a salaried employee by obligation, but a contributor to the economy by design. Sustainable returns are not just about the balance in a brokerage account; they are about the continued growth and leverage of your human capital. — Abhishek Pareek, Founder & Director, Coders.dev
“Real freedom is being able to say no to what drains you and yes to what sustains you.”
I’ve seen too many high achievers burn out chasing Financial Independence, then realize they don’t know who they are without the hustle. The problem isn’t the FIRE framework itself, it’s that people use it to escape rather than create. They’re running from burnout instead of asking why they’re burned out in the first place.
I believe in the FI part because autonomy matters. But retiring at 35 or 40 can backfire if you haven’t figured out what actually fulfills you beyond hitting achievement metrics. I think of retirement as the freedom to choose work that aligns with your values, not necessarily stopping work altogether. Some of my most miserable clients were financially independent but spiritually empty because they’d built their entire identity around accumulation. Real freedom is being able to say no to what drains you and yes to what sustains you, whether that happens at 45 or 65. — Samka Keranovic, Founder, Drwmbs
“Financial Independence is about buying your freedom to choose.”
I love the ambition behind FIRE, but I’d reframe it slightly: Financial Independence is about buying your freedom to choose, and that’s something I think about constantly running operations at Scale By SEO.
The FI part is undeniable. When you’ve built enough cushion that a bad month doesn’t sink you, you make sharper decisions, negotiate better, and sleep easier. The RE part is where I’d push back on the label, because most people who “retire early” at 35 or 40 are really just changing what they work on, not stopping work entirely.
That’s my definition of retirement, honestly: it’s not never working again, it’s never being forced to work on something you don’t care about. Full-stop retirement sounds like a fast track to boredom for a lot of driven people. The folks I admire treat FI as leverage. They leave the salaried corporate role and pour energy into something they own, whether that’s a business, a portfolio of projects, or in my world, building free tools like our customizable QR code generator because they want to, not because payroll depends on it.
How early is too early? Whenever the math only works if nothing ever goes wrong. I apply the same logic I use with clients: we back our SEO plans with a six-month performance guarantee, continuing services for free if KPIs aren’t met, because we’d rather absorb the risk ourselves than ask a small business to bet everything on hope. That’s the FIRE mindset done right, protect the downside first, then race toward freedom. If someone at 32 has a plan that survives market crashes, health surprises, and inflation, more power to them. If it only works in a spreadsheet, they’ve built a fantasy, not a plan.
For reading and listening, I’d point people to Mr. Money Mustache for the no-nonsense math and ChooseFI for the community side of the equation. Both do a great job separating hype from substance, which is the same standard I’d hold any advice to, financial or otherwise. — Melissa Basmayor, Marketing Coordinator, Freeqrcode.ai
“The financial objective, in my view, should be freedom of choice rather than freedom from all work.”
I strongly believe in the FI part of FIRE, but I am less attached to the idea that financial independence should automatically lead to retiring as early as possible.
For me, Financial Independence means reaching the point where your decisions are no longer dictated by the next paycheck. That could mean leaving a corporate job, changing careers, starting a business, working fewer hours, or simply having enough financial security to say no to work you no longer want to do.
I therefore prefer to think of FIRE as “Financial Independence, Reclaiming Employment” rather than necessarily “Retire Early.”
I do not think there is a universal age that is too early to retire. The bigger question is what someone is retiring to. Work provides more than income: routine, social contact, intellectual challenge and a sense of usefulness. If someone reaches financial independence at 40 but removes all of those things without replacing them, early retirement may not feel as rewarding as expected.
My definition of retirement is not “never earn another dollar.” It is reaching the point where paid work becomes optional rather than compulsory.
The financial objective, in my view, should be freedom of choice rather than freedom from all work. — Cem Oner, Founder / Finance & Public Data Publisher, Hesap Cebimde
“My definition of retirement is not ‘never work again.’ It’s never being forced to work again. Huge difference.”
I’m a believer in the FI part, one hundred percent. The RE part is where I push back, and here’s why: I built Scale By SEO from scratch, and I’ve watched consistent effort compound the same way money does. Walking away from work you love at 35 to sit on a beach sounds like quitting a marathon at mile twenty because your legs feel fine.
My preferred term is “Financial independence, work on your terms.” The money buys you optionality, not an exit. It means you take a client because you want to, not because rent is due. That’s the real win.
How early is too early? There’s no magic number, but too early is when you retire from something instead of to something. If you don’t have a reason to get up in the morning that isn’t a paycheck, the money won’t fix that. I’ve watched business owners sell out and go stir-crazy within a year. Purpose doesn’t have a price target.
And my definition of retirement is not “never work again.” It’s never being forced to work again. Huge difference. I run an SEO agency out of Harlingen, Texas, and I genuinely enjoy helping small businesses, plumbers, healthcare practices, auto body shops, get found online. Would I stop doing that because a portfolio hit a number? Absolutely not. Work you choose is one of life’s great pleasures.
On resources, Mr. Money Mustache is still the best voice in the space, and his writing is funny on top of being smart.
The ChooseFI podcast is my go-to for practical tactics, and JL Collins’ “The Simple Path to Wealth” is the book I’d hand anyone starting from zero. His stock series alone is worth hours of your time.
One warning: the FIRE crowd can obsess over the math and skip the meaning. Independence is a tool. Decide what it’s for before you chase it. I’d rather be sixty and excited about my work than forty and bored on a beach. — Wayne Lowry, CEO, Scale By SEO
“Buy the freedom, skip the recliner.”
Buy the freedom, skip the recliner. That’s my FIRE philosophy in one line, and I think it’s the healthiest version of the movement.
I buy the FI part completely. Financial Independence is just margin in your life: low overhead, real savings, the ability to say no. Running a small roastery teaches you that fast. Since Craig Keel founded Equipoise Coffee in 2021, every day has been about prioritizing when resources are tight. Do we spend on another single-origin like the Ethiopian Yirgacheffe, or on brewing guides that help people make better coffee at home? Margin is what lets you make those calls from strategy instead of panic. Personal finance works the same way.
The RE part is where I’d edit the script. I prefer “financial independence” plain and simple, maybe “financial autonomy,” because “retire early” sells an ending when most people actually want a beginning. I define retirement as the point where work becomes a choice rather than an obligation. By that definition, I know plenty of “retired” people who work more passionately than any salaried employee, and plenty of employed people who retired emotionally years ago.
How early is too early? When you’ve funded decades of pure consumption with nothing you’re building toward, you’ve traded one imbalance for another. Our whole brand philosophy is balance, in the cup and in life. A coffee that’s all brightness and no body falls flat, and so does a life that’s all freedom and no purpose.
On resources, Mr. Money Mustache is the classic and still worth reading, less for the math than for the “build the life you want, then save for it” ethos. ChooseFI is a solid podcast with a wide range of guest stories worth sampling.
So if FIRE means engineering the freedom to do work you love, I’m all in. If it means never working again, that just sounds like a long, quiet fade. — Rory Keel, Owner, Equipoise Coffee
My honest take: the “FI” half matters far more than the “RE” half
My honest take: the “FI” half matters far more than the “RE” half — the math (25 times your annual expenses, per the 4% rule) doesn’t care whether financial independence means quitting work entirely or just no longer needing the paycheck, and that distinction gets lost when people fixate on “retiring early.” I’d define retirement less as “never earning another dollar” and more as your paycheck becoming optional — once a portfolio can sustain a lower, safe withdrawal without more contributions, working becomes a choice about meaning rather than survival. The lever that actually moves someone’s FIRE date isn’t income, it’s savings rate: saving 10% of your income buys roughly one year of retirement for every nine years worked, but push that to 50% and it gets close to one-for-one, a bigger shift than most raises ever deliver. I build the free FIRE and compound-interest calculators at TheSmartWealthTools.com, so I watch that one input move people’s timelines by decades more than any other number on the page. — Haggai Tzouk, Founder, TheSmartWealthTools.com
Financial Independence is real. The “retire early” part is where people lose the plot.
I’m Runbo Li, co-founder and CEO of Magic Hour. The FIRE movement gets the diagnosis right but the prescription wrong. Financial independence is real. The “retire early” part is where people lose the plot.
I watched my parents run small businesses my entire life. They never talked about retirement. They talked about freedom. Freedom to pick which problems they wanted to solve, which customers they wanted to serve, which days they wanted to work. That’s a fundamentally different orientation than “stop working as fast as possible.” Continue Reading…
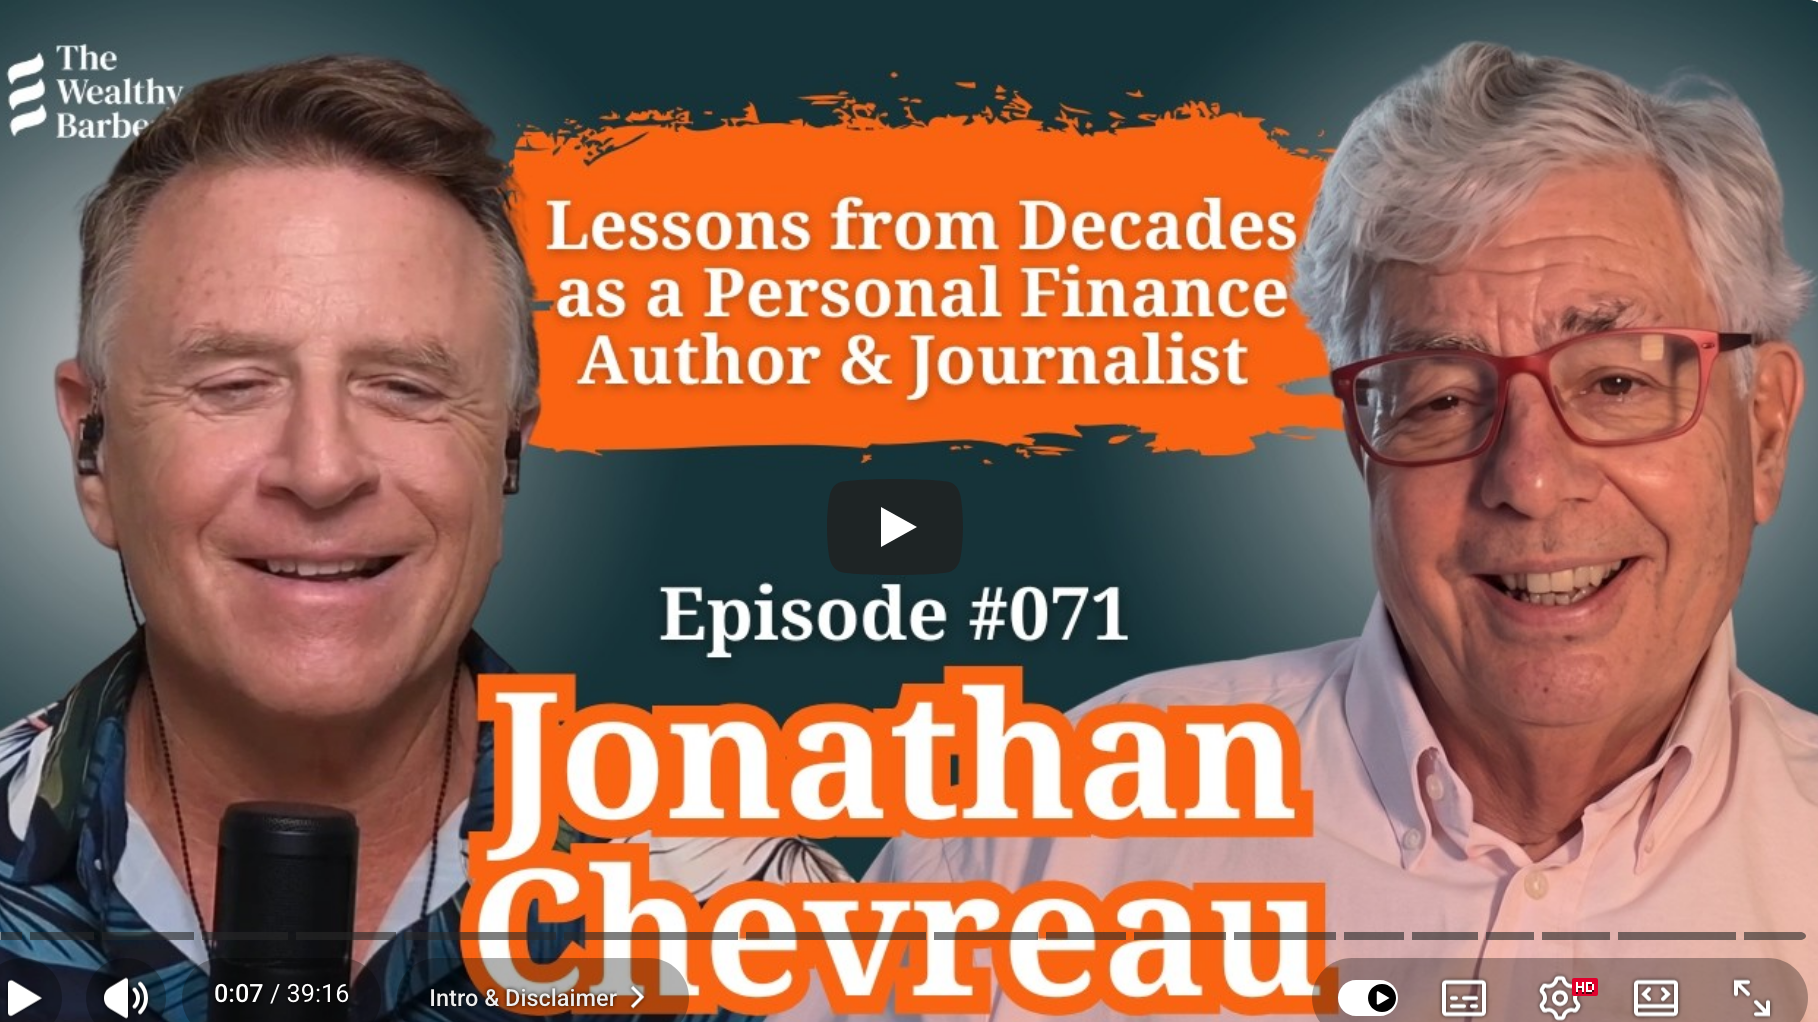
As those who follow me on social media may already know, financial guru David Chilton interviewed me on his popular The Wealthy Barber podcast, which dropped Tuesday on YouTube.com. You can find the full 39-minute clip here: try 1.5x speed if you’re pressed for time!
David is a good interviewer and got me to confess a few things I might not have coughed up otherwise. Mostly, we chatted about personal finance in Canada, retirement and retirement planning and — a particular concern for David — the plight of young Canadians priced out of the Canadian real estate market. This included a discussion of our own family’s situation and how the “Bank of Mum and Dad” may be enlisted to supplement down payments scraped up by some combination of TFSAs, the RRSP Home Buyers Plan and the new First Home Savings Accounts (FHSAs) that David is quite enthusiastic abøut.
Naturally we talked about Retirement. David himself is retiring at the end of this year soon after he turns 65, so he will have “beaten” me to Full Retirement by roughly eight years. I wrote about his looming Retirement recently in my MoneySense Retired Money column, which was also flagged here on Findependence Hub.
A Who’s Who of Canadian Personal Finance
I was David’s 71st interview on the podcast since he launched it two years ago: he says he plans to keep it going at least until the end of this year. As I comment in the interview, his many guests constitute a veritable “Who’s who” of Canadian personal finance, with a handful of Americans thrown in.
Glad to be part of it and to join such luminaries as Ben Felix, Preet Banerjee, Rob Carrick, Fred Vettese and many more. As David notes, a lot of his guests are younger newer voices known as “Finfluencers,” a group I also wrote about in Retired Money earlier this summer.
We also discuss other more “seasoned” financial commentators, including Bruce Cohen, Ellen Roseman, Jim Daw, Mike Grenby and other pioneers of the genre. Some of those veterans’ names came up in another Retired Money interview I did after Rob Carrick retired a year ago from his full-time job at the Globe & Mail.
The financial novels spawned by The Wealthy Barber
With an estimated 4- to 5- million copies of his books sold worldwide, it’s no surprize that Chilton’s pseudo-fiction financial format spawned many imitators. I fondly recall Jim Daw (retired from the Toronto Star) cracking a joke about the many financial novel knockoffs inspired by The Wealthy Barber. Rather than a “branch” of personal finance literature, Jim quipped in his review of my own Findependence Day that this specialized field consituted merely a “twig” of the genre.
While much of the interview was perforce about investing and retirement, good interviewer that he is David manages to coax some confessions about my own lifestyle and choices. For example, I tackled headon the fact that the title of my own similarly titled The Wealthy Boomer was not initially conceived as a ripoff of Chilton’s far more commercially successful The Wealthy Barber: that title was just a description of the possible demographic target for the book’s publisher.
We also talked about 12 Good Years, the blog that blogger Fritz Gilbert originally ran on his Retirement Manifesto blog. That article make she case that new or aspiring retirees should strive to make the best of the years between ages 60 and 72, whether for strenuous travel or demanding hobbies, physically or mentally. Continue Reading…


 Posted By
 Posted By