General

How bad advice on Defined Benefit plans could cost you your retirement

The following is a guest post by financial planner, author and pension expert Alexandra Macqueen, which originally ran on Dale Roberts’ Cutthecrapinvesting blog on Feb. 26, 2020. Because they both consider it such an important subject, they have given us permission to re-publish on the Hub. While an overview, it can serve as the ultimate guide to defined benefit pension planning. And mostly, Alexandra outlines the pitfalls and the importance of finding a true and qualified pension expert.

By Alexandra Macqueen, CFP

Special to the Financial Independence Hub

If you’re a Canadian facing a decision about staying in or leaving your defined-benefit pension plan, it might be one of the highest-stakes choices you’ll ever make: the amounts you’re considering can be high – worth as much as your house, or even more – the timeline short, the tax consequences significant, the details complex, and the outcome irreversible.

Over the course of my financial planning career, I’ve encountered, unfortunately, more than one pension decision gone wrong. Just how many ways can a pension decision go off the rails? Here are five “pension pitfalls,” drawn from real-live cases that have crossed my desk in the last year or so, along with the lessons Canadians who are facing this decision can glean.

Pitfall Number 1: Unbalanced advice

It is widely understood that defined-benefit pension plans cover what’s called, in the financial planning world, “longevity risk” – or the chance of living longer, even much longer, than you expect. Defined-benefit pension plans protect against the risk of living very long by providing lifetime income.

In exchange for covering off this risk, however, if you die sooner than expected, the pension payments may stop (depending on whether you have a surviving spouse or other beneficiary, and whether your plan provides guaranteed payments for a specified term).
Image by Gerd Altmann from Pixabay

One of the most misleading financial plans I ever encountered – it was just one page, and written in Comic Sans font – outlined the “pros and cons” of staying in a defined-benefit plan. Under “cons,” the planner had listed “mortality risk,” which they defined as the risk of dying relatively shortly after starting to receive monthly pension income.

Here’s what they meant by “mortality risk:” Let’s say you’re facing a pension decision between, say, receiving a lump sum of $750,000 if you “commuted” your entitlement under the plan today, versus $3,500 per month for as long as you’re alive – and you’re wondering about what happens if you die a few years after starting the pension. (“Commuting” your pension entitlement means taking the assets out of the plan as a lump sum today, typically to manage on your own.)

In this situation, and with “mortality risk” presented by the advisor in this way – as equally balanced with the probability of living a long time – it can be very tempting to think that the best option is to “take your money and run.” Maybe you’ll die “early,” you might think – and if you do, you’ll leave an estate!

However, this “financial plan” simply listed “pros and cons” of staying in the defined-benefit plan, without considering the probability of either outcome. If we use the projection assumptions provided for Certified Financial Planners® to reference in preparing financial plans, we can see that a woman aged 65 today has a 50% chance of living to age 91, and a 25% chance of living to age 97, while a man aged 65 today has a 50% chance of living to age 89, and a 25% chance of living to age 91 (see page 13 of the linked document).

Longevity risk vs mortality risk.

Instead of this guidance, however, in this plan the chance of “living” (longevity risk) and “dying” (mortality risk, although you won’t be able find anyone else using this term in the way this advisor did) were presented as equally-weighted possibilities, with no discussion of the likelihood of living to an advanced age.

While a discussion of the impact of dying “early” on pension outcomes is appropriate, this probability should be contextualized – not simply listed as a “con” of staying in a defined-benefit plan, and implicitly characterized as “just as likely” as living to an advanced age.

Pitfall Number 2: Inexpert advice

In this case, a member of a “gold-plated” pension plan (think large sponsoring organization and top-of-the-line pension plan features, such as inflation protection) was going through a divorce, and needed to find a way to equalize assets with a soon-to-be-ex-spouse.

As is not unusual for members of defined-benefit pension plans, the member didn’t have significant other assets. In order to meet his financial obligations, and guided by a financial advisor, he decided to commute his plan entitlement and use the freed-up cash to make an “equalization payment” to his ex.

Unfortunately, neither he nor the advisor really understood the tax consequences of this choice. Because of the size of the plan’s commuted value, the client was unable to shelter much of the paid-out lump sum from immediate taxation, meaning he had a very significant tax bill when tax time rolled around. (That’s because the amount of the commuted value was well in excess of the Maximum Transfer Value set by the Income Tax Act, which specifies how much of that commuted value can be sheltered from immediate taxation.) Continue Reading…
What if market fear is the real epidemic?

A month ago, a relatively small number of people had heard about the CoronaVirus (since re-named COVID-19) and few people cared about it.  In the past couple of weeks, the spread of the virus – and the damage it has done and is likely to do in terms of:

  • Public health;
  • Faith in institutions;
  • Faith in political leaders, and of course;
  • Faith in capital markets

– is already enormous.  Many people think the trouble is only just starting.  I’d like to propose a potentially mind-blowing scenario: what if the stock market declines we have seen lately are merely a variation on the theme of what a virus can do?  If you’ve ever read Malcolm Gladwell’s The Tipping Point, you’ll know that some ideas spread a bit like viruses.  Why not the “idea” of a market decline?

Robert Shiller is a Nobel prize winner and a professor at Yale University in New Haven, Connecticut.  He has written and/or co-written several influential books about finance.  One of those books, Irrational Exuberance, posits that many markets (localized real estate markets, for instance) can be influenced by the feedback loop of human behaviour.  In other words, some people do certain things in response to others doing certain things.  As an example, panic selling might beget more panic selling.

There are lots of people who would have us believe that this is simply not the case and that markets are highly efficient.  Shiller provides ample evidence that a virus like response is very much analogous to what markets are doing.  Just as a disease can be identified, monitored, presumably contained …. and then pow! We have a major pandemic on our hands, so, too, can capital markets languish for a bit and then drop precipitously.

I’m no expert on diseases, but I’m fascinated by various aspects of behavioural economics and I find both Shiller’s evidence and his reasoning to be sound.   In practical terms, that means markets are likely to keep on dropping as long as people are fearful that they’ll keep on dropping.

Some people will want to get out (grab their supplies, get into quarantine) before the “big one” (a drop of 20%, 30%, 40% or more) occurs.  To be clear, however, this is not about what I think personally.  It’s about what your hairdresser, lawyer, real estate agent, school superintendent, insurance representative, health care provider and dozens of others think as a matter of general gut feel consensus.

Greater fool theory suggests that it may be shrewd to buy high and sell higher.  It works in reverse, too.  Sell now before the bottom falls out.

John De Goey, CIM, CFP, FP Canada™ Fellow, is a Portfolio Manager with Toronto-based Wellington-Altus Private Wealth Inc. This blog originally appeared on the firm’s “Newswire” site on March 2, 2020 and is republished on the Hub with permission.

Coronavirus and its impact on Markets and Travel

Let’s talk about last week. Unless you were living under a rock, which in hindsight might not have been a bad idea, you couldn’t help but notice that North American stock markets suffered their worst week of losses since the financial crisis. Global economic fears triggered by the outbreak of coronavirus disease (COVID-19) caused the S&P 500 to fall 11.5 percent, while Canada’s TSX dropped 8.9 percent this week.

My own RRSP shed $15,000 – or 8.18 percent. Fear and speculation was rampant in the media, with several pundits predicting further losses and that the worst is yet to come. On the other side we had the ‘buying opportunity’ crowd. You know, the ones who endlessly crow about stocks being on sale and going bargain hunting. So annoying.

Then there’s me, sitting here with no bonds to sell and no unused RRSP contribution room. Sad.

A market sell-off of this magnitude has a real psychological effect on investors, no matter their age and stage. Retirees, or soon-to-be retirees, are undoubtedly concerned when their nest-egg takes a 10 or 15 per cent hit. Investors still in the accumulation stage might be re-thinking their investment strategy as they watch their portfolio decline in value.

Let me remind you that a 10-15 per cent correction is well within the normal distribution of returns. It happened in late 2018, and in August 2015, and again in August 2011. This is not new, so ignore any headlines that claim to say ‘this time is different.’

Coronavirus and the Markets

So what’s an investor to do? This is a good time to remind investors that the money invested in their portfolios should have a time horizon greater than 3-5 years (ideally 10+).

It’s a good time to remind investors that their asset allocation should reflect their actual risk tolerance, not just their perceived tolerance when markets are performing well.

Finally, it’s a good time to remind investors that timing the market is incredibly difficult and so the best course of action in these volatile times is to stay the course and stick to your plan.

What that means is tuning out both the bearish pundits and the annoying ‘stocks are on sale’ investors. I say that about the latter because normal investors can get a serious case of FOMO [Fear of Missing Out] or just feel plain dumb if they don’t have a sensible way to add to their investments during this sell-off.

Let me be the first to tell you that it’s perfectly okay to stick to your regular contribution schedule, or to not contribute at all (just stay invested). All of the great buying opportunities in history come at times when few investors are truly in a place or frame of mind to double down on their stock investments. You’re not missing out.

Here’s some perspective to consider. North American markets have basically retreated to October 2019 valuations. Ask yourself how you felt about your portfolio in October of last year? Probably pretty darn good.

Now ask yourself if markets were completely flat for four months between October and February would you still feel this sense of fear and dread? Likely not. After all, investors have been fortunate to participate in 10+ years of nearly uninterrupted gains. You’d forgive the markets for going sideways for a few months.

Instead, we got a steady climb of investment gains for four months, followed by a fast and furious tumble in the past week or so. That’s just the markets doing what they do.

It’s also another good time for a reminder of an age-old fallacy: the idea that investors can get out of the market and wait for things to settle down. When exactly have markets been calm and consistent? How about never. Continue Reading…

Do Americans want Free Health Care or complete Student Loan Forgiveness?

A LendEDU study shows more Americans want free health care than student loan forgiveness. Free health care is a big plank for Democratic presidential candidate Bernie Sanders.

By Mike Brown

Special to the Financial Independence Hub

In Canada, the debate over health care isn’t nearly as fiery as the one that is going on within the confines of its southern neighbor, the United States. 

That is because Canadian citizens and permanent residents already have access to public health insurance that alleviates them from paying for health care services most of the time. 

But in the U.S., the debate rages on, especially with 2020 being a presidential election year. 

This election cycle is no different than any other one in recent memory because health care is once again a core issue amongst the candidates and constituents. Plans from both sides of the aisle range from maintaining the status quo to free universal health care. 

What is different about this year’s presidential election is the much greater emphasis that is being placed on the student loan debt crisis and the growing cost of higher education. 

Whereas before these joint-issues would have rarely been discussed at debates and rallies, they are now amongst the most discussed topics. 

And it’s easy to understand why; in the U.S., the total outstanding student loan debt figure is now roughly $1.61 trillion, which makes it the second largest class of consumer debt in the country behind mortgage debt. There are 44.5 million student loan borrowers and recent ones owe $28,565 in student loan debt. 

Student loan debt has gotten so out of hand in the U.S. in large part due to the ever-inflating cost of college tuition, which has outpaced the inflation rate by at least three times. Whereas the average cost of college in Canada for a Canadian citizen costs around $5,000 per year, it costs between $20,000 and $50,000 per year for an American attending college in the U.S. 

So, both health care and student loan debt plus the cost of higher education will be issues that weigh heavily on the minds of American voters in the 2020 presidential election. 

With this in mind, LendEDU, a personal finance company, conducted a survey of 1,000 Americans of voting age to gauge their preferences on the two topics. 

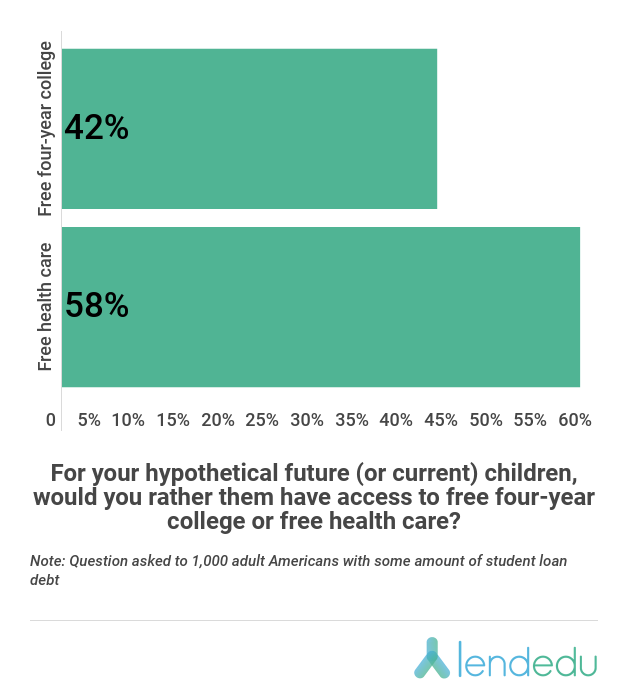
60% of Americans prefer free Universal Health Care to complete Student Loan Debt Forgiveness

LendEDU’s survey first asked respondents the following: “Would you rather have the United States’ $1.61 trillion in outstanding student loan debt be completely forgiven or have a free health care for all policy be implemented in the U.S.?”

reembargolifted(1)


While 40% of poll participants opted for complete student loan forgiveness, the majority (60%) still wanted free universal health care instead.

In terms of cost, forgiving the nation’s student loan debt would cost somewhere around $1.61 trillion, while free universal health care would cost anywhere from $25 trillion to $36 trillion over 10 years. Further, while the average student loan debtor owes $28,565 in student loan debt, the average cost of health insurance was $18,764 for the average American family in 2017, with $5,714 of that coming from out of the pocket.  Continue Reading…

RRSP deadline today: Choosing between a TFSA and an RRSP

By Micheal Davis, H&R Block Canada

Special to the Financial Independence Hub

The registered retirement savings plan (RRSP) contribution deadline is today!

Many Canadians may be making last-minute contributions before the deadline of midnight March 2nd  in hopes of unlocking a bigger tax return [if investing online; if at a physical branch, you need to act during business hours — editor.]

In fact, a recent survey from H&R Block reveals that 32 per cent of Canadians plan to contribute to an RRSP this year, a six per cent increase from last year where only 26 per cent of Canadians reported their intentions to contribute.

While RRSPs can offer tax advantages to help you reach your savings goals, it’s also important to note that they aren’t the only option available.

RRSPs vs. TFSAs

While RRSPs – a tax-deferred retirement savings vehicle in which contributions are tax deductible – can be a great investment, you do have to pay income taxes when you withdraw money, which makes this option a bit less flexible should a sudden need to access your funds arise.

Another investment tool to consider is the tax-free savings account (TFSA). Because TFSA contributions are made from after-tax income, the TFSA is a simpler tool in that it allows your investments to grow tax-free. And, since taking money out of it has no tax consequences, it can be much more flexible.

How to decide between these two investment options

The main differences between the RRSP and TFSA are their contribution limits, withdrawal restrictions, and how and when you pay taxes. Both are investment vehicles that can shelter taxes on your investments, but depending on your circumstances, one might suit you better than the other. Continue Reading…