General

Suze Orman and the FIRE movement

Photo by QuinceMedia on Pixabay

By Aaron Burdick

Special to the Financial Independence Hub

In a recent interview, Suze Orman provided her opinion about the FIRE (Financially Independent, Retire Early) movement. However, in doing the social media interview, her words were probably taken out of context, and triggered a viral reaction. Everything from Orman being a “shill for the financial industry” to “she doesn’t really want people to be financially independent at all” was thrown around. No surprise, Orman had to step out quickly and put clarity into her words.

First off, Suze Orman makes a point that she’s been advising people to be financially solvent and independent for decades, so she has no outright gut opposition to the idea. Period. But she does add that there should be a balance between spending and saving as well, which is an entirely different idea. Frankly, it’s more about balancing our satisfaction interests versus what we really need to survive and live comfortably. But where the heartburn really kicks in for Orman is on the topic of retiring early. For her, it’s a bit like quitting your job early but having no idea how to pay for health insurance until you reach the age to get Medicare, avoidable and dumb.

What is the Definition of Retirement?

So, it comes down to definitions first. If we are talking about true retirement, for Orman that means stopping working for income altogether. There is no odd job, or a part-time job, or a different job operating a lathe machine; it’s just not working at all for any profit. Second, retirement under the FIRE definition could be 55, but it could be as early as 30 or 40 as well. For the financial planner that Suze is, mathematically, that was pretty much impossible unless one was a millionaire or won the lottery. Mainly, the problem has to do with the fact that people are living really long, and that translates to tens of thousands of dollars needed annually to survive on. Quitting work at 40 or even 50 is just ludicrous.

FIRE’s Definition of Retirement

As it turns out, however, FIRE’s definition of retirement isn’t a complete cessation of retirement. Instead, it involves switching from what you have to do for a paycheck to what you want to do and still earn an income doing it. No surprise, without that clarification, Orman’s original response was not just “no,” but “hell no!” And that caused a kerfuffle on the Internet. In fact, the revised definition is entirely inline with Suze Orman’s general advice direction, pushing people to find what they love doing, but still, earn an income doing it. Some call it FIRE, and Orman calls it Living on Your Own Terms.

So there is commonality with the clarified version of FIRE and Orman’s advice categories. The detail then comes into the “how,” the method used to get from what you have to do for a paycheck to what you want to do. FIRE doesn’t necessarily detail these steps; that’s left up to the user to figure out. This is where Orman finds a gap in the philosophy.

Orman’s Take on Retirement

For Orman, retirement and individual financial independence aren’t about making enough money to quit a job. It’s about keeping stable while finding a life direction more in line with your interests, goals, wants, and happiness. Just getting to retire early with a lump of money isn’t going to translate to happiness per se. And, going back to her financial math, it’s a high risk for even more problems and unhappiness. So, Orman’s not against FIRE per se; but she has an issue with its lack of detail and in that respect, being misleading.

Aaron Burdick is a blogger and personal finance enthusiast with slight “addiction” of planning and organizing whether it’s budget, business or just life in general. Finances, real estate, budgeting and new technological solutions are not the only talking points, that he has his heart set on. Passionate about life. he studies and writes about environmental changes, human rights and quality of life. He is also the proud owner of a Golden Retriever. When he’s not writing articles he’s with his best friend playing fetch or cycling around the streets of Louisville. 
Is your neighbourhood in a Sellers’ Market for homes?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

Deciding whether or not to get into the real estate market? While budget, location, and home type will be among your top considerations, there’s another metric that can help inform your move: the buyers’ conditions in your desired neighbourhood.

Understanding whether you’ll be dealing with a sellers’, buyers’, or balanced market is key to crafting your offer or listing strategy. Those trying to buy a home amid tight sellers’ conditions will need to be ready to participate in bidding wars, for example, make aggressive bids, and be prepared to drop offer conditions to be competitive. Entering a buyers’ market indicates more real estate inventory and choice for buyers, and often the room to negotiate.

Sellers are also wise to take these conditions into account as listing during a relaxed market may mean adjusting pricing expectations; it could be a better idea to wait for the market to firm up before trying to sell your home.

What is a Sellers’ Market?

But what actually classifies a market as buyers’, sellers’, or balanced? A common misconception is price. However, while prolonged conditions will eventually influence home values, a buyers’ market doesn’t also indicate better affordability, and vice versa. Rather, these conditions are determined by a metric called the sales-to-new-listings ratio (SNLR).

The SNLR is calculated by dividing the number of sales by the number of new listings within a specific housing market over a period of time. It reveals how many of the homes listed for sale are selling within that time frame, and sheds insight into how competitive the market is for buyers and sellers. According to the Canadian Real Estate Association (CREA), an SNLR between 40  to 60% is considered a balanced market, with below and above that threshold indicating buyers’ and sellers’ conditions, respectively.

Getting the Bigger Picture

A great thing about looking at SNLR is you can get as local as you need to with your market assessment; a buyer or seller can understand what’s happening at the neighbourhood level, whether they’re looking for condos for sale in downtown Toronto, or Etobicoke homes for sale.

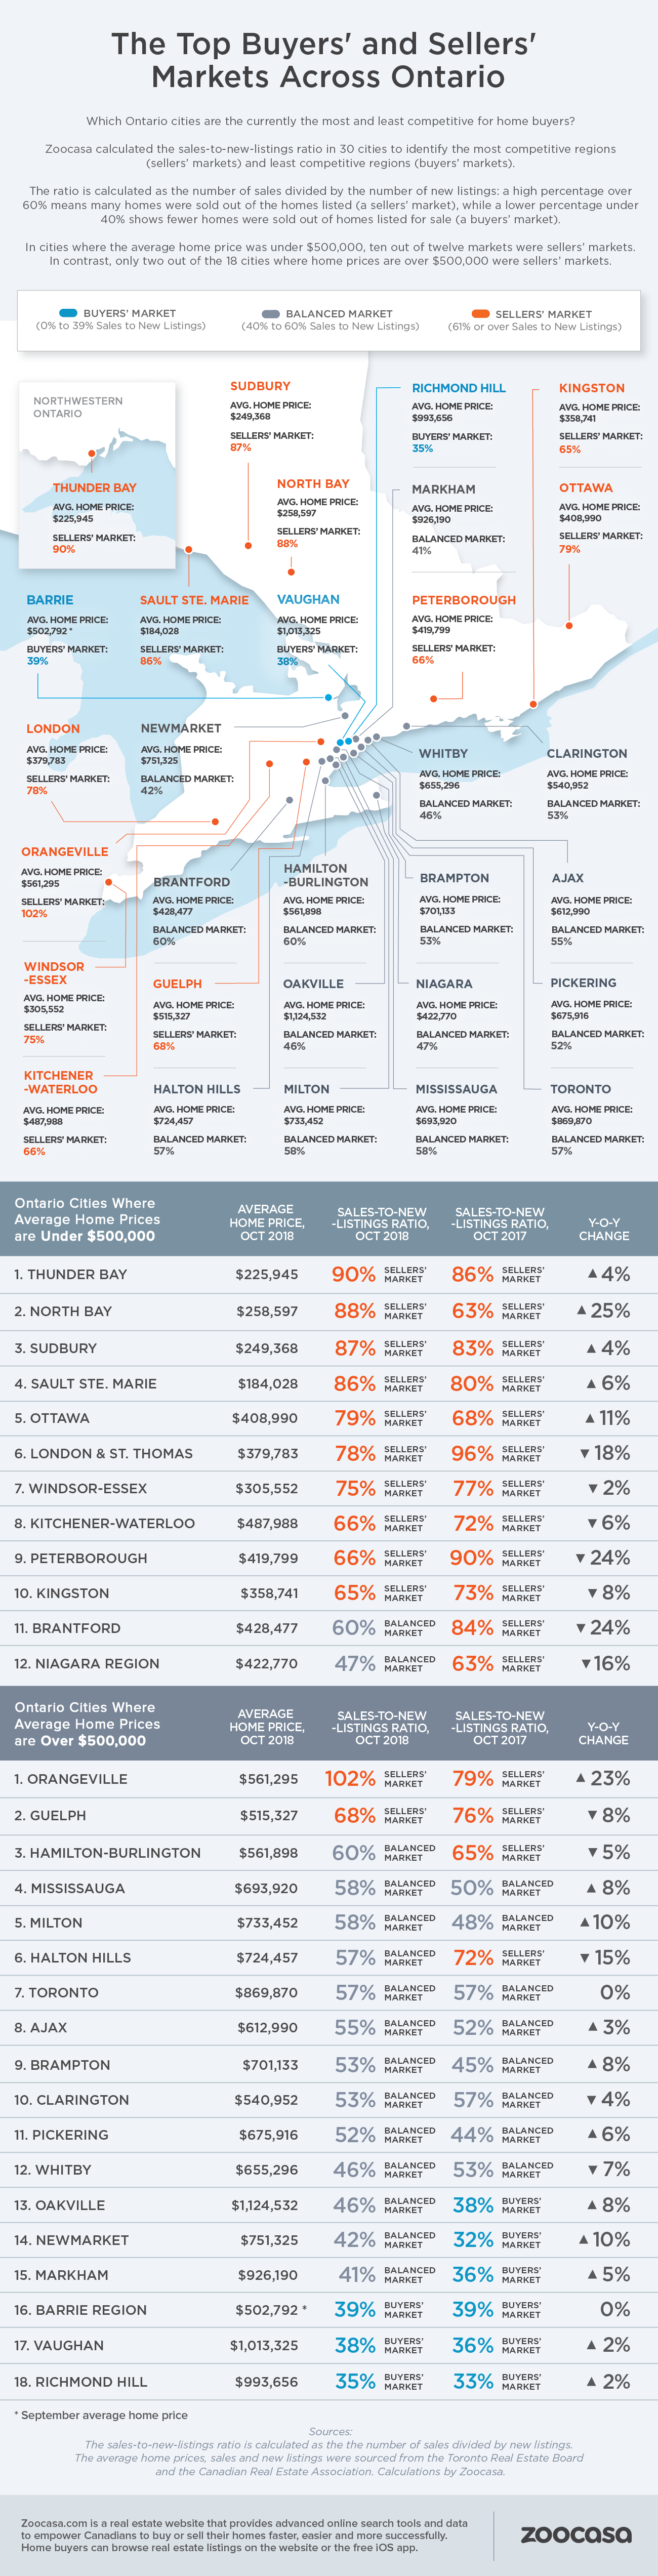
The SNLR can also be used to measure activity over larger geographic areas. At a provincial level, Ontario’s housing market remains in balanced territory, with an SNLR of 56%. However, this ranges quite widely throughout the province with some surprising results, according to recent data compiled by Zoocasa; a look at October sales and new listings numbers reveals Ontario’s most affordable markets are actually among the tightest in terms of sellers’ conditions.

Sellers’ conditions in Ontario’s most affordable markets

In markets where homes sell for less than $500,000, 10 of 12 municipalities could be considered sellers’ markets. Continue Reading…

Major credit-card mistakes to avoid over the holidays


By Hyder Owainati

Special to the Financial Independence Hub

The holiday season is now in full swing, and for most Canadians, that means ramped up spending and a large end-of-the-month credit card bill. While not inherently bad – as a credit card that’s paid off in full and on time can offer valuable cash back or travel points – there is a delicate line that must be tread. 

Here are some of the major credit card mistakes you’ll want to avoid making over the busy holiday shopping season to ensure your card is working for you (and not the other way around).

Not following a budget and carrying a balance

Without a holiday budget in place, you’re more likely to spend beyond your means and carry a balance on your credit card. You always want to avoid a situation where you don’t have enough money in the bank to pay off your monthly credit card statement, as carrying a balance will lead to costly interest charges on top of the money you already owe.

When setting a holiday budget, make sure you set a maximum dollar amount you can spend, list out how many people you plan to buy gifts for, and factor in other costs that are likely to spike during the holidays, such as travel, gas and food for social gatherings. 

Taking out a cash advance

Using a credit card at the ATM for a cash advance is almost always a bad idea and should only be accessed in cases of real emergencies when paper money is a necessity – not holiday “shopping emergencies.” 

Cash advances are short-term loans that are accompanied with high fees, and unlike other purchases made on a credit card, may charge interest that accrues immediately with no grace period. So, stick to paying with cash that’s already in your wallet or charging your credit card at the sales counter over cash advances.

Using a high interest credit card

Several Canadians are starkly self-aware of that fact that they will overspend during the holidays. According a survey conducted by Ratehub.ca, 1 in 3 people anticipate they will carry a post-holiday credit card balance while a separate survey from CIBC found 52% of Canadians expect to go over budget during the busy shopping season. Yet, rewards credit cards that have high interest fees continue be the payment method of choice for many.

If you’re among the shoppers who foresee that your holiday spending will lead you to carry a balance, opt for cash or a low interest credit card. In the case of the former, you’ll be more inclined to limit your spending and avoid any interest, while in the latter, you can stretch your budget while paying up to 50% less in interest fees compared to what most other credit cards charge.

Signing up for a store credit card without thinking it through

A number of retailers may try to lure you into signing up for their store credit cards during the holidays, often providing steep discounts on everything in your shopping cart if you apply on the spot. You’ll want to think twice before signing on the dotted line however. 

Most store credit cards have low credit limits, high interest charges in the instance you carry a balance and lacklustre rewards: particularly when compared to what Canada’s best travel credit cards or cash-back cards have to offer. While in some instances applying for a store credit card can be worth it, (if you frequent the same store for all your shopping runs for example), you’ll still want to do some research and avoid being swayed by a one-time discount. 

Not shopping from your loyalty program’s e-store

From the airmilesshops to the Aeroplan eStore, numerous credit card loyalty programs have online shopping portals that offer bonus points on your purchases. So instead of automatically visiting a retailer’s official website or Amazon to hunt for online holiday bargains, tap into your loyalty program’s e-store to potentially walk away with up to double the amount of points your card typically offers.

Not reading the terms of your card’s welcome offer

If you picked up a new credit card with a lucrative welcome offer just in time for the holidays, you’ll want to get familiar with the offer’s terms and conditions. A number of welcome offers don’t come into effect immediately and may require you to hit a minimum spend of $1,000 in order to get your bonus points or wait up to 3 months before you can access your cash back savings. 

Many card offers also stipulate your account needs to be in good standing for you to be eligible to receive an offer. So, if you missed a series of payments on your card, you may lose out.  In such instances however, it’s always recommended you contact your bank or card issuer as they may offer to maintain your eligibility. 

Paying extra fees while travelling

If you plan on escaping Canada’s blistering-cold winter for a beach getaway or are travelling to visit family abroad during the holidays, you’ll want to read up on what your card charges for foreign purchases. The huge majority of credit cards charge a foreign transaction fee (usually around 2.5%) on every purchase you make on your credit card in a non-Canadian currency. With that being said, there are a number of no foreign transaction fees credit cardsthat Canadians can use abroad that waive this fee and can help you save big on purchases you make outside of the border.

Not taking any action after accruing credit card debt

If, after the holidays have come and gone, you’ve racked up debt on your credit card, it’s critical you take steps to address it. Limit your spending on nice-to-haves and focus on paying off your balance, avoid racking up additional debt by using cash or debit to cover purchases instead of plastic, and consider transferring your balance to a new card with a lower interest rate (known as a balance transfer).

Hyder Owainati is a Content Marketing Specialist at Ratehub.ca, a website that compares credit cards in Canada, as well as mortgage rates, high-interest savings accounts, chequing accounts, and insurance, with the goal to empower Canadians to search smarter and save money.

Bucking the public’s confirmation bias on Chinese stocks

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

Does the “global trade war,” quotation marks intentional, spell doom? It depends on your silo. 

The 2009 American Recovery and Reinvestment Act poured some C$1.03 trillion of stimulus into the system, while China’s coincident crisis-era package dumped a C$768 billion package on top.1Central banks added trillions in bond purchases for the trifecta.

But some people may have missed the boat. Who? Those who couldn’t get past their ideological differences with the last U.S. president, who made some of them think the global financial crisis would lead to a perpetual depression. Distorted reality costs money, and what happened with Obama’s detractors is now happening in the Trump administration. Some proportion of the public, including many on Wall and Bay Streets, are letting their political views with respect to President Trump get in the way of arithmetic.

That can create opportunity for the sober observer.

What is one mistake investors are making? Prognosticating “global trade war” doom.

Global Trade War?

2018 has witnessed nothing but improvement in relations between China and Japan, nothing but improvement in relations between Japan and Europe and, arguably, nothing but improvement in relations between the U.S. and both Mexico and Canada, at least compared to this past summer.

Some global trade war this is, with major foreign leaders jumping over each other to prove their free market bona fides.

“We must promote trade and investment, liberalization and facilitation through opening up—and say no to protectionism.”— Chinese President Xi Jinping, 2017

“It is also quite vital that we keep on raising high the flag of free trade.” — Japanese Prime Minister Shinzo Abe, 2017

“We believe multilateral cooperation can add value for everyone, and that’s why we’re advocating global trade that is as free as possible and which is based on common rules. ”— German Chancellor Angela Merkel, 2018

The truth is that Trump is calculating that Americans have finally hit a wall on the status quo with respect to China. Regular people on the street may not know the specific trade numbers, but they know where the knock-off purses come from, they know now about wanton intellectual property theft and, most disconcertingly, cyberwarfare.

In reframing the argument about global trade, does anyone care that Japan, China and South Korea are sitting at the table with one another for trilateral trade talks?2How about the big August trade deal between Japan and the EU? Talk about large economies. 

While market angst is focused on the Trump administration’s “global trade war,” most of the planet is actively making deals, in direct contrast to the meme of global internecine tariff warfare.

And China’s Scythe on Taxes

While markets react to headlines, China’s fiscal stimulus continues apace. Some investors appear to be missing the good in hoping for Trump to prove an economic failure. One such “good” is the total revolution happening in China’s personal income tax code, shockingly ignored by so many. Figure 1 shows the C$565 tax cut that the average white-collar Chinese worker, earning C$17,689 a year, is set to witness. There’s more too if we count mortgage, student loan and child deductions (figure 1).3 

Figure 1: Proposed China Personal Income Tax Example, Average White-Collar Worker

Proposed China Personal Income Tax Example

That comes on the heels of this spring’s 1% cut in value-added tax (VAT) rates. Combined with income tax relief, we count C$135 billion in cuts this fiscal year alone (figure 2).4

Figure 2: VAT + Personal Income Tax Cuts, 2018 Amount

VAT Personal Income Tax Cuts 2018 Amount

Granted, there are offsets. For example, Beijing is also vaguely promising reductions in social insurance premiums, but that may be more than offset by the tax authority’s ratcheting up of collections efforts this year. The result could be a net tax hike on this front.

Nevertheless, figure 3 shows the decade-long effect of Chinese President Xi Jinping’s tax cuts on the VAT and personal income fronts. At slow-to-fast growth rates, the cumulative 10-year estimate is C$1.35 trillion to C$2.66 trillion, straddling both sides of Trump’s C$1.97tn package that sent stocks higher in 2017.

Figure 3: Cumulative 10-Year Total, Xi Tax Cuts (Using WisdomTree’s C$135bn Calculation for 2018)

Cumulative 10 Year Total Xi Tax Cuts

Meanwhile, we present figure 4; China’s exports to the U.S. have been shooting higher in a largely uninterrupted fashion for most of this century.

Figure 4: Annual USD Chinese Exports to the U.S.

Annual USD Chinese Exports to the US

The Play

Our TSX-listed dedicated China strategy is the WisdomTree ICBCCS S&P China 500 Index ETF (CHNA.B). It hits broad China with a 9+% earnings yield and tracks China’s S&P 500.5Because it is so broad, it can be used as a single line item for a portfolio’s entire Chinese equity exposure. 

While the mass of investors focus on “global trade wars,” few observers are noting Chinese fiscal expansion or, for that matter, big trade deals being signed right now. There’s your edge, contrarian reader.

1Sources: Congressional Budget Office, Publication 49958, Estimated Impact of the American Recovery and Reinvestment Act on Employment and Economic Output in 2014. Chinese stimulus data by The Economist, China Seeks Stimulation, 11/10/08.2Source: Laura Zhou, “China, Japan and South Korea Aim to Speed Up Talks on Free-Trade Agreement to Counter U.S. Tariffs,” South China Morning Post, 9/22/18.
3Average white-collar worker income calculated by Zhaopin Ltd., a career platform similar to Monster.com, as of end-2017. Tax cut calculations by WisdomTree, using the PBoC’s tax proposal that is likely to become law in October.
4See source data beneath Figure 1.
5Sources: Bloomberg, WisdomTree, as of 10/24/18.


Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.

 Important Risks Related to this Article

There are risks associated with investing, including possible loss of principal. Foreign investing involves special risks, such as risk of loss from currency fluctuation or political or economic uncertainty. The Fund focuses its investments in China, including A-shares, which include risk of the RQFII regime and Stock Connect program, thereby increasing the impact of events and developments associated with the region, which can adversely affect performance. Investments in emerging or offshore markets are generally less liquid and less efficient than investments in developed markets and are subject to additional risks, such as risks of adverse governmental regulation and intervention or political developments. The Fund’s exposure to certain sectors may increases its vulnerability to any single economic or regulatory development related to such sector. As this Fund can have a high concentration in some issuers, the Fund can be adversely impacted by changes affecting those issuers. The Fund will be required to include cash as part of its redemption proceeds which introduces additional risks, particularly due to the potential volatility in the Chinese market and market closures. The Fund invests in the securities included in, or representative of, its index regardless of their investment merit and the Fund does not attempt to outperform its index or take defensive positions in declining markets. Due to the investment strategy of this Fund, it may make higher capital gain distributions than other ETFs. Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.

How can you create a supplementary source of income?

By Beth Morris

(Sponsored Content) 

Is your job failing to provide you with money to spend on the things that you always wanted to have for yourself? Since you most likely have free time other than the typical eight hours of sleep per day, you should use it to earn additional income.

If you need further convincing as to why you should seek to build a source of income aside from the one that your current job provides, you should consider talking to a financial advisor or planner like those from Capstone who can walk you through the nitty-gritty of how to plan out your finances going forward. But if you already want to get straight to it, here’s how you can create a supplementary source of income:

Build an online store

Shopping online has become a common activity for some, especially those with tons of money to spend but don’t want the inconvenience of driving into town. However, instead of settling at becoming an online shopper yourself, why not try selling products via the Internet?

You might want to consider registering a seller account first at an e-commerce platform such as Amazon or eBay. You can set up shop in your chosen e-commerce platform in only a matter of minutes, thus allowing you to focus more on spreading the word about your online store and targeting potential buyers.

Once you’ve established yourself as an online seller, you can then consider creating a dedicated website for your onlinestore where you can have fuller control of all the profit generated by your side business. Just remember to retain your day job for the time being until you can already live comfortably using the earnings that your online store receives.

Work as a Freelance Writer

You may have a knack for writing about anything under the sun, but your current job might find you doing anything but that. However, since you don’t spend your entire day working at your job, you can use your free time in an income-generating way by rekindling your passion for writing and finding work as a freelance writer.

Website owners and bloggers who find very little time to write content – especially if they have a hectic schedule – often hire freelance writers and pay them to create articles and posts. Once you become a freelance writer for a website owner or blogger, your research skills will be put to the test, thus making you learn more about specific topics in a more active way compared to when you stumble upon a random article on the Internet and read it in your spare time. Best of all, you can work anytime you want as a freelance writer. Continue Reading…