General

Closed-end funds vs. actively managed ETFs

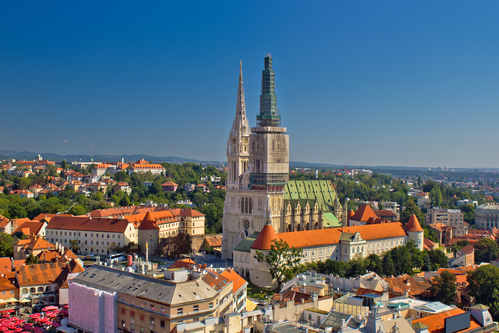
Zagreb, capital of Croatia, HQ for closed-end fund manager OTP Bank.

By Tony Porcheron

Special to the Financial Independence Hub

The current popular conversation in investments is about Exchange Traded Funds (ETF) versus normal mutual funds. The conversation is always about low fees vs high fees. The one version that never seems to come up is about Closed-end Funds, which are the granddaddy of all managed money.

The brief history of the modern managed money industry — which included mutual fund, hedge fund, and exchange-traded fund (ETF) industries — started formally with The Investment Company Act of 1940.

It clearly defines the responsibilities and requirements of investment companies as well as the requirements for publicly traded investment product offerings including open-end mutual funds, closed-end mutual funds and unit investment trusts. It primarily targets publicly traded retail investment products.

The next major development was the first index fund. This was a Wells Fargo fund formed in 1971. In 1974, the first mutual fund index shares were offered to retail investors.

Finally, exchange-traded funds came along in 1993 with the invention of TIPs (Toronto Index Participation Units) on the TSX.

The ETF is now growing tremendously globally with investors looking for lower fees during strong market cycles.

You can now get ETFs in a variety of investment focuses, types, industries, countries, security selection bias, etc.

The majority of ETFs are passive, where the manager simply follows the direction of the fund outline with no or extremely little input from the manager. These ETFs are usually with the smallest fees down to less than 0.1% on large US Indexes or Fixed Income Funds. As the funds are very large and need little management input, they can still be very profitable for the fund companies to manage.

Actively managed ETFs

There are also ETFs that have an active management approach. The manager then has some or a tremendous amount of involvement in stock selection and management of the fund. Active ETFs are usually in sectors where it is difficult to get an index return or average. These would be in situations such as emerging markets, small or microcap stocks or sub investor grade fixed income. Continue Reading…

3 ways to organize your new business

By Sia Hasan

Special to the Financial Independence Hub

If you have a new business, then it is crucial that you organize it in the right way. Otherwise, you could end up missing out on more productivity.

So ensure that you get the most done possible during the day and increase profits while reducing problems with workflow. Set up your business for massive success by organizing your business better in the following three ways:

SOP (Standard Operating Procedure)

The first thing you need to do when organizing your new business is determine what kind of roles everyone has. There should be specific and unique classifications as to who is responsible for what.

The best way to do this is with SOPs. These are documents that show everyone what is expected of each role. You can have certain protocols as to how to handle consumer service, sales, and more.

The idea of the SOP is that anyone can plug right into your business and know how to perform that role without much hassle. It’s a step by step list of instructions so there is no confusion regarding what needs to be accomplished to deem that particular part of the business a success. Of course, this kind of thing won’t happen overnight!

It is best to sit down and make time to create your own SOPs. You might even read a few books or resources on the subject. This way, you have some guidance. There are a lot of different ways to do it, but you need to choose one that works for you.

For instance, some people find that they prefer to record a video and upload the files online. Then, it acts as a training resource. Others like to write down the procedures and share them in the cloud. Do whatever seems right for your new business.

The right software

We live in a world where software is more important than ever. It is vital that you use the right software tools or you could risk falling behind. Oftentimes, the right software will allow you to get more done, save time, save money, and stay on the cutting edge so you can generate new ideas for even more innovation. Consider the various types of software out there.

For instance, accounting software for nonprofits helps you keep an eye on your transactions. This is crucial for a company. If you lose sight of what you need to be doing for your income or expenses, then it could come back to bite you later. This is true regardless of what kind of business you run.

Another type of software is a great CRM. Being able to communicate with your team and upload information about customers is invaluable. It shaves time off the communication cycle and gives everyone what they need in the cloud.

Sales and Marketing Automation

Long gone are the days where marketers had to sit down and write out a new email, post, or ad by hand. Today, you can use automation software to make these assets in a scalable way. After all, your team can’t be there every second of the day.

You want your team focused on the higher-level aspects, so let them do that. Enable them with marketing software that automates your funnels. It can test your ads right away. Continue Reading…

Is every day a Saturday in Retirement?

Is every day a Saturday in retirement? That’s what behavioural scientists Dan Ariely and Aline Holzwarth claimed in a recent study about retirement income. The premise being that when you’re no longer working 40 hours a week (or more) all of a sudden you have 40 hours a week available to spend money. Every day is like Saturday. Not to mention, many of the things your employer used to pay for, such as coffee, a smart-phone, or gym membership, now falls on you.

The study’s conclusion? Retirees should expect to spend as much as 130 per cent of their preretirement income after they retire. Yikes!

That flies in the face of typical retirement planning advice, which pegs the income replacement rate at around 70 per cent of your preretirement income. A lot of expenses should disappear when you reach retirement age. Hopefully your kids have left home, and your mortgage is paid off. You’ll no longer have payroll deductions for income taxes, CPP, and EI. Say goodbye to the long, soul-crushing commute, along with the expensive business attire.

Because of these reasons (and others) some retirement experts, like Fred Vettese, even champion a much lower retirement income target of 50 per cent of your income.

On the flip side, in this article about money myths, financial advisor Kurt Rosentreter seems to concur with the Ariely / Holzwarth study:

All the old retirement planning textbooks said you could expect to live off less than your working income (e.g. 70 per cent). The reality of what we are seeing in the trenches doing this work everyday is that there are three phases: Age 60 to 70 where we are seeing as high as 110 per cent of pre-retirement spending; age 75 to age 85, where costs can drop to 80 per cent after the first spouse death; and costs in the final phase of age 85 onward that can be lower or higher depending on health care.

This study resonated with me because one of my biggest fears about retirement is that I’ll overspend and completely blow my carefully planned budget.

Overspending is one of the biggest Retirement fears

Why is that a fear?

We do spend more money on the weekend. That’s when we do our shopping, our leisure activities, and when we go out for dinner. Weekends can be expensive!

Continue Reading…

If you have no faith in the future, should you invest?

By Billy Kaderli

Special to the Financial Independence Hub

As many know, I am more than willing to offer financial advice in order to help others to become financially independent (aka “findependent.”) The sooner the better” that’s good for everyone, right?

I met a lady at a recent event that Akaisha and I attended, and in our visiting together I steered the conversation towards finances. Knowing that she lived in Hawaii and seeing that she was probably in her 40s, I falsely assumed she had some knowledge of money and how it works.

I was wrong.

After I shared with her that we retired at the age of 38, I asked what her financial plan for retirement was. She told me that she did not have much faith in the future, therefore she had no plan.

I asked her, “What if you are wrong?”

Her response was “I do not think I am wrong”

The Dollar is going to collapse

I have been hearing of the impending collapse of the Dollar for the last forty years.

First it was going to be replaced with the German Mark, then the Swiss Franc, then the Russian Ruble, Chinese Yuan, and now Bitcoin. Maybe someday they will be right, but so far, betting against the Dollar has been a costly investment.

I like to tell people that the Dollar is the cleanest shirt in the dirty laundry bin. Maybe you have some special inside trading information, but for me, I’ll stick with the U.S. currency.

Various apocalyptic scenarios

Maybe it’s part of being human, but it seems that society creates ominous future scenarios of various sorts to scare the living bejesus out of everyone. Continue Reading…

Poking fun at investing clichés

“You sell when people are greedy and buy when people are fearful.” —Warren Buffett

Do you ever wonder what the gurus are really saying when they speak in clichés? Typically in trying to draw your attention to what is happening in the markets.

Don’t fret. I often find myself wondering just what someone said or meant. I suggest poking a little fun at this topic is a valuable exercise.

As in practically every other part of life, the world of investing is full of clichés. Some are pearls of wisdom to behold.

Hopefully, poking a little fun at these investing clichés helps you better understand ‘guru speak.’

They are found throughout the internet. Let’s uncover some common clichés favoured by the pundits and what the translations really mean.

Guru speak gems
Here is my sampling of “guru speak” gems and corresponding translations that stand out for me:


1.) “It’s different this time”
Some wild and crazy logic is about to be let loose.


2.) “Markets never move in a straight line”

Take the ups and downs in stride.


3.) “You’re catching a falling knife here”

It’s going to get worse before it gets better.


4.) “Greed can be the achilles heel of investors”

Sell when you can, not when you must.


5.) “Markets can stay irrational longer than you can stay solvent”

You had better have some deep pockets.


6.) “All the weak hands are getting shaken out”

I’ve lost a lot of money on this, but I’m still right.


7.) “You have to be defensive here”

I have no idea what is going on in the markets.


8.) “My thesis is still intact”

I am so underwater on this investment, I see the ocean floor.


9.) “Bulls make money, bears make money, pigs get slaughtered”

Take the money and run.


10.) “It’s the start of a new quarter”

Expect new money to flow into the markets to keep things going


11.) “There are big headline risks right now”

Hide your cash under the mattress.


12.) “Buy on rumour, sell on news”

Buy as you hear something may happen, sell when the company confirms it’s happening.


13.) “The markets like it”

I have no clue why stocks are rising.


Hopefully, poking a little fun at these investing clichés helps you better understand “guru speak.” Listen attentively for the next ones.

The messages are typically short and simple. For example, Warren Buffett reminds us how to buy low and sell high.

I’ve only just scratched the surface.

Adrian Mastracci, Discretionary Portfolio Manager, B.E.E., MBA started in the investment and financial advisory profession in 1972. He graduated with the Bachelor of Electrical Engineering from General Motors Institute in 1971, then attended the University of British Columbia, graduating with the MBA in 1972. This blog is republished here with permission from Adrian’s website, where it appeared on May 29, 2018.