General

Could you become car-free?

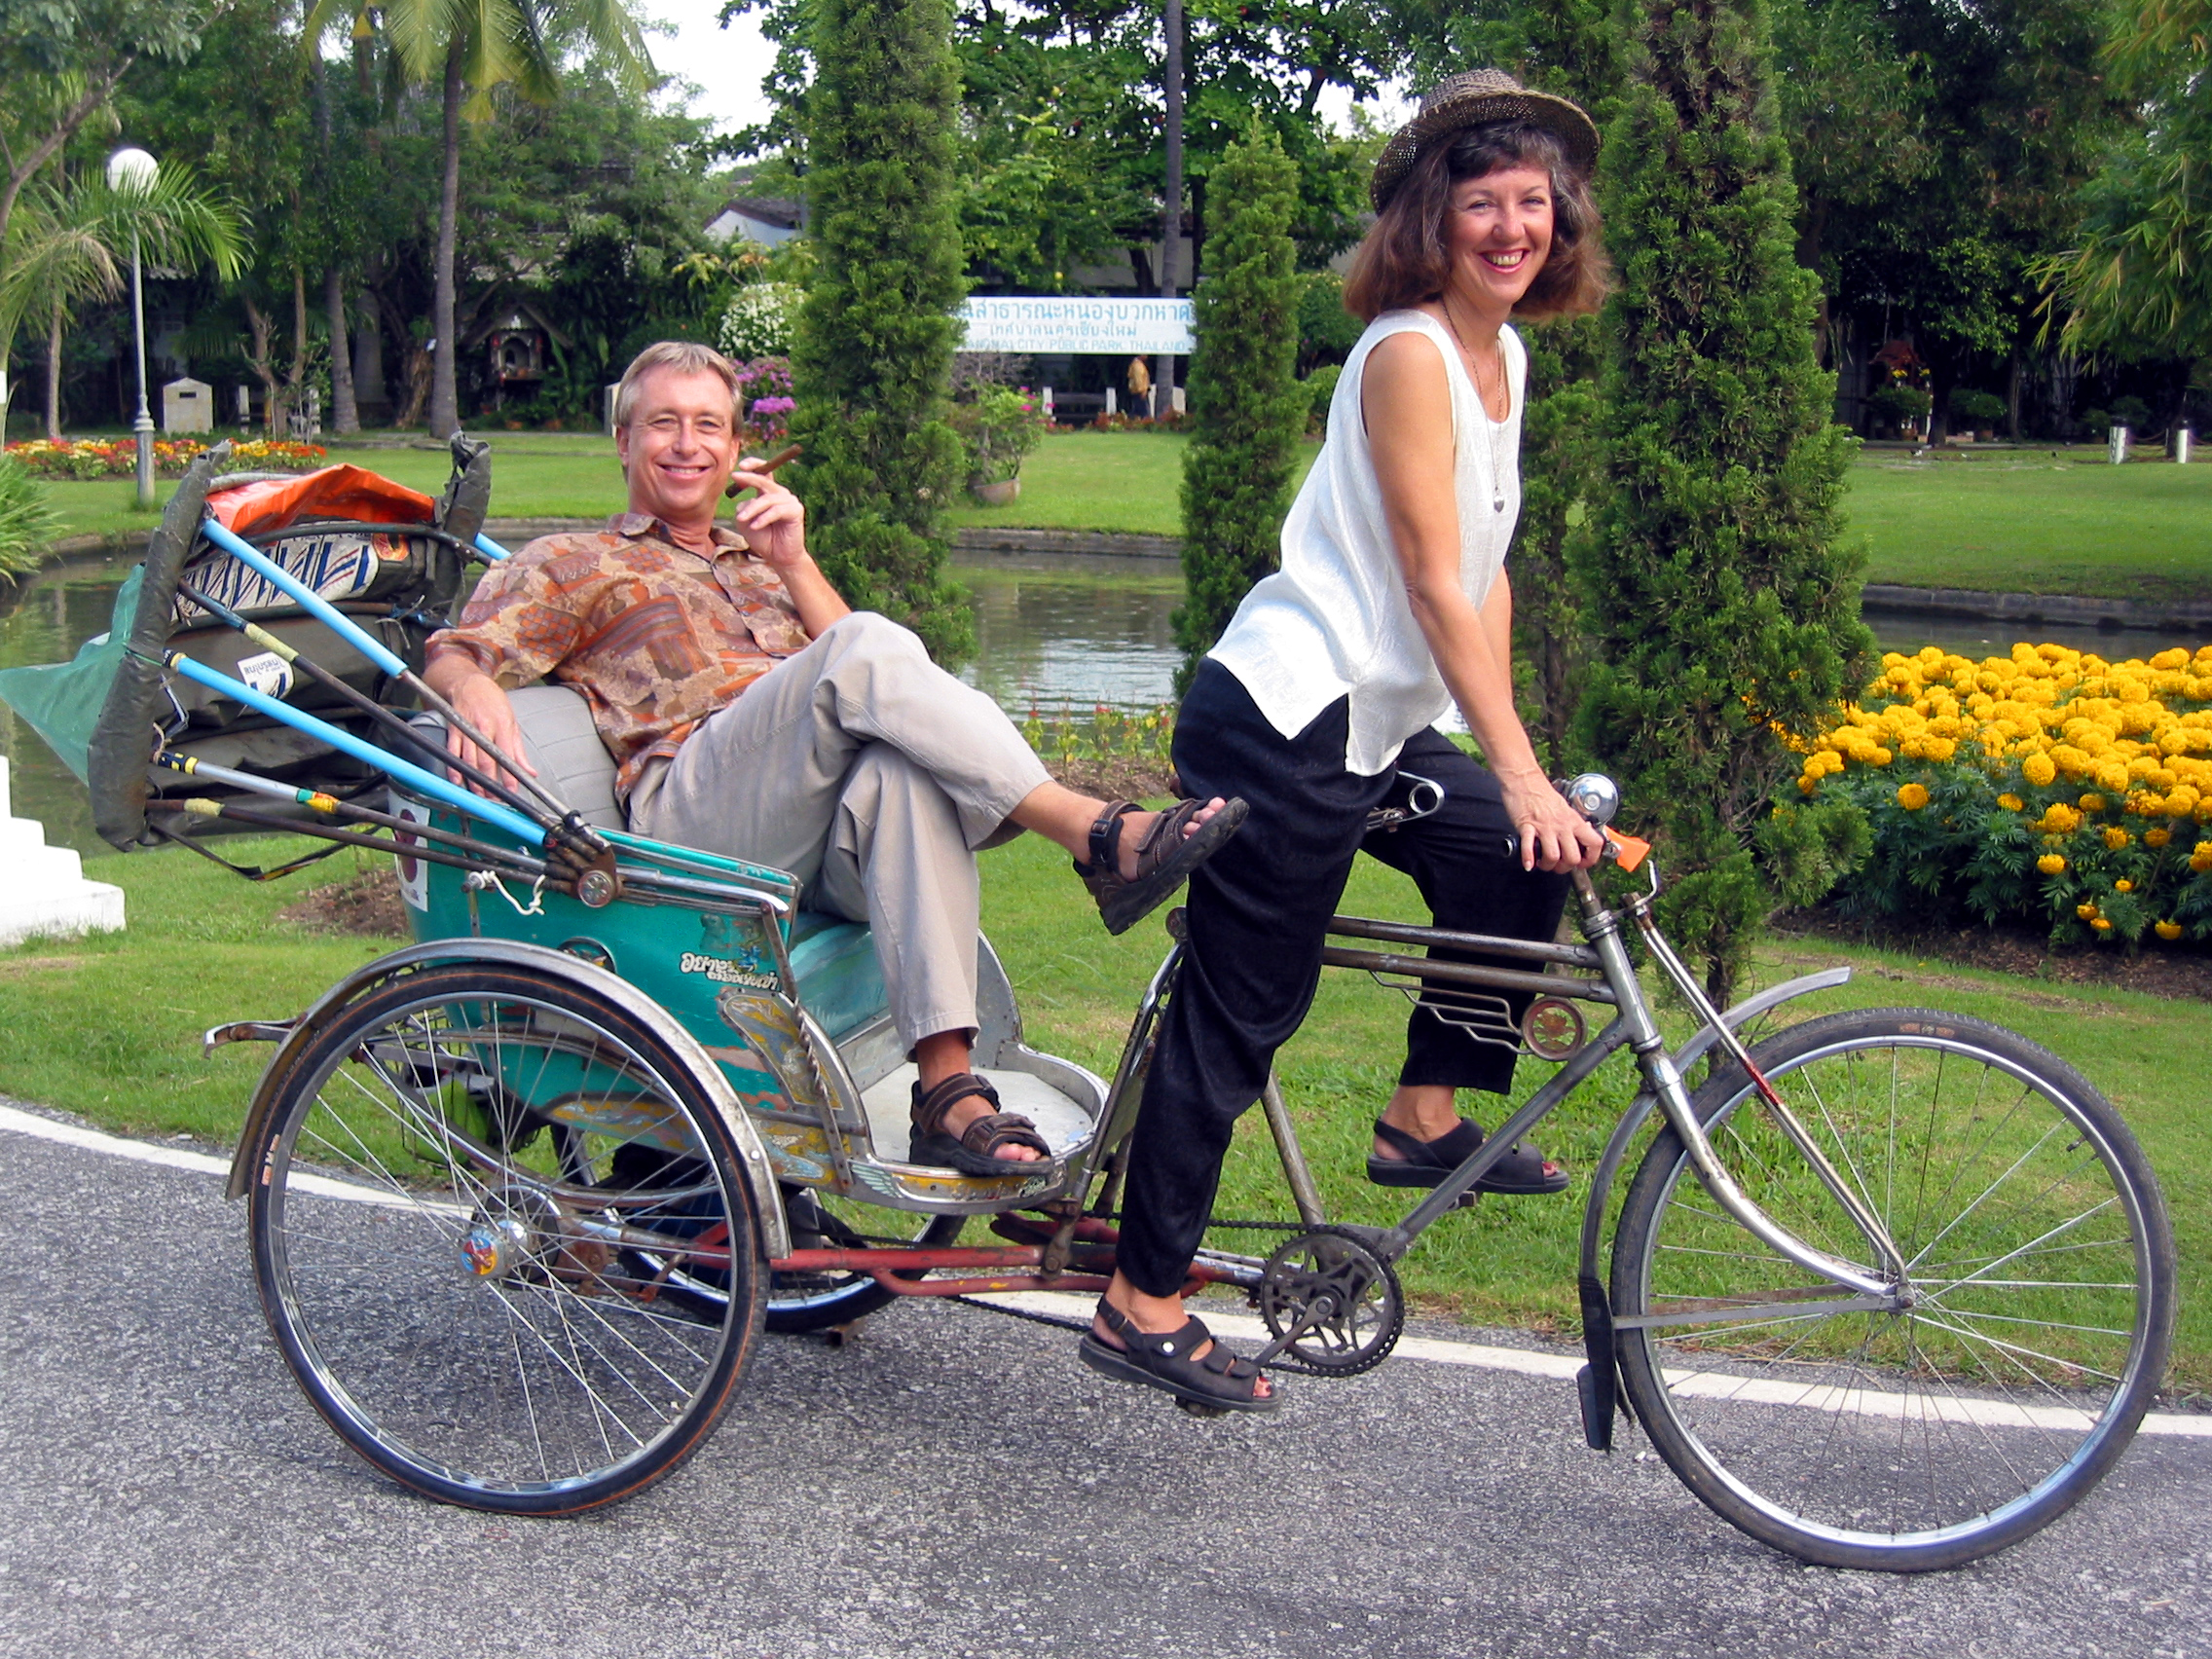
Billy and Akaisha on a Jak-a-Ran in Thailand

By Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

It wasn’t a decision we took lightly.

In fact, Billy and I discussed the idea of becoming car-free for several years. There were good reasons to do it: no more maintenance and repair costs; no more fees for insurance, license plate renewal, or registration; no more fuel expense; and no more worry about storing the vehicle here in the States when we are traveling overseas for months or years at a time.

But there were also some obvious downsides. We wouldn’t have the freedom to come and go at a whim. And because we live in the American Southwest, where temperatures reach triple digits in the summer, we wondered how we’d manage to get around during the sun season.

Silly idea or feasible plan?

Most people we know couldn’t fathom the idea of giving up their vehicle and saw this new lifestyle choice as a hardship. Americans love their automobiles, and owning one is packaged as part of the American Dream. A look at the automobile and truck commercials today describe how we will be sexier, more popular, physically stronger, and obviously smarter if we purchase their brand of car.

As we’ve described on our Retire Early Lifestyle website, Billy and I live in an active adult community where we are within walking distance to stores, restaurants, and several different entertainment options. Most of what we need is near to us, and we appreciate the slower pace of life with all the rewards it brings. Many of our neighbors use a small scooter, golf cart, or bicycle to get around within a reasonable range. When we need to go somewhere farther, we trade services or pay cash to a neighbor or friend for their time. This is much cheaper than a taxi, more sociable, and we aren’t bogged down with worries about maintaining a vehicle. Both sides appreciate the trade, and our lives are enriched.

After almost two decades of world travel, we realized that the only place where we need to drive is in the States. Elsewhere, we take public transportation or hire a private driver. For the amount of time we live in the States, and for the amount of money that owning our own transport required, we finalized our decision to sell our vehicle.

The year was 2009.

What about you? 

Retirement takes many expressions and even if you could never see yourself as becoming completely free of car ownership, maybe you have toyed with the idea of keeping only one vehicle instead of two.

The following sites may help you with this transition: Continue Reading…

The (Renewed) Case for GICs

**This is a sponsored post written by me [Robb Engen] on behalf of EQ Bank. However, as always, all opinions are my own.

A guaranteed investment certificate (GIC) is unlikely to spark an exciting dinner party conversation but when stock markets are reeling, like they were earlier this year, investors often seek safe havens to wait out the storm. Cash is king for those who don’t have the stomach to watch their portfolio plunge in value, and GICs at least offer the promise of a modest return.

Back in February 2009, when the global financial crisis had just about reached rock-bottom, 30-year-old me was scrambling to meet the RRSP deadline and bought a five-year GIC. It was a costly mistake in hindsight. The Toronto Stock Exchange surged ahead for the next five years, earning annual returns of 9.52 per cent, while my five-year GIC earned an average annual return of 2.75 per cent.

Instead of turning my $7,000 contribution into nearly $10,000, I only had $7,800 to show for my decision. At the time, though, I thought the GIC was a smart move because I had to make a quick decision on what to do with my contribution, and the stock market still looked downright nasty.

Why invest in GICs?

The truth is there’s nothing wrong with stashing your savings inside the comfort of a GIC. Here are four times when it makes good sense to put your money in GICs:

1.) When your entire portfolio is sitting in cash, waiting for “the right time” to get into the market

If you’re the type of investor who can’t ignore the doom-and-gloom economic headlines, and who’s convinced that a market meltdown is always imminent, maybe the stock market isn’t right for you.

Having your retirement savings constantly sitting in cash and earning nothing is like sitting on the fence and being paralyzed to move for fear of making the wrong decision at the wrong time.

A GIC ladder, which might involve purchasing equal amounts of one, two, three, four, and five-year terms, will maximize your risk-free returns and still give you the option of dipping your toes in the market each year when one of the terms comes due.

2.) When your investing strategy boils down to chasing last year’s winning stocks or mutual funds

If you’re the type of investor who’s constantly looking for the latest fad, you might be falling victim to the behaviour gap – the difference between investment returns and investor returns.

Consider that, according to DALBAR, from 1986 to 2016 the S&P 500 Index averaged 10.16   a year, but the average equity fund investor earned just 3.98   a year.

When you think about our poor investor behaviour, coupled with sky-high mutual fund fees (at least, here in Canada), those investors who just can’t help themselves might be better off parking their savings in the best five-year GIC and earning a guaranteed return. Continue Reading…

Stock portfolio management and planning for your Heirs

Our work with stock portfolio management clients sometimes gives us a window into problems that can arise with the death of parents and the distribution of their personal belongings and financial assets.

For instance, siblings may assume they were supposed to get particular items of jewelry or furniture. When they learn that somebody else asked first, they can harbour a grudge that can last for decades.

Planning for your heirs: Head off sibling conflict with frank discussions

The best way to spare your family this problem is to head it off while you’re still alive. Tell your kids that you want to be fair to everybody. Ask them to send you a note or an email to express interest in any particular article. But don’t put too much emphasis on who asked first, and don’t feel you need to rush into making a list of who gets what. Some of your children may be slow to think of what items matter most to them. Or they may feel shy about asking for them.

Everybody should understand that if one child gets valuable household items from the estate, they may wind up receiving less cash.

Unpaid loans from parents can also cause dissension. Sometimes adult children run into money problems and wind up having to sell their home, for instance. Later, they may want to borrow the down payment to buy another home. If you grant that request, don’t simply write a cheque.

Instead, have a lawyer register a mortgage on the new home for the full amount of the loan. Explain to your child that this protects the money from attachment by creditors if new money problems come along, and keeps it in the family. You should also be aware (no need to mention it to your child) that this step also keeps the money in the family in the event of divorce.

Dissension can also arise when a child stays in the family home long after his or her siblings have moved out. Living at home and taking care of a parent can hold a child back from career advancement, and may get in the way of the child’s social or romantic life. But siblings may see it as simply taking advantage of free room and board. If you think it’s appropriate, you may want to add a line or two in your will that acknowledges the personal contribution of the stay-at-home child.

It’s hard to avoid all tension that grows out of these all-too-human conflicts. But if you think about them and talk about them with your children, things will go much more smoothly than if you leave them for the kids to sort out on their own.

Planning for your heirs: Invest based on your heirs’ timelines

If you have substantially more money than you’ll need for the rest of your life, and you plan to leave the excess to your heirs as part of your retirement planning, it makes sense to invest at least part of your legacy on their behalf. That is, invest based on their time horizon, not yours. And above all, choose investments with our Successful Investor philosophy in mind.

For instance, if your heirs are in their 40s, your retirement planning should involve holding at least part of your portfolio in a selection of investments that would suit investors in their 40s, and that follow our Successful Investor approach. Of course, you’d still want to invest conservatively. But you’d want to take advantage of the many years that 40-somethings have till they reach retirement age. Continue Reading…

Which Robo Advisor differs from the other?

I recently penned the blog What and who are the Canadian Robo Advisors? That blog outlined how, true to the moniker, a robo advisor is an online financial advisor without the human.

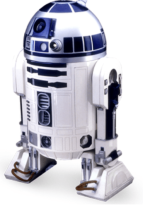
Well, let’s say that at times there is no human present. In actuality the robo advisors are all quite human and they all have a unique personality. Think Star Wars and the loveable tin cans known as R2-D2 and C-3PO. They are very different in voice and personality.

Above left is R2 …

And to the right is my robo mascot …

The answer to the question posed in the headline is that all of the robo advisors are different, at times very different from one another. That’s why it’s important to know and understand these differences so that you might be able to find the robo that’s right for you. Getting in the ‘right robo’ might make a difference of thousands to tens of thousands of dollars or more over an investment lifetime.

The ‘robots’ don’t think in a pure sense. In most cases, this is not artificial intelligence at work. The process involves investment concepts and approach(es) and then mountains of computer programming applied so that the robo platforms can follow the direction of the human financial gurus who set the course for each robo advisor.

The Chief Investment Officers and their teams can and do also make adjustments on the fly. Some may react to market conditions. That may seem ironic given that the robo advisors will mostly embrace and use mostly passive Exchange Traded Funds, but they will then get a little more active with regards to asset allocation and types of funds used based on changing market conditions. All said, that will be one of the factors that I track moving forward as we compare the performance of the Canadian robos.

Robos can be passive or active

Some robos are more passive, some robos are very active.

One of the robo advisors, responsive, is considered AI-based as the platform will automatically change the asset allocation (mix of stocks and bonds) based on many market and economic indicators. Continue Reading…

A growth-by-acquisition strategy could stunt growth of marijuana producers

Cannabis by the Numbers (TSINetwork.ca)

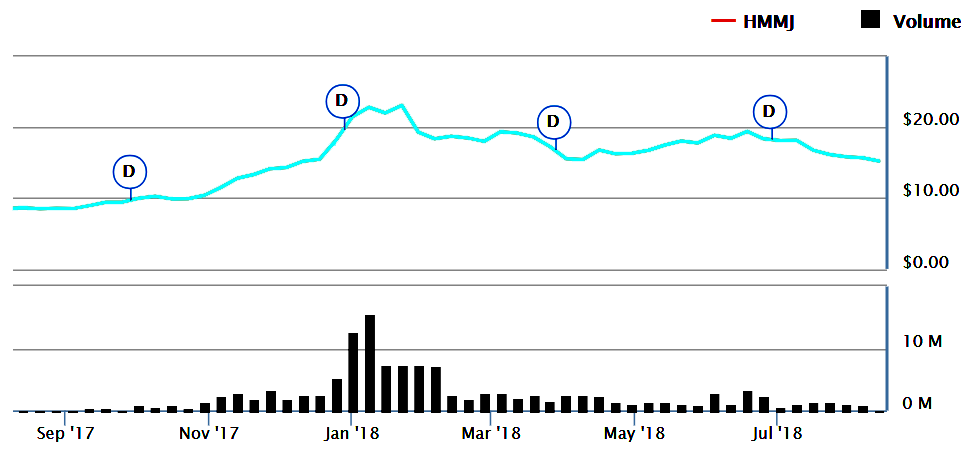
Expanding by acquisition can be risky in any business, but it carries even more risk in a new industry like marijuana production. Buyers could end up with companies whose revenues are completely dwarfed by their outsized market caps.

Many marijuana producers continue to grow quickly by acquisition.

Some are looking to diversify: either from medical marijuana into recreational cannabis, or into new areas like edibles. Most are/were simply looking to grab as much market share as possible before legalization on October 17, 2018. That’s because buying an existing grower is a much faster way to boost output than building a greenhouse from the ground up.

Canadian producers are also looking to expand internationally, including buying marijuana sellers overseas as medical marijuana becomes increasingly legal worldwide.

Higher chance of unpleasant surprises

In general, growth by acquisition is riskier than internal growth for a variety of reasons, but especially because acquisitions carry an above-average chance of unpleasant surprises. The buyer of something rarely knows as much about it as the seller. If a company makes enough acquisitions, it is bound to buy something with hidden problems. Eventually, those problems come out in the open and hurt the buyer’s earnings. Growth by acquisition in unrelated areas is especially risky.

That kind of expansion also tends to load up a company’s balance sheet with goodwill. Generally speaking, “goodwill” is the total price a company has paid for all acquisitions it has made over the years, minus the value of tangible assets that it acquired as part of its acquisitions. Goodwill is an intangible asset whose value can drop overnight if it turns out that the company made a bad acquisition.

The purchases that marijuana producers are making are particularly risky. That’s because they are mostly buying firms with huge market values: but with limited revenues and little chance of making a profit anytime soon.

Pat McKeough has been one of Canada’s most respected investment advisors for over three decades. He is the founder and senior editor of TSI Network and the founder of Successful Investor Wealth Management. He is also the author of several acclaimed investment books. This article was first published on Aug. 22, 2018 and has been republished on the Hub with permission.