General

How to add value to your home before selling

By Emily Roberts

(Sponsored Content)

Over time, the value of your home can be expected to gradually increase in value, unlike most consumer purchases (like cars), which depreciate from the moment they are acquired.

As long as you’re living in the home, this price appreciation is seldom a gain you can pocket, and in fact, your property taxes may rise as a result. But eventually it should be able to be sold at a solid profit.

When you do decide to finally sell, you will want to get as much money for your home as possible. You will want to get a return on your investment and be able to afford your new home. In this article, we are going to give you some ideas on how you can improve the value of your home before selling. Keep reading if you’d like to find out more.

Build an extension

If you have a lot of space on your property, then you might find that adding an extension to the kitchen or the side of your home might actually make a huge difference to the overall value. Think about how much this could cost you and how much more you might be able to make on your house when you are selling it. People love to have extra space but don’t sacrifice a garden completely for a slightly bigger kitchen.

Add Insulation

If your home is not totally insulated, then you are not saving as much money on monthly bills as you could be. Many people forget to insulate their attics and their sheds, which can consume a lot of energy. Not only will you save yourself money on the bills, but you will also save the new buyer in the long run. Make sure to insulate your home and mention it to potential buyers when they are viewing your home.

Add an outdoor building

If you have some extra space in your garden you should think about investing in an outdoor building, which you can learn more about at Armstrong Steel: one of the most renowned providers. The buildings they provide come pre-made and so all you have to do is assemble them. When you have put it together, you can choose to do whatever you want with it. Continue Reading…
Aging business owners need to tackle estate planning

By Andre Guillemette

Special to the Financial Independence Hub

Did you know that more than 50% of medium sized enterprises in Canada are controlled by an owner between the age of 50 and 64? Additionally, about 75% of Canadian business owners plan to exit their business before 2022. However, according to the Canadian Federation of Business, only half of Canadian business owners have a proper succession plan in place. If you are a business owner, you need to think about the future of your company, no matter your age.

When a family’s assets and income are linked to a business, if the business owner passes away, both estate and succession planning will ensure that the family is taken care of and the company remains viable. If a person passes away without a will, provincial wills and estate law will determine how their assets are dispersed. Without any kind of estate planning in place, their heirs could be hit with a hefty tax bill, and unexpected fees and administrative costs.

There are many steps to effective estate planning and whether they all apply to you will depend on your personal circumstances. Some of them include:

  • ensuring your will is up-to-date
  • appointing an appropriate executor
  • establishing an Enduring Power of Attorney (EPOA)
  • providing an income for your spouse and family in the event of your unexpected disability or death
  • developing a plan for equitable and tax-efficient distribution of your assets
  • creating an emergency business plan
  • writing shareholder/partnership buy-sell agreements if applicable
  • planning for succession

To accommodate the above, there are several financial strategies at your disposal to help you meet your goals. As a business owner you should investigate:

1.) Looking at insurance as a way to shelter assets for the next generation.

Permanent cash value life insurance policies, such as participating whole life and universal life, are attractive to corporations for the potential tax-free death benefit and the tax-preferred cash accumulation benefits they offer. These insurance policies provide the corporation with valuable life insurance protection on a key person or shareholder. Another benefit is they allow for tax efficient growth and access to policy values tax-free immediately or in the future. By using life insurance, the estate value available for future generations can be significantly increased by the tax-free death benefit. Continue Reading…

Forget the Trade War, already: China is cutting Taxes

By Jeff Weniger, WisdomTree Investments

Special to the Financial Independence Hub

The market’s obsession with trade wars may finally be exhausted and priced in. Move on to the next market mover: massive Chinese tax cuts, which should aid the WisdomTree ICBCCS S&P China 500 Index ETF (CHNA.B), our tracker exchange-traded fund for the country.

Sure, China exported US$457 billion (C$597 billion) of goods and services to the U.S. in the year through June, and some fraction of those exports is at risk from a deterioration in Sino-U.S. relations. But engage a drastic scenario: lop off US$200 billion or US$300 billion from that figure. Even if that happened, most of that sum wouldn’t even disappear; it would be sold elsewhere, maybe inside China, at concessionary prices. But even suspending logic and having it all vanish, is it really doomsday for China’s US$14.1 trillion economy (US$25.2 trillion at purchasing power parity)? We don’t want to minimize the importance of trade conflicts, but the airtime given this topic is hysterical.

When Obama was in office, many conservatives and free market acolytes convinced themselves he would destroy the U.S. economy, so they ignored massive fiscal and monetary stimulus — the data — and missed the equity bull market. Emotions ruled; logic lost.

Now it’s happening with Trump. Among some investors, emotions are defeating data. The recent Bank of America Merrill Lynch fund manager survey pointed to a trade war as the market’s biggest risk. Some investors so badly wish Trump to fail that, like conservatives during the Obama years, positive news is simply ignored. Forget Japan’s major trade deal with the EU, ink still wet. Forget Trump’s meeting with Jean-Claude Juncker, European Commission president, where they agreed to work toward zero tariffs. The end is near!

Astute investors need a sober, facts-based thesis.

A Thesis without Emotion

A more realistic take on matters is that China finds itself isolated, unable to pair with Moscow in a two-country geostrategic counterbalance to the West. This forces Beijing to backtrack on intellectual property theft, inordinately high tariff levels, state subsidies and dumping because of its weak bargaining hand.

The pain must be offset, so Beijing gives the market that for which it aches: trillions of dollars in tax cuts at the business, product and personal income tax levels. Yes, Trump’s ability to stir the pot is important, but mathematics matters.

Chinese equities are the play here.

Bold actions

We calculate that many Chinese will see their personal income tax liability fall by half or more, effective January 1, 2019. Add to this our estimate of nearly US$500 billion in value-added tax cuts over the next decade, with still-in-the-works business tax relief on top, which would be another US$132 billion to $138 billion if activity grows at a pace of 6% to 7%. For perspective, Beijing’s Lehman-era US$586 billion spending package, hypothesized by some to be the reason the Global Financial Crisis ended, is smaller than 2018’s total announced tax cuts, if we calculate them over several years. This is this year’s big story.

Income Tax Scenarios: Implications for everyday Chinese

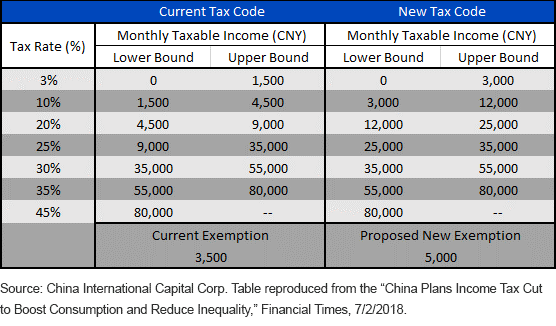
The proposed personal income tax code changes are staggering (figure 1). Exemptions and the minimum bounds for the 10%, 20% and 25% brackets are set to gap higher, while tuition, medical and mortgage deductions add to the savings.

Figure 1: China Personal Income Tax Code 

If these become law in October and are implemented in January, someone making CNY15,000 per month (C$2,906), a wage that is common in a city like Shanghai, where 2017 median monthly income is $2,048, would see their monthly taxes cut by CNY1,080 (C$209).1The person making half that amount, or CNY7,500 per month, which is short of the metropolitan median, would save about C$500 per year on an income of C$17,437. This is serious.

Chinese Equity Valuations

With many Chinese equity markets hammered this year, the S&P China 500 Index’s forward P/E multiple has fallen to 11.7, a sharp discount to the S&P/TSX Composite Index of Canadian equities (P/E of 15.8).2  Continue Reading…

The stock market crash that never came

Markets have reached all-time highs so frequently that investors are understandably nervous about an upcoming crash. The problem is, nobody knows when a crash might hit, if ever, or how severe it might be if it does occur. Stocks may continue to go up for a few years, or maybe go sideways for a while, or we might suffer a small correction of 10-15 percent before the next bull market begins.

The tech bubble and financial crisis are still fresh enough in our minds to convince investors that declines of 40-50 per cent are normal, when in fact these were major black swan events that perhaps we’ll never see again.

Investing at all-time highs

Let’s say you’re a nervous investor who decided to get out of the stock market at some point in the last 10 years, whether due to Europe, Brexit, Trump, or simply because the markets were looking “expensive.”  What’s the cost of waiting for a correction? It turns out to be quite high.

“Far more money has been lost by investors preparing for corrections, or trying to anticipate corrections, than has been lost in corrections themselves.” – Peter Lynch

The Cogent Advisor blog looked at U.S. investment returns over the period 1927 through 2016. That’s 91 years, or 1,092 months. The average monthly return was 0.95 per cent. But when they removed the returns from the best performing 91 months, the remaining 1,001 months provided an average return of virtually zero (0.1 per cent). In other words, 8.5 per cent of the months delivered almost 100 per cent of the return.

Their takeaway: Even if you believe the probability of a correction is high, it’s far from certain. And when the correction doesn’t happen, the expected opportunity cost of having waited is much greater than the expected benefit.

The Crash That Never Came

One reader who I’ll call Jason emailed me and confessed that while he used to invest in index funds he got nervous after Trump’s election and moved everything to a full service wealth management firm last year. He didn’t say in the email, but I can imagine he stressed this concern with his new advisor, who placed him into a conservative portfolio aimed to provide downside protection in the event of a crash.

Here’s Jason, one year later:

I just took a look at the past 12-month performance and it was 3 per cent vs the market of ~13 per cent. I have a sinking feeling I made a mistake and should move it back to self manage using index funds.

I sent my advisor a few questions and basically got the answer that they protect the downside, and have a lower risk targeting 4-6 per cent average over five years.

I still feel nervous, but at age 42 I think I should be more in the market. We have been at all-time highs for a while so I am torn between a bear market that may start now and the downside protection would be warranted. That said, maybe not.

Continue Reading…

Tips for investing in gold — and how to hold gold in your RRSP

At TSI Network, we’ve long recommended that you stay away from buying gold bullion, coins (unless you collect them as a hobby) or certificates representing an interest in bullion. If you are looking at investing in gold for 2018, there’s a better way.

That’s because gold investing in bullion does not generate income. Instead, bullion and coins come with a continuing cash drain for management, insurance, storage and so on.

Instead, we recommend that you limit your investing in gold to gold-mining stocks. Unlike bullion, gold-mining stocks at least have the potential to generate income.

However, if you do want to hold physical gold or silver in an RRSP, here’s how to do it:

More than a decade ago, the 2005 Canadian federal budget made investment-grade gold and silver coins, as well as gold or silver bullion bars, eligible to be held in an RRSP.

To be considered investment grade, gold coins must be at least 99.5% pure, and silver coins must be at least 99.9% pure. As well, only legal-tender coins produced by the Royal Canadian Mint are RRSP-eligible.

Bullion bars are also eligible for RRSP gold investing, as long as they are produced by a metal refinery that is accredited by the London Bullion Market Association. Accredited metal refineries include the Royal Canadian Mint and Johnson Matthey.

However, to hold the coins or bullion bars in your RRSP you need to find a third-party custodian of your coins or bars who will verify that you indeed hold the amount of bullion claimed, and report that to the Canada Revenue Agency on your behalf. Despite those safeguards, we do not recommend investing in gold through coins or bullion.

Investing in gold: a practical way to hold gold bars and coins in your RRSP

Questrade, a Canadian online discount broker, introduced its “Gold RSP” in January 2006. A decade later, in July 2016, this investment still meets all of the Canada Revenue Agency’s specifications, and makes it practical to hold coins or bullion bars in your RRSP.

To access the Questrade Gold RSP, you have to open a Questrade account. You can open an account with as little as $1,000. Kitco Metals buys the gold from the Royal Canadian Mint, and the gold is stored at the Mint, as the Canada Revenue Agency requires. Bid and ask prices are quoted on the Questrade web site, so you can buy and sell gold bars or coins if you want to bet on gold price fluctuations.

Questrade, on behalf of the Royal Canadian Mint, charges storage fees of about $0.10 per ounce of gold per month. There is no minimum number of ounces you need to hold, and no minimum storage charge.

Mistakes you should avoid when investing in gold

The first of the gold investing mistakes you should avoid is gold futures or options. Continue Reading…