General

Retired Money: How to beat the banks at their own game

My latest MoneySense column reviews the new book by ex banker Larry Bates, titled Beat the Bank. As the headline suggests, it’s all about how to beat the banks at their own game, which ironically can mean owning the big bank stocks themselves! The full column can be retrieved by clicking on the highlighted text here:  Tips for DIY investors on beating the Big Five banks.

The formal launch date for the book is this Thursday: September 13, 2018. I first met Bates over lunch in March as his manuscript was nearing completion, where he expounded on what he called the “two Bay Streets.” Old Bay Street and its secrets are the focus of chapters 4 and 5, and New Bay Street is chapter 6.

Old Bay Street is not the investor’s friend

Most experienced investors will have encountered Old Bay Street at some point. This is the traditional investment industry: the commission-based mutual fund and brokerage industry, insurance company reps, investment “specialists” in the bank branches and various salespeople who call themselves “advisors.”

New Bay Street = Discount Brokerage, ETFs & fee-for-service planners

The New Bay Street includes providers of low-cost index funds or Exchange-traded Funds (ETFs) or online robo-advisers that automate the purchase and rebalancing of ETFs along with setting asset allocation.

At 62, Bates is well into his own “Victory Lap,” leaving employment for self-employment. Actually, his New Bay Street model isn’t all that new, as it describes models similar to what I myself described back in 1998 in my own financial book, Findependence Day. My version consists of buying ETFs at a discount brokerage and using a fee-for-service financial planner. The same year, similar principles were also described in Stop Buying Mutual Funds!, by Mark Heinzl, now a Globe & Mail stock market columnist.

Dinosaur banks have the lowest T-REX scores

Bates has fashioned something he calls T-REX scores  This is an acronym for Total Return Efficiency Index Score. A T-REX score of 100% would be paying absolutely no fees at all, no matter how long your time horizon.

Mutual funds with 2% annual fees would have T-REX scores of 54% over 20 years and true fees of 46%, but the longer you hold, the worse the performance; thus, over 40 years the T-REX would be 41% and the true fee 59%. Fees of 3% inflict even more damage. This is the basis for his statement that long-term customers of Old Bay Street lose half their money to fees. You can find more at his website at www.larrybates.ca.

The pure DIY model of buying individual stocks or bonds at a discount broker yields the highest scores: a T-REX of 96 to 99%. (Remember, the higher the better, with 100 being perfect).

Continue Reading…

How much can you expect for investment returns?

“How much am I going to make?”

That’s likely the most reasonable question that an investor could ask. When you sign up for a savings account or GIC it’s usually the rate of return that lured you in, or got your attention. We know that many savers are ‘rate chasers’. They go from bank to bank, playing each bank against the other bank, asking for more, asking for a higher interest rate on their savings account or GIC.

I often had clients brag to me that they could get a savings account at 1.5% at so-and-so bank or credit union. I’d reply “That’s great, go for it, but I work in investments, I’m talking about earning triple or quadruple or more than that rate over time.” Of course, I would always qualify that there was the potential to earn that greater rate or return.

Did I mention that 1.5% don’t impress me much?

Of course, at this stage of the conversation I would probe the client’s savings accounts and whether or not they had a more than ample Emergency Fund. Typically, advisors will suggest that you hold 3-6 months of total spending needs in a savings account. That said, everyone knows their own personal situation and what types of emergencies that might pop up – and potentially the costs of those emergencies.

Separate short-term and long-term money

Another important practice is to separate our short-term monies and our long-term monies. Once we’re covered with that short-term emergency bucket, we move on to growth and try to make our long-term monies work real hard. You will also have day–to-day monies in a chequing or savings account.

One of the biggest mistakes Canadians make is to have too much money in “high interest” savings accounts. Guess what? That 1-2% is not going to take you to the retirement promised land. In fact, monies in a savings account are usually going backwards, it’s not making you a dime once you factor in inflation. A long term historical average for inflation is in the area of 3%. If you’re earning 2% in a savings account, you’re losing 1% spending power, each year.

Your $100,000 that you have today might feel like (or spend like) $90,000 or less in ten years. Start to extrapolate that over a few decades and the effect is greatly exaggerated. Inflation is nasty. Here’s an example that will also show my age. When I was a kid, I would take 25 cents to the movies to buy treats. With those 25 pennies I would be able to buy a pop and chips, I think I may have also been able to buy a 3-pack of gum. Yes, I also spent a lot of time in the dentist’s chair. Can you get anything for a quarter these days? I didn’t think so. Talk about losing spending power. And no, I did not grow up in the era of the Great Depression. I ‘grew up’ in the best decades of all time: the 60s and the 70s.

Only stocks can outstrip inflation

Now certainly, the 70s experienced some ‘hyper’ inflation so the effect was exaggerated. But inflation is there and it’s powerful, even in the 2.5 – 3% range. Continue Reading…

What to consider before converting your RRSP to a RRIF

By David Mortimer

(Sponsored Content)

Congratulations, you’ve retired! After many years of working and saving, the time has finally come for you to travel, spend more time with family, or do any number of activities you may not have had time for when working 40+ hours per week.

One of the first decisions you now need to consider is when to convert your RRSP to a RRIF? Technically, you are required to do so by December 31stof your 71styear, but many retirees find themselves wondering if they should do so early. Here are some things to consider before making the conversion from RRSP to RRIF.

Am I retired for good?

It’s important for people to consider whether they’ve retired for good before converting their RRSP to a RRIF. Remember it may not be so easy to turn back  after making the conversion from RRSP to a RRIF so if you are planning to return to work, even part time, you may find yourself with a tax problem if you’re working and taking an income through your RRIF. The taxes you end up paying could easily wipe out any financial gains you would make from working part time, not to mention it would not allow you the option to continue contributing to your RRSP (once converted to a RRIF), which will further reduce your taxes – providing of course you are under the age of 72!

Thinking you might like to keep busy with a part time job? Consider supplementing your finances with your tax-free savings account and non-registered investments before touching your RRSP. If you draw these out first while still working, there will be fewer tax consequences. You may also be better off taking money from your RRSP on a short-term basis rather than officially converting to a RRIF right away.

When it comes down to it, don’t collapse your RRSP into a RRIF until you’re fully retired, and have considered all your potential income streams and their potential tax consequences.

What income streams are available to you?

When making the decision on when to convert your RRSP to a RRIF, it’s important to look at how you will be funding your retirement. Do you have a workplace pension you will be receiving? What about Old Age Security (OAS) or Canada Pension Plan (CPP)? Keep in mind that your OAS has certain claw-back provisions once your income exceeds a certain threshold. Continue Reading…

Court decision on sold data access means more transparency for home buyers and sellers

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

A seven-year legal battle between the Toronto Real Estate Board (TREB) and Canada’s Competition Tribunal has come to an end, ushering in a new era for Toronto real estate data access.

On August 23rd the Supreme Court of Canada stated it would not hear an appeal from TREB to keep past sold real estate data private, following rulings from both the Tribunal and the Federal Court of Appeal that required it be made available online.

This means TREB’s online brokerage members, such as Zoocasa, are now allowed to display the historical data for individual real estate listings to site users with password-protected accounts. This information includes a home’s original listing price and sale price, its 10-year sales history, and whether it has ever had a terminated listing. Previously, clients could only receive this information once they were under contract with a real estate agent, who could provide it to them over the phone, by fax, or in person.

The move is being widely hailed as a victory, both for those who work in the real estate industry and for prospective buyers and sellers’; but how will it change today’s real estate market?

A boon for Buyers

Perhaps the biggest benefit for buyers will be the improved transparency around home prices. While having access to the data is unlikely to prevent bidding wars, it will mean shoppers will have a better idea of what condos and houses for sale are truly worth before they put in an offer.

It will also decrease price lowballing, a strategy in which sellers list their homes for a much lower amount than they expect to receive. This piques the interest of buyers looking for a great deal, often leading to multiple-offer situations and hyper-inflated prices. It’s an especially common tactic in hot markets, such as on the Toronto or Vancouver MLS, and a constant source of frustration for buyers trying to find homes that are actually within their budgets.

Now, buyers will be able to see what comparable homes are selling for in the same neighbourhood, and whether their desired listing has been priced accurately.

Greater strategy for Sellers

This doesn’t mean sellers will receive the short end of the stick: they’ll now have more information than ever to inform their decision to list. Continue Reading…

How investing makes it easier to achieve Financial Independence

By Gary Bordeaux

Special to the Financial Independence Hub

If you are looking for a way to secure your financial future, learning how to invest your money can help accomplish that goal. There are a variety of investment vehicles that can be tailored to fit your needs, timeline, and risk tolerance.

Let’s take a look at some of the specific reasons how investing helps a person obtain financial independence (aka “Findependence”).

Make money both today and tomorrow

If you are interested in generating a steady income from your investment portfolio, you can buy dividend stocks or a REIT (Real Estate Investment Trust). You make money today by receiving a dividend payment every month or quarter. You make money in the future by holding the security as it appreciates in value. When it reaches what you feel is the height of its value, feel free to sell it and lock in a profit. It is also possible to hold stocks in a trust that can benefit children, grandchildren or other beneficiaries after you pass on.

Obtain returns greater than the Rate of Inflation

Thanks to inflation, a dollar that you hold in your hand today will be worth the equivalent of 98 cents a year from now. This is because the price of goods will increase by an average of 2 per cent per year. In some cases, inflation can reach 4 per cent or greater in a given 12-month period.

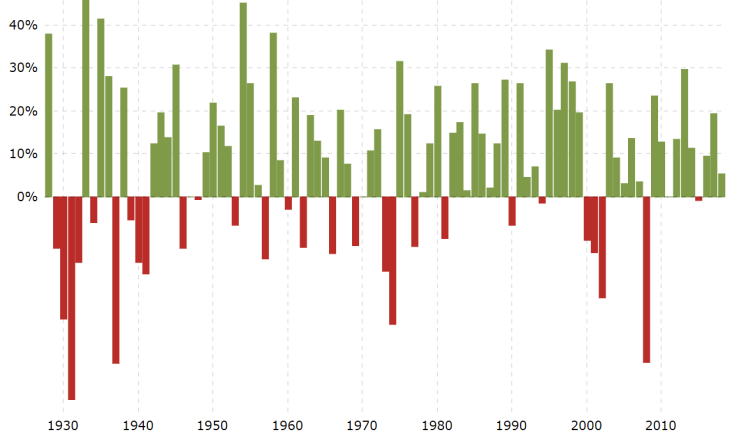
As a general rule, stocks will appreciate by about 7 per cent per year, and that amount is higher if a stock offers a dividend. What this means is that you are increasing your net worth above what it takes to keep up with cost-of-living increases. Over a period of years or decades, you could accrue tens or hundreds of thousands of dollars that can be used to enhance your lifestyle.

Improve your chances of owning a home

Let’s say that you are looking to buy your first house. You could decide to buy a single-family unit with a monthly mortgage of $1,000 that you are responsible for paying on your own. However, another option is to buy a duplex that you can both live in and derive income from. At the very least, having a tenant living in the other half of your home will decrease the monthly mortgage payment.

The money that you save can then be used to improve the home or make other investments. If you make improvements to a property that is used for rental purposes, it may be possible to write off the amount of those repairs on a state or federal tax return. Continue Reading…