General

Underinvested in China? How to invest in the “New China” Economy

Highrises in Shanghai’s new Pudong financial district.

By Caroline Grimont

(Sponsor Content)

Investors are missing out on strong growth opportunities by being underinvested in China:  the world’s most populous country and second largest economy.

Since China slowed down from two decades of near double-digit growth, investors have become skeptical about investing in the country.

They worry about the country’s macro challenges; among them, a high leverage ratio resulting from a rapid buildup in debt over the past 10 years, excess capacity in industrial segments, an over-reliance on investment as a growth driver, and more recently, the risks of protectionism.[i]

In our view, these challenges are overstated. China has the capacity to overcome them and has taken a measured approach to sustain its growth, albeit at a slower pace.   The Chinese economy has grown almost ten-fold from US$ 1.2 trillion in 2000 to US$ 11.2 trillion in 2016, second in size only to the US.  Given the size of China’s economy now, a slower more sustainable rate of growth makes sense.

Our view is shared by Morgan Stanley, which states: “We expect China to avoid a financial shock and achieve high income status by 2027. Our view is that moving to higher value-added activities will propel the economy forward and drive the continued medium term outperformance of MSCI China versus MSCI EM, providing significant investment opportunities.”[ii]

China accounts for almost 50% of global economic growth

China remains one of the fastest growing economies in the world, with a forecasted growth rate of 6.5% in 2017 and 6% in 2018. On a global scale, China represents 15% of the world’s economy and accounts for close to 50% of global economic growth.

Continue Reading…

Alternative Investments for the Masses

Is it time for the average investor to look into alternative investments to the traditional balanced portfolio of stocks and bonds?

In a column in Thursday’s Globe & Mail Report on Business, I look at a relatively new mutual fund from Mackenzie Investments that gives both average and affluent investors a way to diversify their portfolios into alternative investments or asset classes.

You can find it by clicking on the highlighted headline: Alternative Investing for the Masses.

The Mackenzie Diversified Alternative Fund (“MDAF”) is positioned as a low-risk way to diversify beyond the typical “balanced” fund or balanced portfolio of stocks and bonds. As the article says, both traditional stocks and bonds appear pricey at this juncture, and studies show that putting up to 20% of a total portfolio can smooth returns. Indeed, many giant pension funds have far more than that, including such well known pensions as Ontario Teachers and OMERs.

Non-traditional asset classes seen as “alternatives” include private equity, infrastructure, emerging-market debt, limited partnerships and a host of other investments not easily accessed by the average investor. Pension funds can get their own direct access to alternatives but for individuals many were available only through “offering memorandums” available only to those considered sophisticated investors: with $1 million in investible assets or combined annual family income of $300,000.

Low entry point, liquid

By contrast, the Mackenzie fund can be purchased for as little as $500, like most mutual funds, and unlike many hedge funds, can be liquidated on demand like any other mutual fund.

The article goes into the fee issue: the A series has an Management Expense Ratio (MER) of 2.42% and the F series 1.25% (advisors will then tack on their own fee, typically another 1%). But affluent investors get a price break under the Mackenzie Private Wealth Solutions’ preferred-pricing program, with the basic management fee for household wealth in all Mackenzie funds tapering down from 0.8% to as little as 0.5% for $5 million dollar portfolios.


Is the Fixed Income Market buying what the Fed is Selling?


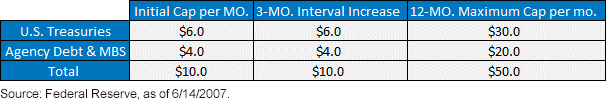
Fed’s Balance Sheet Normalization Guidelines (in billions)

By Kevin Flanagan , WisdomTree Investments

Special to the Financial Independence Hub

In the post-Federal Reserve (Fed)-meeting world of the money and bond markets, there seems to be a disconnect between what market participants are thinking and the Fed policy decisions actually being made. It is a case of the market not buying what the Fed is selling.

In other words, the term “policy mistake” has begun to enter the discussion, as the U.S. Treasury (UST) arena appears to be operating under the assumption that the Fed should perhaps ease up on its tightening campaign because

(a) inflation has been slowing in recent months, and

(b) economic growth has been lackluster. This line of reasoning concludes that the policy makers will go too far with their rate hike and balance sheet normalization plans, to the detriment of the economic setting.

Based on the Fed’s actions at the June FOMC meeting, the policy makers do not seem to be deterred in their “full steam ahead” outlook, as they envision yet another rate hike this year and expect “to begin implementing a balance sheet normalization program this year” as well. (On Wednesday, July 27, the Fed kept interest rates unchanged — Editor.)

So, let’s assume economic and financial conditions do live up to the Fed’s expectations, what then will their plan look like for phasing out their reinvestment program.

Continue Reading…

Can you retire on a million dollars?

In your 20s and 30s, retirement is so far away that you can barely see it on the horizon. The best way to get there is to save what you can afford – say 10 per cent of your income – and then readjust your financial compass as you get closer and have more information.

You might start the journey with the idea that you need a million dollars or more once you reach your destination. To get to one million by age 65, a 30-year-old would need to save $8,500 per year for 35 years, assuming a 6 per cent annual return.

Saving for Retirement

It’s not easy to save $700+ per month in your thirties. Competing priorities like a mortgage, car payments, and raising children often means that retirement savings are put on hold.  Put off saving until you reach 40 and you’re now faced with the daunting task of saving more than $1,400 per month for the next 25 years to reach that million dollar mark.

Some might feel it’s prudent to pay off the mortgage and max out children’s RESPs before ramping up their own retirement savings. By age 50, most of those obligations should be taken care of which should now free up significant cash flow to save for retirement. It’ll need to be significant to reach a million. With only 15 years to go now, compound interest is not on your side, and so you’ll need to save nearly $3,400 per month – or $40,000 per year – to get to your retirement goal.

A tempting alternative at this point is to adjust your expected rate of return. After all, with an 8 per cent return you’d only need to save $2,800 per month, and at 10 per cent you’d need to put away less than $2,400 per month.

But the more realistic approach would be to adjust your expected retirement age and then figure out if a million dollars is really the amount you need to enjoy a comfortable retirement. You’d be surprised to learn you can live off much less.

Related: Have you considered a permanent retirement overseas? Read this:

Continue Reading…

Cryptocurrencies 101: “So what the heck am I supposed to do?”

By Tony Humble

Special to the Financial Independence Hub

If you are like 99.9% of Canadians, you are probably wondering what this crypto-thing is all about.  Your stream of consciousness likely goes something like this: What is Bitcoin?  And what the heck is Ether?  Will they change my life?  How can I make money on it? Could I lose money on it? What….?”

Allow me to open the secret door a crack for you.

At this moment in time, the early adopters are cleaning up.  They saw the potential of Bitcoin and Ether, and bought it when it was cheap.  Now they are sitting on a pile of value, much like Amazon investors who bought at the IPO price of  $16.00 in 1997 – except they have only seen a 64-times growth, to $1,010 today.  The cab driver in Calgary who took Bitcoin for a $5 fare a few years ago years ago is reportedly now a multimillionaire.

There is still money to be made, however, which is why you are seeing somewhat self-serving forecasts by service providers and pundits, of Bitcoin and Ether in particular hitting $20,000 and more.  That could happen, but so could Dow at 100,000, and as most of us know, the road to that particular Nirvana is full of potholes and unexpected dips and swerves.

Cryptocurrencies are not “securities”

Importantly, cryptocurrencies are not “securities” and do not appear to fall under the rules of most of the Western regulatory system that governs the sale of securities.  That of course would appear to free this new highly valuable (and growing) form of electronic money from the constraints faced by “unaccredited” investors.  Right now, if you want to buy a piece of a private company, you cannot buy their securities from a financial intermediary unless you meet the extremely high bar set by the regulators.

Continue Reading…