Posted By
By Michael Greenberg and Wylie Tollette
(Sponsor Content)
The 60% stocks and 40% bond (60/40) balanced portfolio ― or 70/30 depending on your risk tolerance and time horizon ― has helped many investors build wealth over the past 20 years. It’s a simple recipe for success that has relied on four basic market expectations:
1.) Positive longer-term returns for stocks, driven by underlying economic growth
2.) Falling ― but still positive ― yields on bonds, particularly sovereign bonds
3.) Low and contained inflation
4.) Negative correlations between stocks and bonds (move in opposite directions), particularly during recessions
This last expectation has been especially important. When equity markets are under stress, central banks traditionally have been able to reduce short-term interest rates, increasing the value of nominal bonds. Investor flight to safe-haven assets and quantitative easing (QE) programs initiated by central banks also provide a price boost to the asset class. This helps offset the decline in equities and provides portfolio managers with “dry powder” to reinvest in newly cheap stocks.
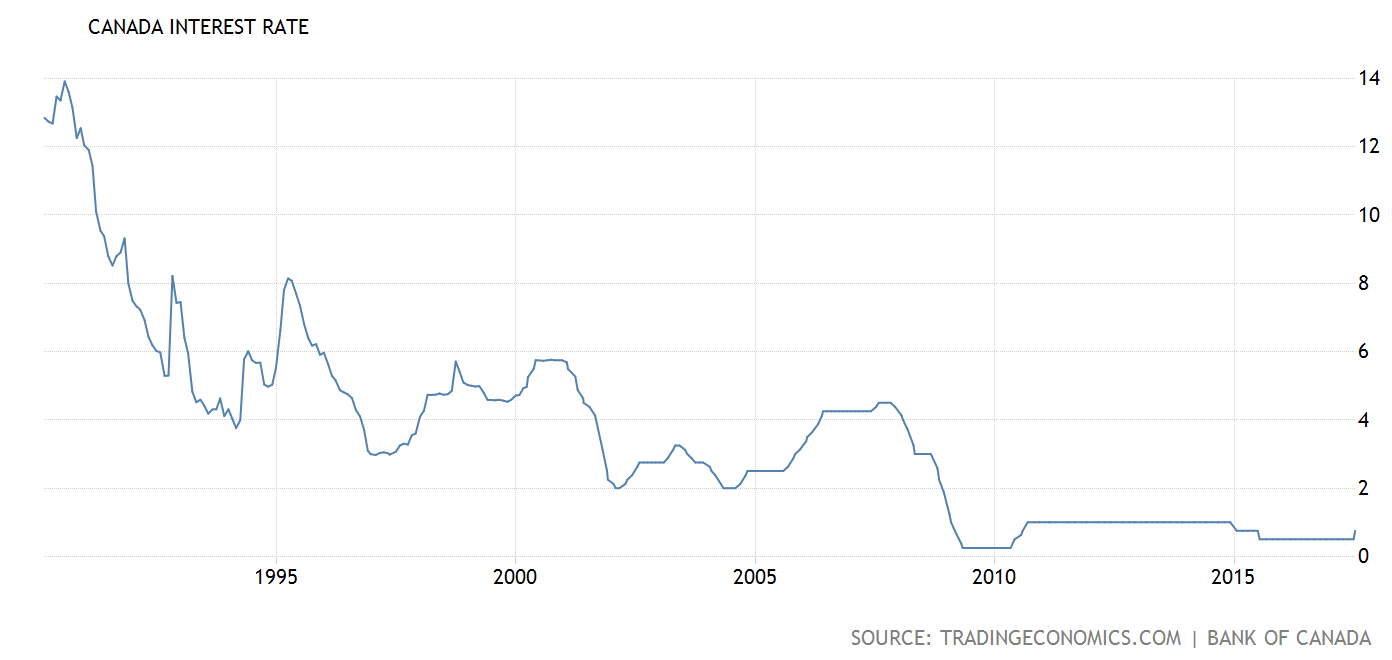
But the world has changed. With sovereign bond yields approaching zero in many countries, does this basic equation still hold?
Four Strong (Head)Winds
Today, the 60/40 portfolio faces four formidable headwinds:
- Low bond yields – for the past 35 years, yields have fallen and stayed near historic lows. Investors have offset those declines by increasing equity risk; but in a balanced portfolio, more risk means more volatility.
- Reduced negative correlation impact – with such low yields, the sought-after negative correlation between bonds and stocks may diminish.
- Waning disinflation –increasing pressures on inflation from aggressive monetary and fiscal stimulus, increased protectionism/nationalism, and supply chain disruption/re-shoring could lead to higher yields, which would hurt bond prices.
- Limited monetary tools — near-zero/negative interest rates and bloated balance sheets mean less ammunition for central banks to fight the next economic downturn. A move to heavier fiscal policy and resulting increased government bond issuance would also hurt bond prices.
The Real Price of Risk
At this point, taking on more risk may not be worth the incremental return. If your cash flow is negative, you won’t be able to rely on equity risk to carry the load. To fund those cash flows, you would need to sell securities periodically, which introduces timing risk. At the worst, you could be forced to sell a long-term asset during a bad short-term stretch in the markets.
Evolve, don’t abandon
Do these changing conditions mean the trusty 60/40 portfolio should be completely scrapped? We don’t think so. Here are some ways to bring your balanced portfolio up to speed:
- Adjust your return expectations. Yes, the contribution to returns from bonds will be much lower. On the other hand, we think there is likely a cap on how far and fast yields could rise. That will limit the downside. We suggest a long-term return of 4-5% is a reasonable expectation for a 60/40 portfolio (excluding potential value add from dynamic asset allocation and active security selection).
. Continue Reading…
 Posted By