Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Your business is your retirement plan. Here’s how to make it worth what you need

Image by Pexels/Zeynep Sude Emek

By Arvin Mondano

Special to Financial Independence Hub

In a recent Findependence Hub roundup on FIRE, Loretta Kilday of DebtCC said most FIRE folks she’s encountered “don’t actually stop working; they stop working for someone else.” Business owners made that move years ago, which leaves them with a different retirement problem: for many of them, the company is the nest egg. The RRSP got whatever was left after payroll, and the plan has always been to sell.

That plan works when the sale price covers the retirement. It fails quietly when the owner learns what a buyer will pay only after deciding to retire. The fix is to run the numbers the other way around, years before you list.

Start with the number your retirement needs

Begin with the income you want, not the price you hope for. Say you need $60,000 a year on top of CPP and OAS. Using the 4% rule as a rough guide, that takes a portfolio of about $1.5 million. If your RRSP, TFSA and other savings already hold $400,000, the sale has to deliver roughly $1.1 million after tax, legal costs and any broker’s commission.

Your accountant can turn that into a pre-tax sale price. For this example, call it $1.3 million. What matters is having a target before you ever have an asking price. Owners who skip this step tend to price on what the business means to them. Buyers price on what it earns.

What buyers actually pay for

Buyers of owner-run businesses price them on the seller’s discretionary earnings, or SDE: pre-tax profit plus the owner’s salary and perks, plus one-time and non-cash expenses. It’s the cash flow a single owner-operator could take out of the business in a year.

The price is a multiple of that figure. Most small, owner-operated businesses in Canada sell for somewhere between two and three and a half times SDE. Where yours lands depends on how clean the records are, whether earnings are rising or falling, whether a few big customers make up most of your sales, and how much the business depends on you.

Now run your retirement math against it. Divide the price you need by a realistic multiple and you get the SDE the business has to show. At a multiple of 2.5, a $1.3 million sale needs about $520,000. If the business shows $350,000, it’s worth closer to $875,000, which leaves a $425,000 hole in the plan. Far better to find that out now than in the first offer.

The add-backs buyers accept, and the ones they don’t

Add-backs are where most price arguments start, because every dollar of SDE is worth two dollars or more of price. Buyers generally accept the ones they can verify: your own salary and benefits, personal costs run through the business such as a vehicle or phone, true one-time expenses like a legal settlement or a move, and depreciation and interest. Continue Reading…

Retired Money: Book Review of David Booth’s Stay Calm

As we telegraphed in the September installment of my MoneySense Retired Money column, this month’s column is a book review of David Booth’s Stay Calm, published early in September. For the full review in the October column, click on the highlighted headline: The calming genius of passive investing.

David Booth is founder of Dimensional Fund Advisors (DFA), maker of DFA Index Funds and DFA ETFs. I have long invested some of our family’s money in DFA funds, along with many of the other usual indexing suspects.

They are famously champions of taking a passive set-it-and-forget it approach to investing while minimizing the noise of what they have dubbed “financial pornography” propagated by traditional and social media, and the self-appointed experts who claim they can pick individual stocks or consistently time the markets.

As someone who takes a decidedly hybrid approach to investing in ETFs in various asset classes, — and occasionally indulging in a bit of high-conviction “index skimming” — I found Booth’s Stay Calm to be a refreshing reminder of the sound principles that underlie DFA.

Those who need a refresher on the virtues of passive investing will not be disappointed but as the book’s subhead implies, there are also quite a few lessons about embracing uncertainties in life in general, as well as investing in particular.

Stay Calm was published early in September by Authors Equity and is aptly subtitled “Learn to Embrace Uncertainty in Investing and Life.”  The book is divided into three main parts. Part 1 is on the science of investing and covers the Gift of being an Outsider, how Markets work and how to harness public markets. Part 2 is titled “The Mindset to Stay Calm” and the four chapter titles all make for excellent bullet points; Flexibility is the key to navigating Life’s Uncertainties; Don’t Predict, Plan; Control what you can control and manage what you can’t; and Tune out the Noise.

Continue Reading…

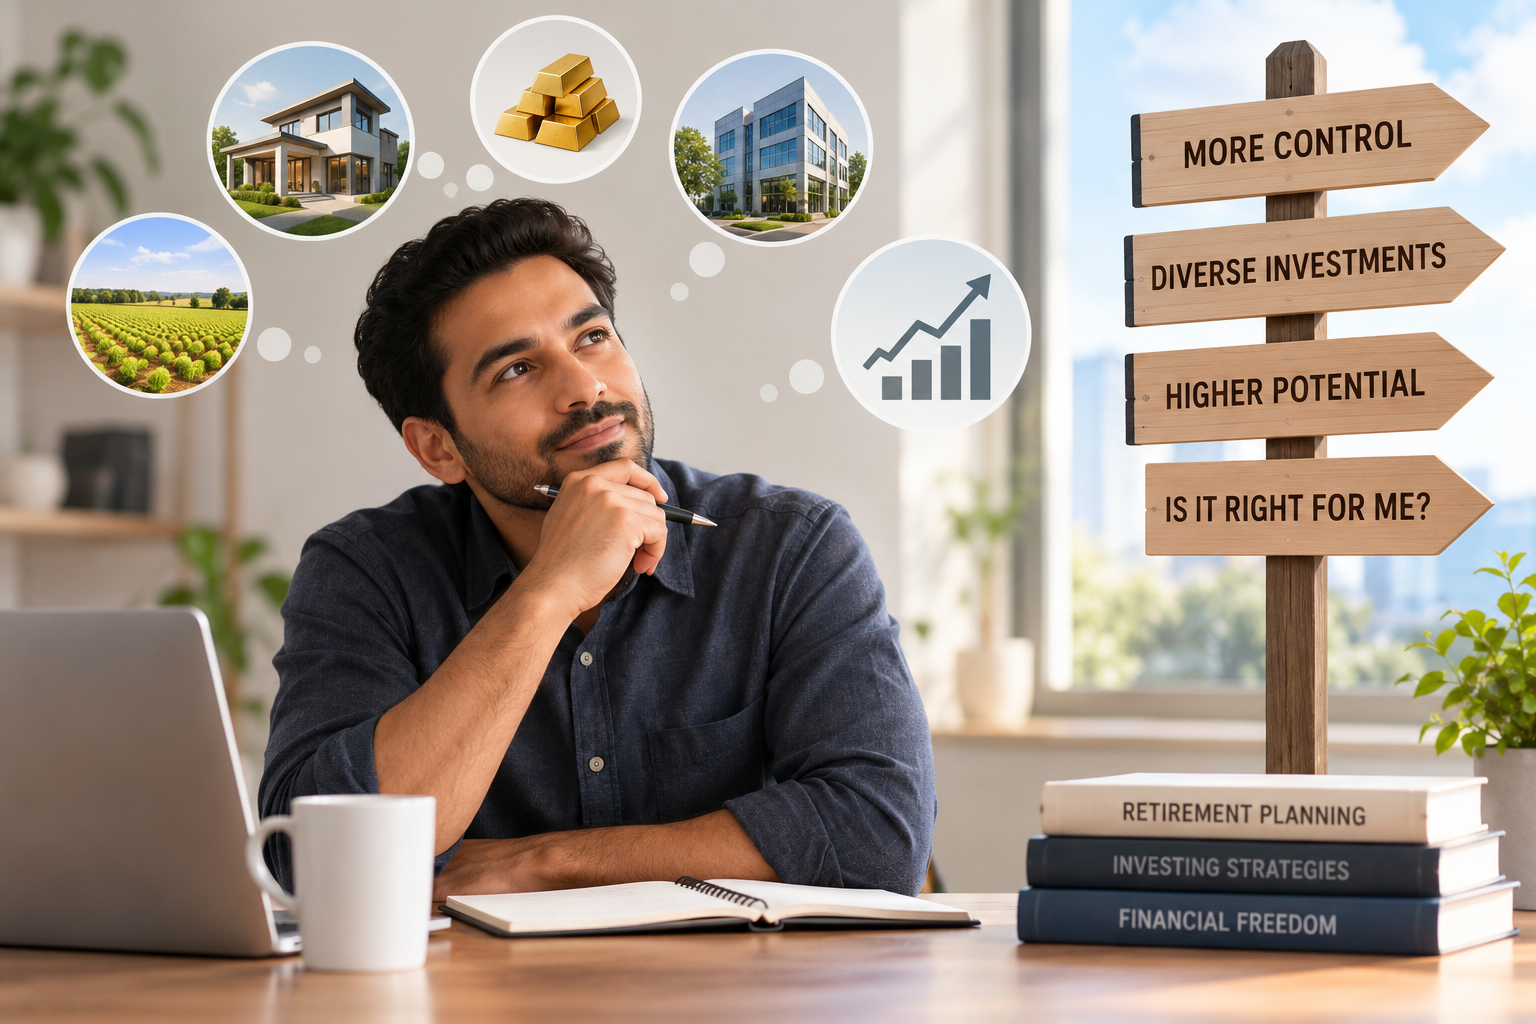
Is a Self-Directed IRA right for you? 7 Questions every investor should ask

Image created by the author with ChatGPT

By Donnell Stidhum, Self Directed Retirement Plans LLC 

Special to Financial Independence Hub

A self-directed IRA has become one of the most talked-about retirement accounts among investors looking for greater control over how they build wealth.

The appeal is easy to understand. Unlike many traditional retirement accounts that limit you to stocks, bonds and mutual funds offered by a brokerage, a self-directed IRA can provide access to a much broader range of investments, including real estate, private lending, private equity and certain precious metals, provided IRS rules are followed.

But here’s what I tell people during our conversations: having more investment choices doesn’t automatically mean a self-directed IRA is the right choice for you.

Over the years, I’ve seen investors open these accounts because they heard someone made money buying rental properties or investing in private companies. Unfortunately, some discover too late that the flexibility also comes with greater responsibility.

Before opening a self-directed IRA, I encourage people to slow down and ask themselves seven important questions:

1.) Do I understand the investment I’m buying?

This is always my first question.

A self-directed IRA allows you to invest beyond publicly traded securities, but it doesn’t eliminate investment risk. In fact, many alternative investments require even more due diligence because they aren’t traded on public exchanges and often have less transparency.

If you can’t clearly explain how an investment makes money, what could cause it to lose value and how you’ll evaluate its performance, you’re probably not ready to place retirement dollars into it.

Retirement investing isn’t about chasing opportunities. It’s about making informed decisions

2.) Am I looking for flexibility or simply chasing higher returns?

Many investors assume that because a self-directed IRA offers more choices, it must produce better returns.

That’s not how investing works.

The account itself doesn’t create performance. The investment decisions do.

I’ve met investors who have built substantial retirement wealth using traditional index funds. I’ve also met investors who have done exceptionally well with real estate inside a self-directed IRA. The difference wasn’t the account, it was their knowledge, discipline and long-term strategy.

Choose the account because it fits your investment approach, not because it promises bigger returns.

3.) Can I follow the IRS rules?

This is where many investors underestimate the complexity.

The IRS allows a wide range of investments, but it also has strict rules governing prohibited transactions and self-dealing. For example, you generally can’t use IRA-owned property for your personal benefit or engage in certain transactions with yourself or other disqualified persons. Violating these rules can jeopardize the account’s tax-advantaged status.

The rules aren’t designed to discourage investing. They’re designed to preserve the integrity of retirement accounts.

Before investing, understand the rules as carefully as you study the opportunity itself.

4.) Is this investment liquid enough for my retirement plan?

Liquidity is often overlooked.

Suppose your retirement account owns a rental property or a private business interest. Those assets may take months, or even longer, to sell.

That doesn’t necessarily make them poor investments, but it does mean your retirement strategy should include enough liquidity to meet future needs.

A diversified retirement portfolio shouldn’t leave you scrambling for cash because every investment is tied up in long-term assets.

5.) Am I properly diversified?

One of the biggest mistakes I see is concentration.

An investor becomes excited about real estate and moves nearly all of their retirement savings into a single property.

Another puts everything into one private company.

Diversification still matters. Continue Reading…

Cognitive Decline and your Finances

Image via Pexels: SHVETS production

By Michael J. Wiener

Special to Financial Independence Hub

One of the talking points of financial advisors is that even if right now you’re able to handle your own investments, tax planning, and other aspects of personal finance, you may face cognitive decline later in life.  The implication is that maybe you should get a financial advisor now before it’s too late.

The challenge here is that many people who hold themselves out as financial advisors are little more than sellers of expensive mutual funds.  Some might even be inclined to take advantage of your cognitive decline to churn your account and generate excess fees.

What you may need is a good financial advisor.  Some financial advisors are excellent.  They range from those who charge by the hour for “Advice Only” to those who manage your investments directly for you.  However, if you’re in cognitive decline, it won’t help to just get the occasional portfolio checkup.  The advisor would have to directly manage your investments.  But it’s hard to get this type of advisor without at least a million dollars invested.

If you do meet an advisor’s asset threshold, you’re still faced with the dilemma of determining whether you’ve found a good advisor.  One strategy is to reduce the size of the problem.  The more guaranteed income you have, the less important your investments become.  If you or an advisor mangle your investments, having a higher guaranteed income will be valuable.

Here are three possible ways to increase retirement income:

1.) Delay the start of CPP and OAS

The formula for increasing CPP and OAS benefits if you delay their start is quite generous.  Any delay up to age 70 gives you more money per month.  The fact that these benefits are indexed to inflation is very valuable.

2.) Buy an annuity

Typically annuities are not indexed at all, but you can get one whose payments increase annually by a fixed percentage, such as 2%.  Buying annuities isn’t as beneficial as delaying CPP and OAS, but it does create more guaranteed income to protect you from yourself in the case of cognitive decline.

To reduce inflation risk, you could wait until later in life (but not too late!) to buy an annuity.  One strategy might be to buy more than one annuity at different ages.

3.) Work somewhere that offers a defined-benefit pension

This option is certainly more extreme than the other two, particularly if you would have to change careers.  But if it’s something you don’t mind doing, a defined-benefit pension takes away many retirement worries.

Family help

Another alternative to getting a financial advisor is to get help from younger family members.  I’ve gone to a lot of trouble to learn how to invest, manage taxes, and run the rest of my personal finances.  I’ve been passing this knowledge along to my sons in small steps.

A time will come when I’ll start showing them how my finances work in preparation for when they might have to start helping.  This feels natural for me, because once my wife and I are gone, they’ll get what’s left anyway.

Not everyone has family members whose intelligence and morals they trust enough for this kind of help.  But if you do, they can help protect your finances from your mistakes.

The financial advisor path

A good financial advisor is likely to benefit you most when family assets are complex.  But you still have the challenge of figuring out whether a financial advisor is good and honest.  I feel like I have the knowledge to judge an advisor’s competence, but you almost have to know how to do it yourself to be able to judge an advisor. Continue Reading…

Retirement Spending: Why Spending your Savings is the Hardest Part of Retirement

AlainGuillot.com, via ChatGPT

By Alain Guillot

Special to Financial Independence Hub

I have an unusual retirement problem. I have more money than I’ll probably ever spend.

For most of my adult life, retirement spending was never something I worried about. Saving was.

Like millions of people, I spent decades training myself to save every extra dollar. I invested consistently, avoided unnecessary purchases, resisted lifestyle inflation, and watched my retirement accounts grow year after year.

Today, at 59 years old, I am financially independent.

Ironically, I’ve discovered that spending money is far more difficult than earning or saving it.

I don’t need to work another day in my life, yet I continue working because I genuinely enjoy what I do and I don’t know what to do with myself if I don’t have this daily activity called work. Meanwhile my investments continue to grow faster than I can realistically spend them.

The problem isn’t that I don’t have enough money.

The problem is that I no longer know how to spend it.

And it turns out I’m far from alone.

Retirement Spending is Harder than Saving

A recent Corebridge Financial survey found something surprising.

  • Fewer than one third of retirees feel comfortable withdrawing money from their retirement savings.
  • Seven out of ten retirees say it’s very important that their nest egg never shrinks.
  • Thirty-eight per cent admit they deliberately avoid spending money simply to preserve their savings.

Think about that.

People spent forty years saving for retirement…

… and once retirement finally arrives, many refuse to spend the money they worked so hard to accumulate.

That seems irrational.

Until you realize we’ve spent our entire lives being rewarded for saving.

We train ourselves to Accumulate, not Decumulate

Every paycheque teaches us the same lesson.

Save more.
Invest more.
Increase your net worth.
Watch the graph go up.

Personal finance books celebrate growing investment balances.

Financial news celebrates higher account values.

Net worth becomes the scoreboard.

Then retirement arrives and suddenly we’re expected to reverse decades of conditioning.

Instead of accumulating wealth, we’re supposed to slowly spend it.

Psychologically, that’s an enormous shift.

For many retirees, watching their investment account decline — even if it’s exactly according to plan — feels like failure.

My Retirement Spending Problem

When I imagined retirement in my Twenties, I assumed I would eventually spend money on expensive things:

A luxury car.

A larger house.

Designer clothes.

Fine dining every night.

None of that happened.

I live in Montreal, where owning a car would mostly be an inconvenience.

I have a comfortable apartment that suits me perfectly.

My wardrobe is simple. A good polo shirt lasts for years.

My favorite hobby is salsa dancing, and the best dance floor in the city is … free.

I eat out regularly, but because my cholesterol is high, my doctor has encouraged me to follow a mostly plant-based diet. Ironically, eating more healthily often costs less than dining out. And when I go out to eat, I go to small neighborhood restaurants to encourage the local owners. The waiters know me, the owners know me, and I feel at home.

I already take two international vacations every year.

Beyond that, I honestly don’t know what else I need.

The result?

My portfolio keeps growing because my spending simply hasn’t caught up with my savings.

Retirement Spending doesn’t mean Spending Carelessly

Many people hear this discussion and think the solution is simple:

“Just buy more stuff.”

I disagree completely.

Financial freedom isn’t permission to become a reckless consumer.

It’s permission to make choices based on happiness rather than necessity.

The goal isn’t to maximize spending.

The goal is to maximize fulfillment.

Sometimes that means spending more.

Sometimes it means spending exactly the same while feeling less guilty about it.

Better ways to Practice Retirement Spending

If you’ve accumulated more than you’ll likely spend, consider investing in experiences rather than possessions.

Some ideas include: Continue Reading…