Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Why does the Stock Market Rise when the News looks Bad?

Lowrie Financial: Custom Creation with Claude

By Steve Lowrie, CFA

Special to Financial Independence Hub

Short answer: stock prices reflect what investors expect to happen in the future, not what the headlines are reporting today. Markets rise when outcomes turn out better than investors feared, even if conditions still look bad.

By the time a story feels alarming enough to act on, the market has usually already priced it in. That’s why reacting to headlines rarely works, and why discipline tends to beat prediction.

Every market cycle seems to produce the same question. The headlines are negative. Investors are worried. Economists are warning about risks. Yet the stock market keeps climbing a wall of worry. How can both things be true?

It’s one of the most common investing questions I hear, and it usually sounds something like this:

“I don’t understand it. There’s a war in the Middle East. Governments are running massive deficits and have accumulated huge amounts of debt. Economists keep warning about recessions. Every day the news seems filled with uncertainty and risk. So why is the stock market near record highs?”

It’s a fair question, and if you’re asking it, you’re not alone. The answer comes down to one of the most important concepts in investing:

Markets Live in the Future

That may sound like a strange statement at first. After all, investors own businesses that operate in the real world today. Shouldn’t stock prices reflect what’s happening right now?

To a degree, they do. But the value of any business depends far more on the profits it’s expected to earn in the future than on the profits it earned last quarter. Every day, investors around the world are trying to answer the same question: what are those future profits worth today?

To answer it, they evaluate interest rates, inflation, economic growth, corporate earnings, government policy, geopolitical risks, and thousands of other pieces of information. As those expectations change, stock prices change. That’s why stock prices often seem disconnected from the headlines, and it’s where many investors get tripped up.

We naturally assume stock prices should move in response to what’s happening in the economy today. If growth slows, unemployment rises, or geopolitical tensions increase, it seems reasonable to expect stock prices to fall. But there’s an important distinction.

Most financial news and economic data tell us what has already happened. In many cases, that information is weeks or even months old by the time it’s reported. The stock market, on the other hand, is constantly trying to estimate what happens next.

I often think of financial news and economic data as a rearview mirror. They help us understand where we’ve been.

The stock market is the windshield. Investors are looking ahead, trying to estimate what businesses, profits, interest rates, and economic conditions might look like in the future.

Once you understand that difference, it becomes much easier to see why headlines and market performance so often seem disconnected.

Why does the Stock Market Rise when the News Looks Bad?

One of the biggest misconceptions in investing is that markets move based on whether news is good or bad. In reality, markets tend to move based on whether outcomes are better or worse than expected. That may sound like a subtle distinction, but it’s an important one.

Imagine investors become convinced a severe recession is coming. Businesses prepare for it. Economists forecast it. Investors position their portfolios for it. If the economy ultimately experiences only a mild slowdown, stock prices may rise even though conditions look bad. The outcome wasn’t necessarily good; it was simply better than investors feared.

The opposite happens all the time too. A company can report record profits and still see its stock price fall, because investors expected even better results. Markets are constantly comparing reality against expectations.

That may sound abstract, but history gives us a powerful example. During the global financial crisis, stock markets reached their lowest point in March 2009. At the time, the news was still overwhelmingly negative. Unemployment continued rising. The economy remained weak. Many investors were convinced conditions would deteriorate further, yet the market began recovering.

Investors who waited for reassuring headlines missed a significant portion of that recovery, because the market wasn’t waiting for conditions to improve. It was already looking ahead to a future in which they eventually would.

Investors who wait for good news often discover that the stock market has moved higher long before the headlines improved.

That’s what I mean when I say markets live in the future.

What does “It’s Already Priced In” mean in Investing?

This idea also explains one of the most misunderstood phrases in investing. You’ll often hear investors say something is “already priced in.” What they mean is that the market has already incorporated known information into stock prices.

By the time most of us hear a major news story and start wondering what it means for our investments, millions of investors around the world have already evaluated that information and built their views into prices.

That doesn’t mean markets are always right. Far from it. Markets can be overly optimistic. They can be overly pessimistic. Prices can move too far in either direction. But current prices generally reflect the collective expectations of investors based on everything they know today. Put another way, they give the best available estimate of what a company is worth right now.

For prices to move significantly, something usually has to happen that differs from those expectations. That’s why major headlines often have less impact on markets than people expect. Investors aren’t reacting to the news itself. They’re reacting to whether the news is better or worse than anticipated.

Why is Market Timing so Difficult?

Once you understand how markets work, it becomes easier to see why market timing is so challenging. To successfully move in and out of the market, you have to do more than predict what will happen next. You also have to predict what millions of other investors expect to happen and then determine whether reality will turn out better or worse than those expectations. That’s an extraordinarily difficult task.

It’s one of the reasons decades of academic research have found that consistently outperforming the broad stock market is so difficult. Whenever someone tells me they believe the market has it completely wrong, I think it’s worth asking a simple question: who exactly are they betting against?

At any given moment, stock prices reflect the collective judgment of massive pension funds, sovereign wealth funds, hedge funds, insurance companies, analysts, economists, business leaders, professional investors, and millions of individual investors around the world. Could the market be wrong? Of course. But consistently identifying mispricing and systematically profiting from it before everyone else is remarkably difficult. Decades of evidence suggest very few investors do it successfully over long periods.

What is the Practical Lesson for Investors?

The practical lesson isn’t that markets are perfect. It’s that reacting to headlines is usually not a successful investment strategy. By the time a story feels important enough to make you want to change your portfolio, the market has often already processed that information and adjusted accordingly.

This is worth saying clearly, because it’s easy to take the idea too far. “It’s already priced in” is a reason to ignore the daily news cycle. It is not a reason to ignore your own plan. Rebalancing back to your target mix, adjusting your portfolio as your goals and time horizon change, and managing risk, taxes, and costs are all decisions driven by your circumstances, not by the headlines. Discipline doesn’t mean doing nothing. It means acting on your plan rather than on the news.

So this doesn’t mean investors should ignore the news. It means they should be careful about making investment decisions based on it. Successful investing is rarely about predicting the next headline. It’s about building a sensible portfolio, staying disciplined during periods of uncertainty, and focusing on your long-term plan rather than the daily news cycle.

The next time you find yourself wondering why the stock market is rising despite negative headlines, remember that investors aren’t just evaluating what’s happening today. They’re trying to estimate what happens next, and more often than not, the market begins looking ahead long before the rest of us do.

That’s why markets can reach new highs during periods that feel uncertain, uncomfortable, or even frightening. And it’s why some of the best investment decisions are often the ones that feel hardest in the moment: staying disciplined, ignoring the noise, and sticking to a well-thought-out plan when the future feels least certain.

Frequently Asked Questions Continue Reading…

Retired Money: How to use AI to get to Retirement and to enjoy it once there

Image Freepik, courtesy MoneySense.ca

My latest MoneySense Retired Money column went live on Friday. You can read it by clicking on the hypertext link: Is AI the ultimate Retirement Hack? 

The column was initially sparked by reading I am not a Robot, which is subtitled “My year of using AI to do almost everything.” While while author Joanna Stern’s focus is on using AI to enhance her worklife and personal and family life, my primary interest is on AI and retirees.

I was interested in what the experts might say about, first, how AI can be used by those hoping to retire to speed up the process and the planning; and second, once achieved, how AI can be used to help new retirees spend all that abundant leisure time.

Here on Findependence Hub, we once again reached out to almost 20 financial experts and business owners through Linked In and Featured.com. You can find the link to the full 6,000 word (or so) blog here, which presents the entire responses of 18 experts chosen from more than 50 submitted. The Retired Money column is shorter, touching on the highlights and my impression of the book and its implications for new retirees.

As more than one of the contributors noted, it’s ironic that getting up to speed on AI in all its aspects can itself become a full-time job; fortunately time is one commodity retirees should have plenty of! If pressed for time, you can skim the 18 topline headlines in the long blog, skipping to the content that interests you.

Stern’s book came to my attention via an interview with her by Jim Cramer in his Mad Money podcast. Cramer himself appears to be immersed in every AI tool from Claude to Google’s Gemini. The book quickly made it on to the NYT bestseller list.

As I confess in the MoneySense column, while my family members play around with some of these tools, I’ve not yet immersed myself in them, although I find AI to be an interesting theme as an investment, if only through an ETF like AIS , the VistaShares Artificial Intelligence Supercycle ETF.

JoannaStern.com

Indeed, Stern’s book reveals the daunting task of coming up to speed on AI, assuming you wish to try it in every aspect of your daily life, as the author did, if only for a year. Fortunately, our contributing experts have several ideas for focusing and making the task more approachable, even if you have the luxury of leisure time afforded by full-time Retirement or even, as in my case, Semi-Retirement.

Stern closes her book with 6 Rules for living in an AI world, starting with “working with AI, not for it. “Use it to move faster, spark ideas, automate the boring parts. But keep your weird, wonderful human judgement in the loop.”

 Retirement is the ultimate unlock for AI

Most respondents on Featured.com mentioned Health, Finances, Travel, Senior Dating and Creative pursuits facilitated by AI. Wayne Lowry, CEO of  Scale By SEO, put it well: “Retirees finally have something working folks don’t: time to actually learn the tool instead of just bolting it onto a busy day. That’s the unlock. AI rewards curiosity and iteration, and retirement is the perfect runway for both.”

Continue Reading…

When mega-IPOs meet index investing

Franklin Templeton ETFs

By Dina Ting, CFA, Franklin Templeton ETFs

(Sponsor Blog)

For decades, public markets were where companies grew up. Investors could watch young firms move from small-capitalization (cap) to mid-cap level and, for the rare few, into the ranks of the largest companies in the world. That journey today happens increasingly in private markets. We’re seeing now that by the time some companies list, they can seem to arrive already fully formed.

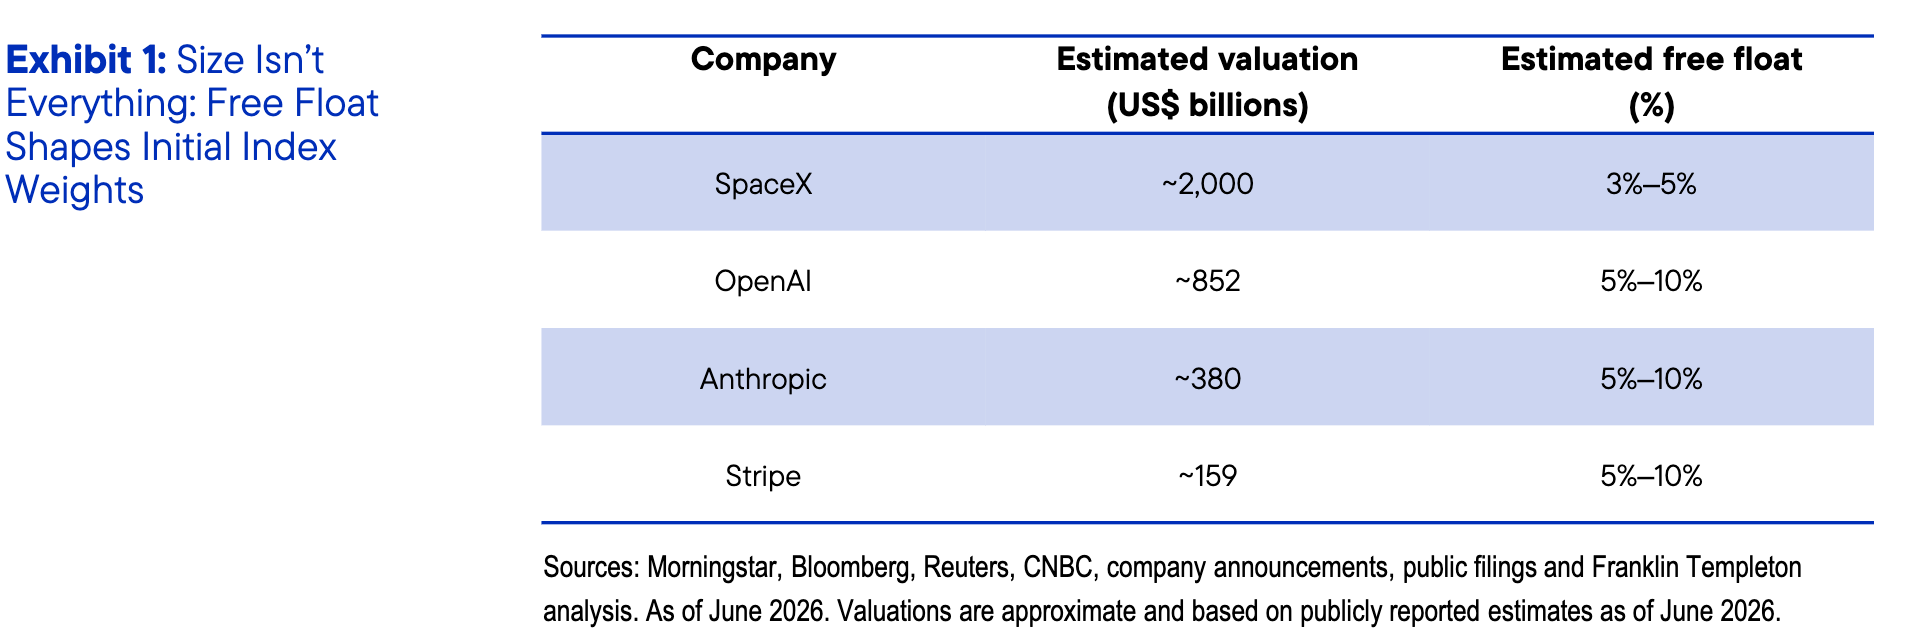
This shift is testing index construction. The impending listings from the likes of SpaceX, OpenAI and Anthropic have prompted index providers to revisit how quickly very large companies making initial public offerings (IPOs) should enter major benchmarks. Some index providers, including FTSE Russell and Nasdaq, have been racing to ensure benchmarks can capture the next generation of large public listings. Others, including S&P Dow Jones Indices, have preferred to keep established guardrails in place, maintaining a more deliberate approach to eligibility and inclusion.

In our view, this diversity of approaches is healthy. Index providers are trying to balance two important goals: reflecting the investable market as it evolves, while maintaining liquidity, stability and transparent rules. There is no single correct answer. A benchmark that moves too slowly may miss important changes in the economy. A benchmark that moves too quickly may expose investors to companies before trading history, float and fundamentals are well established.

An overlooked aspect of benchmark construction is that headline valuations and index weights are not the same thing. Most major equity indexes rely on free-float-adjusted market capitalization, which means they consider the shares actually available for public trading. FTSE Russell’s own preliminary analysis of SpaceX assumed a total market capitalization of US$1.5 trillion but available market capitalization of about US$70 billion, producing estimated weights of only 0.11% in the Russell 1000 Index and 0.08% in the FTSE GEIS All-World Developed Index.1

A company may dominate headlines yet enter a broad index with a relatively modest initial footprint. Over time, lockup restrictions — which typically prevent founders, employees and early investors from selling shares immediately after an IPO — expire, allowing more shares to enter the public market and potentially increasing the company’s index weight.

Another question investors may not have considered is whether these listings automatically make indexes more growth oriented. At first glance, the answer might seem like a no-brainer. Many of these companies operate in areas such as artificial intelligence (AI), aerospace and cloud infrastructure. Yet index construction is often more nuanced than headlines suggest.

FTSE Russell’s treatment illustrates this. Fast-entry IPOs have generally inherited the style characteristics of their assigned subsector until company fundamentals become available. However, the index provider has also acknowledged that relying solely on industry averages could create what it calls “market misrepresentation,” leaving room for alternative treatment in certain cases. For SpaceX, FTSE’s preliminary classification pointed to telecommunications, where the subsector average was 18% growth and 82% value.2

That may surprise investors who instinctively view anything rocket-fueled as growth. But it is a useful reminder: Index investing is rules-based, not headline-based. Style indexes do not simply ask whether a company feels innovative. They evaluate characteristics such as valuation, earnings, growth metrics and industry classification. As more mature private-market companies list, some may challenge traditional style frameworks.

This is where broader portfolio implications emerge. Broad-market index ETFs remain efficient, tactical tools for gaining diversified equity exposure, and country or style ETFs can help investors express more targeted views. But indexes are not static. New companies enter, sector weights shift, float changes, classifications evolve and concentrations emerge. Index exposure is therefore not necessarily something investors should set and forget. Continue Reading…

Picking up Nickels in front of a Steamroller

Image Pixabay

By Michael J. Wiener

Special to Financial Independence Hub

Suppose a casino offered the following bet.  You roll six fair dice.  If anything but all sixes shows up, you get $20.  But if all sixes show up, you lose a million dollars.

There are a number of practical problems with this game.  The casino would demand a million-dollar deposit in advance, and the odds are way too sensitive to imperfections in the dice and to player skill at not throwing sixes.  But this is a thought experiment designed to shed light on real-world financial events.

Initially, few people would play this game, because losing a million dollars is too scary.  But if you watched someone playing, even all day, you’d likely never see a loss.  You’d just see the player collecting $20 every 10 seconds or so, building up to many thousands of dollars.  The fear of missing out (FOMO) would set in for some and tempt them to play.

Over the long haul, the casino expects to pay out $933,120 for every million dollars it wins.  So playing this game is good for the casino but a bad idea for the player.  However, it’s easy to forget about the losses if you only see everyone winning $20 every play.  Games like this are referred to as “picking up nickels in front of a steamroller.”  The $20 payoffs are the nickels, and the million-dollar losses are when you get flattened by the steamroller.

The yen carry trade

So what does this have to do with real life?  There are many “games” in real life that resemble this hypothetical game more than people would like to admit.  When interest rates were much lower in Japan than they were in the U.S., it seemed profitable to borrow yen at a low interest rate, convert it to U.S. dollars, and collect high interest on U.S. dollar deposits.

This sounds quite profitable, so why did I say it only “seemed profitable?”  Well, all was well as long as interest rates and the exchange rate between yen and U.S. dollars were stable.  However, a rise in the value of the yen and higher Japanese interest rates (the steamroller) could more than wipe out any profits from the interest rate spread (the nickels).

Unlike the hypothetical dice game where the potential loss of a million dollars is prominent, it’s less obvious with the yen carry trade.  You might convince yourself that the value of the yen and Japanese interest rates would change slowly enough that you could exit your positions profitably.  However, many others would be trying to unwind their positions at the same time, each one trying to be among the first to get out.

Excessive leverage

Rather than just invest a fraction of your wages in stock markets, you could borrow extra money to invest more.  The stock markets may gyrate, but they keep rising.  If you can just wait out the gyrations, you’ll be sure to eventually make more money (the nickels) than if you didn’t borrow.

The problem is that if you borrow too much, and your creditors see that you’re in danger of becoming insolvent, they may demand their money back or impose high interest rates that eliminate your profits.  A sudden stock market crash (steamroller) could wipe you out before you get a chance to wait out the market decline.  Modest leverage can be reasonable, but it takes some skill to determine how much you can borrow safely.

The great financial crisis

Many Wall Street firms made apparent profits selling insurance against mortgage defaults in the form of exotic financial instruments like credit default swaps (CDSs) and collateralized debt obligations (CDOs).  In this case, the nickels were the insurance premiums they collected, and the steamroller was the wave of mortgage defaults across the U.S. Continue Reading…

Should you Buy a Business instead of Starting one?

Photo by Amy Hirschi on Unsplash

By Devin Partida

Special to Financial Independence Hub

For entrepreneurs, the path to success often begins with the critical decision of whether to buy a business or start one from scratch. The right choice boils down to a few key preferences, such as the level of risk you’re willing to take and your long-term goal of achieving financial independence. Identifying these factors is key to understanding which option is ideal for you.

The Blank Canvas of a New Business

Building a business from the ground up is the ultimate exercise of creative control. You formulate the business model, create the brand identity and hire the team. For opportunistic professionals, this flexibility allows you to jump on market openings the moment you spot them. The level of operational and strategic autonomy you have when starting a business is far greater than when acquiring one.

However, that creative freedom does come with a unique set of risks. In fact, roughly 50% of new businesses fail within their first five years. This staggering statistic underscores the difficulty of building consistent cash flow and securing a customer base while simultaneously proving your business model.

More likely than not, starting a business means navigating years of financial losses before turning a meaningful profit. If you’re the founder, your personal finances are likely to absorb the initial shocks.

Buying a Business means acquiring Immediate Momentum

Taking over an established business is essentially an investment in momentum. You get instant access to existing cash flow, a customer base and a working business model. The costly trial-and-error phase is completely mitigated, and you have the privilege of building off the previous owners’ inertia.

Yet, acquiring an established business often comes at a considerable cost. Acquisitions require significant seller financing or up-front capital, which often entails complex bank loan arrangements. While it is the less risky option, the initial investment will likely be more costly than building a new business on your own terms.

Additionally, buyers risk inheriting unseen liabilities or a toxic workplace culture. When you buy an existing business, you’re simultaneously purchasing someone else’s success and unaddressed problems.

Key Factors to Consider before making a Decision

Making the right decision requires a meticulous navigation of your preferences and resources, including:

  • Financial resources: Startups can allow you to develop your business at a pace that aligns with your financial reality. However, if you have substantial capital to invest, buying a business can generate far quicker returns, directly accelerating your timeline to Financial Independence.
  • Risk tolerance: Starting a new company is statistically risky, requiring a high tolerance for volatility and economic uncertainty. While taking ownership of a working enterprise is more predictable, approaching it without adequate knowledge brings considerable financial dangers.
  • Industry expertise: Building a successful business requires deep market expertise and an aptitude for strategy. Alternatively, taking over a stable operation allows you to rely on existing teams while you learn.
  • Desired level of control: Founders typically want a blank canvas to execute a specific vision. Buyers must be willing to adapt to existing workflows and culture.

Essential Due Diligence Steps before Finalizing an Acquisition

Before officially acquiring a business, entrepreneurs are advised to conduct a thorough evaluation of the company and develop a strong understanding of its financial and operational standing.

Financial Verification

Even if a company’s overall revenue is healthy, it doesn’t showcase the full financial reality of owning it. Before making a purchase, you must review several years of tax returns and bank statements to understand the business’s financial history. Understanding the Seller’s Discretionary Earnings — which is the calculation of an owner’s entire financial benefit — is also nonnegotiable. Continue Reading…