Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Why Secular Trends beat Market Indicators

Forget about market indicators–picking up on secular trends is a much better way to spot top stocks
TSInetwork.ca

Investors sometimes ask how I learned about investing and the stock market. The answer is that I started early, read a lot, and learned how to write so that readers understand what I’m saying.

I got started as a teenager, with a part-time job for an investment writer. My job was to gather and organize information on public companies and the economy. This called for a lot of reading, but I was always an avid reader.

Learning how to write easy-to-read material is also a plus. After all, you have to understand information to be able to explain it to others.

During my first full-time decade in the investing business, I learned that many factors influence market trends. Naturally, I tried to learn about or create market indicators that could tell me how these factors could help my investing. Gradually it dawned on me that most market indicators turn out to reflect the fact that random events tend to occur in bunches.

Some of these bunches are big enough and last long enough that you can mistake them for sure signs that the market is headed in a particular direction.

The four-year U.S. Presidential Election indicator is different. It’s the most valuable market indicator I know of because it takes advantage of recurring cycles in the U.S. Presidential Election cycle. It’s still far from perfect. However, you might say that every few years, it gives investors a helpful nudge in the right direction.

The four-year rule is of little interest to many investors, particularly those who are new to the game. They lack the patience for it. Over the years, I’ve talked to many young investors who seem more interested in short-term trading than in our long-term Successful Investor approach.

From their point of view, they don’t need to obsess about risk because they don’t have enough investment capital to worry about losses. They say they’ll switch to our approach when they’ve made a windfall in something that works out as they hoped. When they have more money to risk, they’ll be more careful with it.

The trouble is that since they disregard risk, they may never acquire the gains they hope for. All too often, they get sucked into one bad investment after another. These include short-term trading (particularly in so-called meme stocks), dabbling in stock options or IPOs or SPACs or cryptocurrencies or NFTs. Dabblers fail to see that the big gains in these opportunities go to those who sell them to the investing public.

Secular trends beat market indicators

In the 1980s, I lost interest in market indicators and began to focus on secular trends. These are economic trends that last longer (sometimes much longer) than the typical prosperity/recession cycle.

Back then, for instance, goldbugs were sure that federal deficit spending was responsible for the high inflation of the period. It seemed to me that they were paying too little attention to the economic changes going on, particularly the impact of the baby boomers’ entry into the workforce. When employers hired boomers, it raised costs, since these newcomers needed training (particularly women who were going to work in higher numbers than previously). Continue Reading…

Can Millennials become Financially Independent?

Image Pixabay/iStock

By Billy and Akaisha Kaderli

Special to Financial Independence Hub

Millennials, those born roughly between 1980 and the year 2000, face a different future than Baby Boomers did at their same age. In terms of Wealth Building and saving for Retirement their challenges are wage stagnation, unemployment, underemployment and a seeming sense of entitlement. Because they came of age during the Great Recession, their faith in brokerage firms, Wall Street and global banks has been bruised.

Being optimists, we believe the financial future of this generation can still be bright, but with loads of student debt and lack of investment understanding they need to get started learning about finances and money management now.

Time is on your side and is your greatest asset

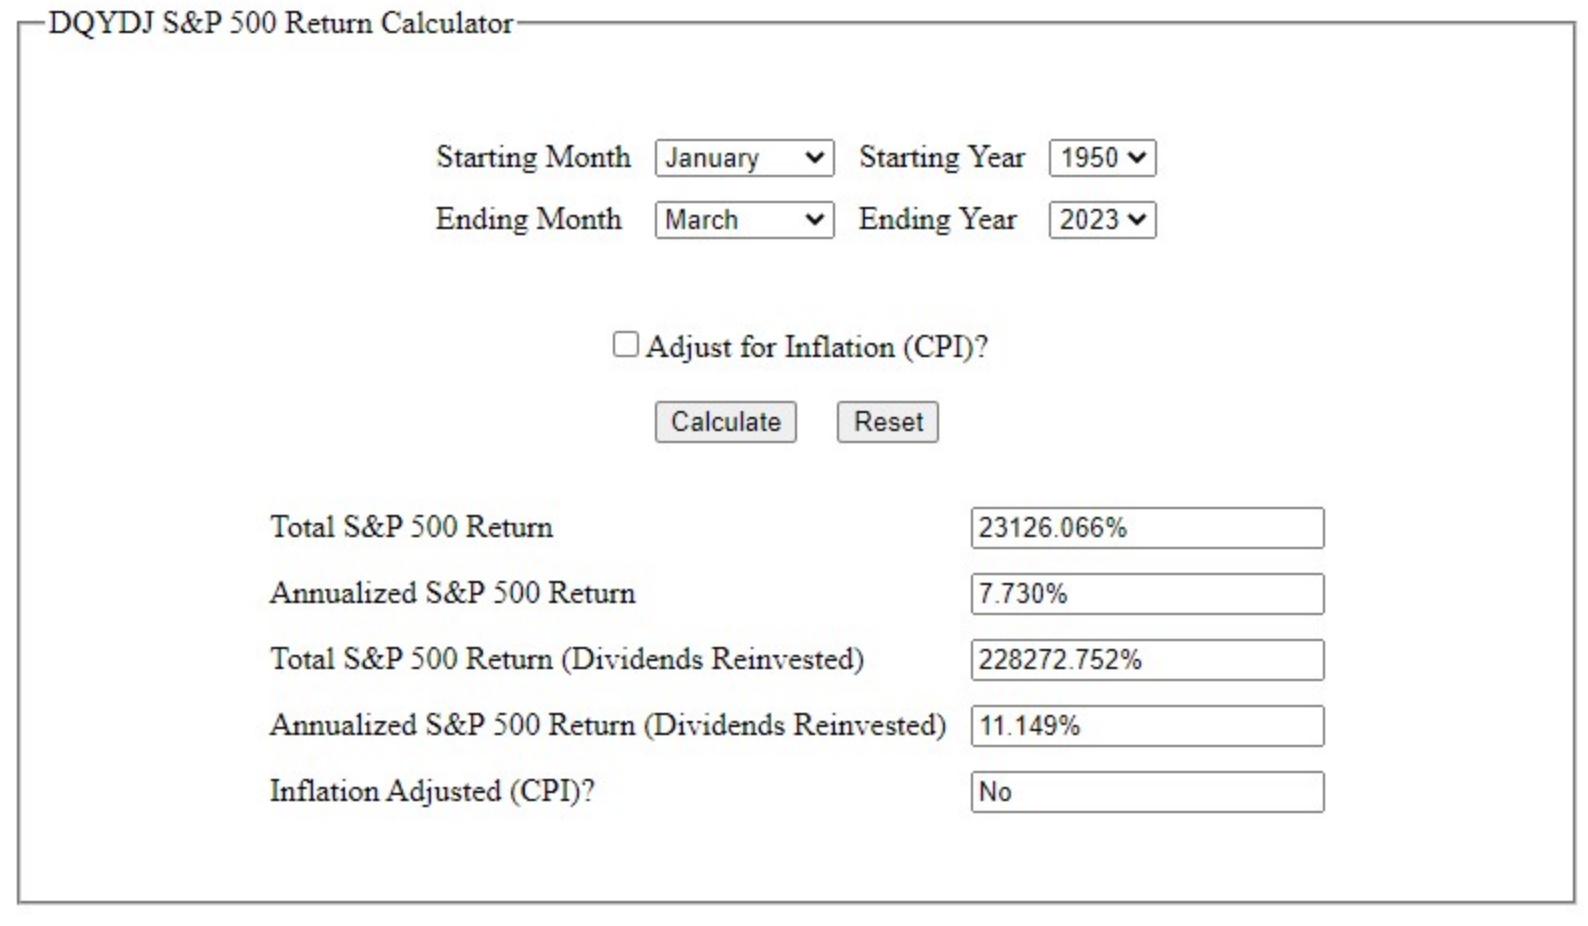
One thing Millennials have today that Boomers don’t is great stretches of time before Retirement. It is their greatest resource and this fact needs to be made clear to them. Time cannot be replaced, and if you are a Millennial, then knowing about the power of compounding will change your financial life. $10,000 – the cost of a used car – invested today in the S&P 500 Index and based on market historical returns from 1950 to March 2023 could grow to US$1,000,000 or more throughout your career, thereby building a solid foundation for your retirement needs. This return is without adding another dollar to your investment.

S&P Market Return Chart

If you do nothing else for your retirement, scrape and scrap to make this investment into SPY (S&P 500 Index ETF) or VTI (Vanguard Total Stock Market ETF) and you will be handsomely rewarded, since you have this time on your side.

Just get Started

A new investor with limited funds can utilize an online, no-frills brokerage account and — depending on which brokerage you pick —  you can open an account with less than $1,000. Not every house requires initial investments of more than $2,500, and as of this writing, Fidelity is offering a no minimum for opening an account. Continue Reading…

BMO ETFs’ third annual ETF Investor Day aimed at DIY investors

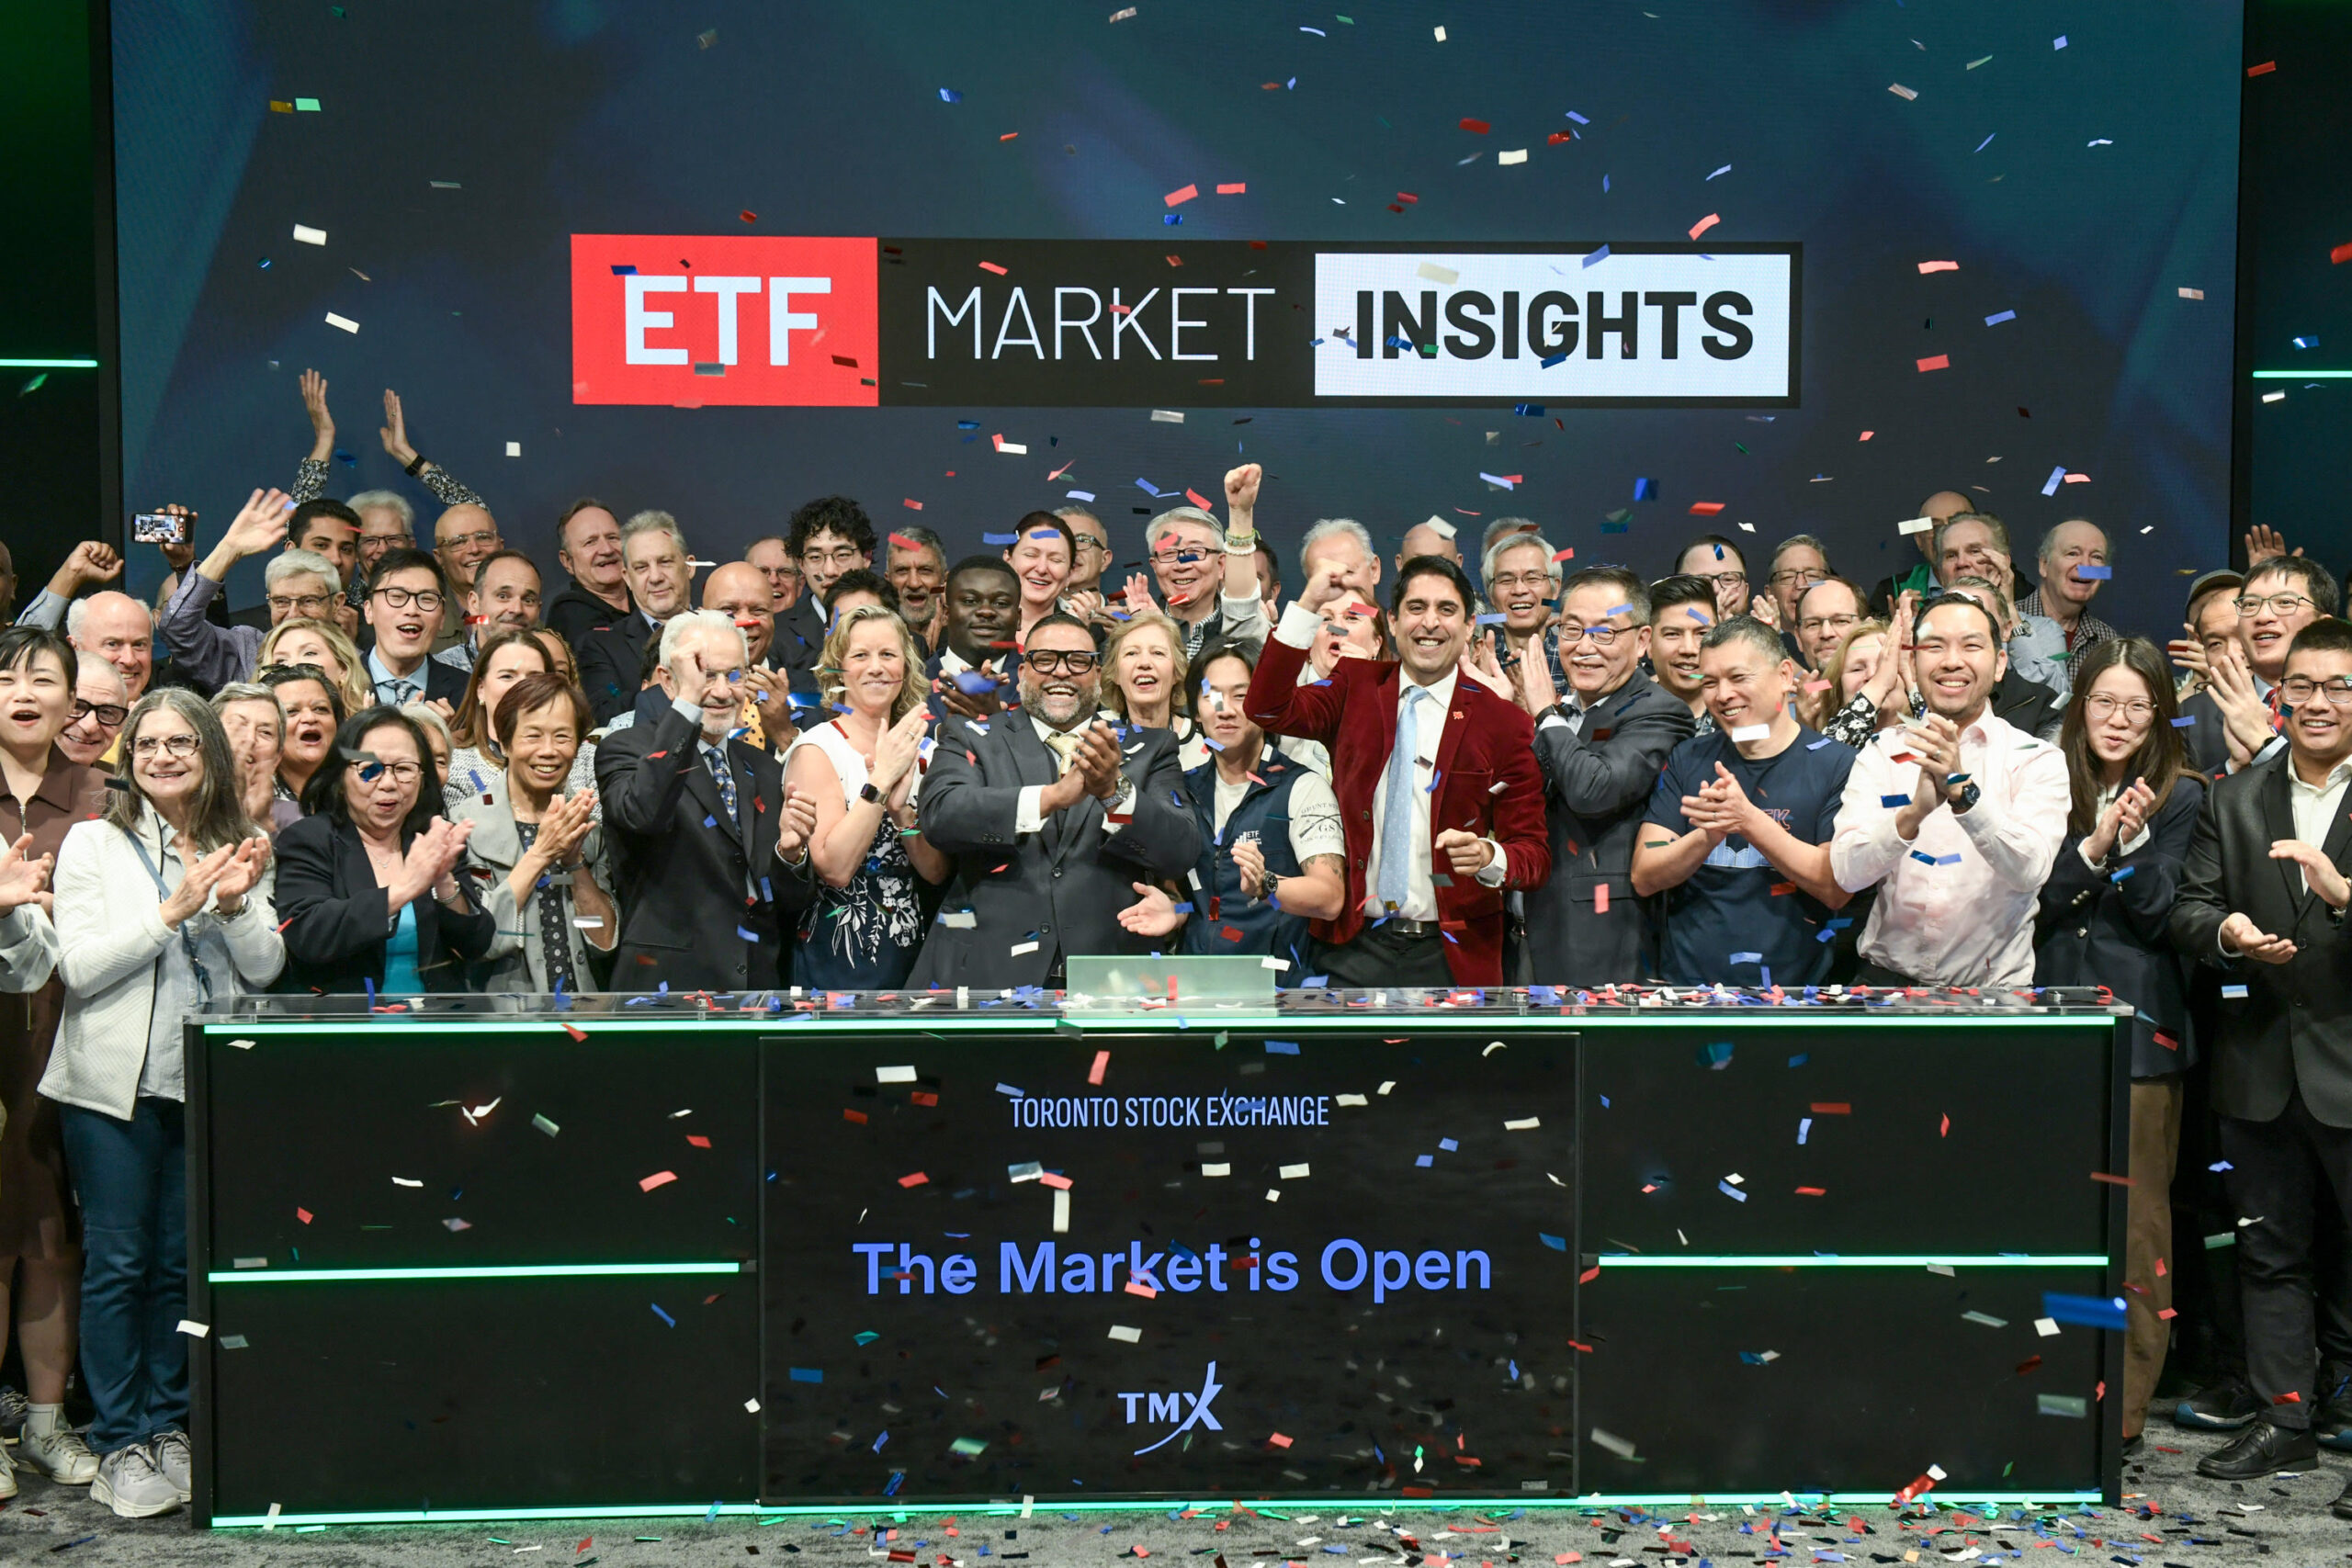
On Tuesday, BMO ETFs conducted its third annual ETF Investor day. Conducted at the Toronto Stock Exchange, Do-it-yourself investors and finfluencers [Financial Influencers] were on hand for the ceremonial opening of the exchange, shown in the photo on the left. The Investor Day will also be held in Montreal on June 18: Details here

This marks BMO’s 17th year as a Canadian ETF provider, with $165 billion in Assets under management and 66 tickers  with a 10-year track record.

The first presentation was an economic and investing overview from Fred Demers, Director of Multi Asset Strategy at BMO Global Asset Management. He teased whether the R word refers to a Recession or Resilience when it comes to forecasting the economy. While the world is likely to remain messy, “the good news is the world always carries on.”

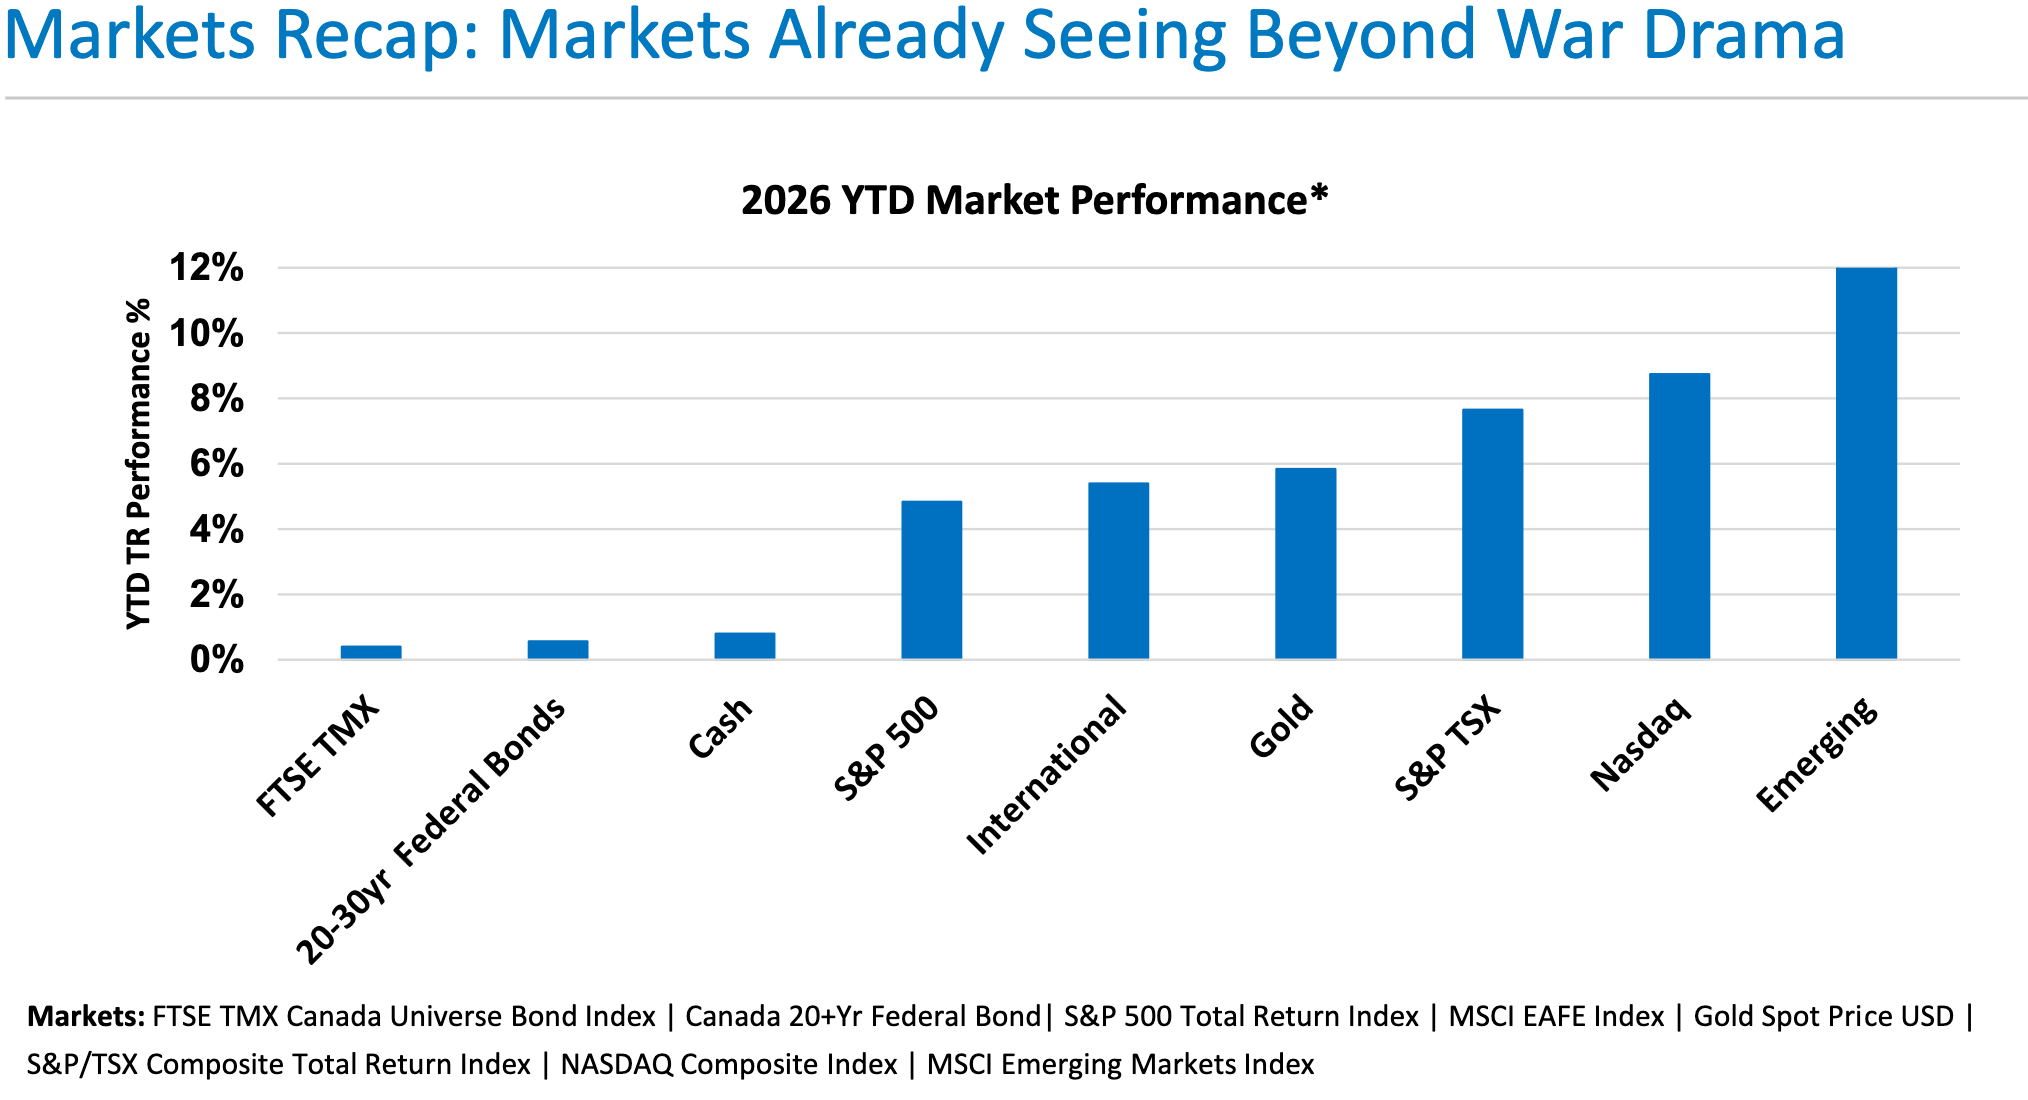
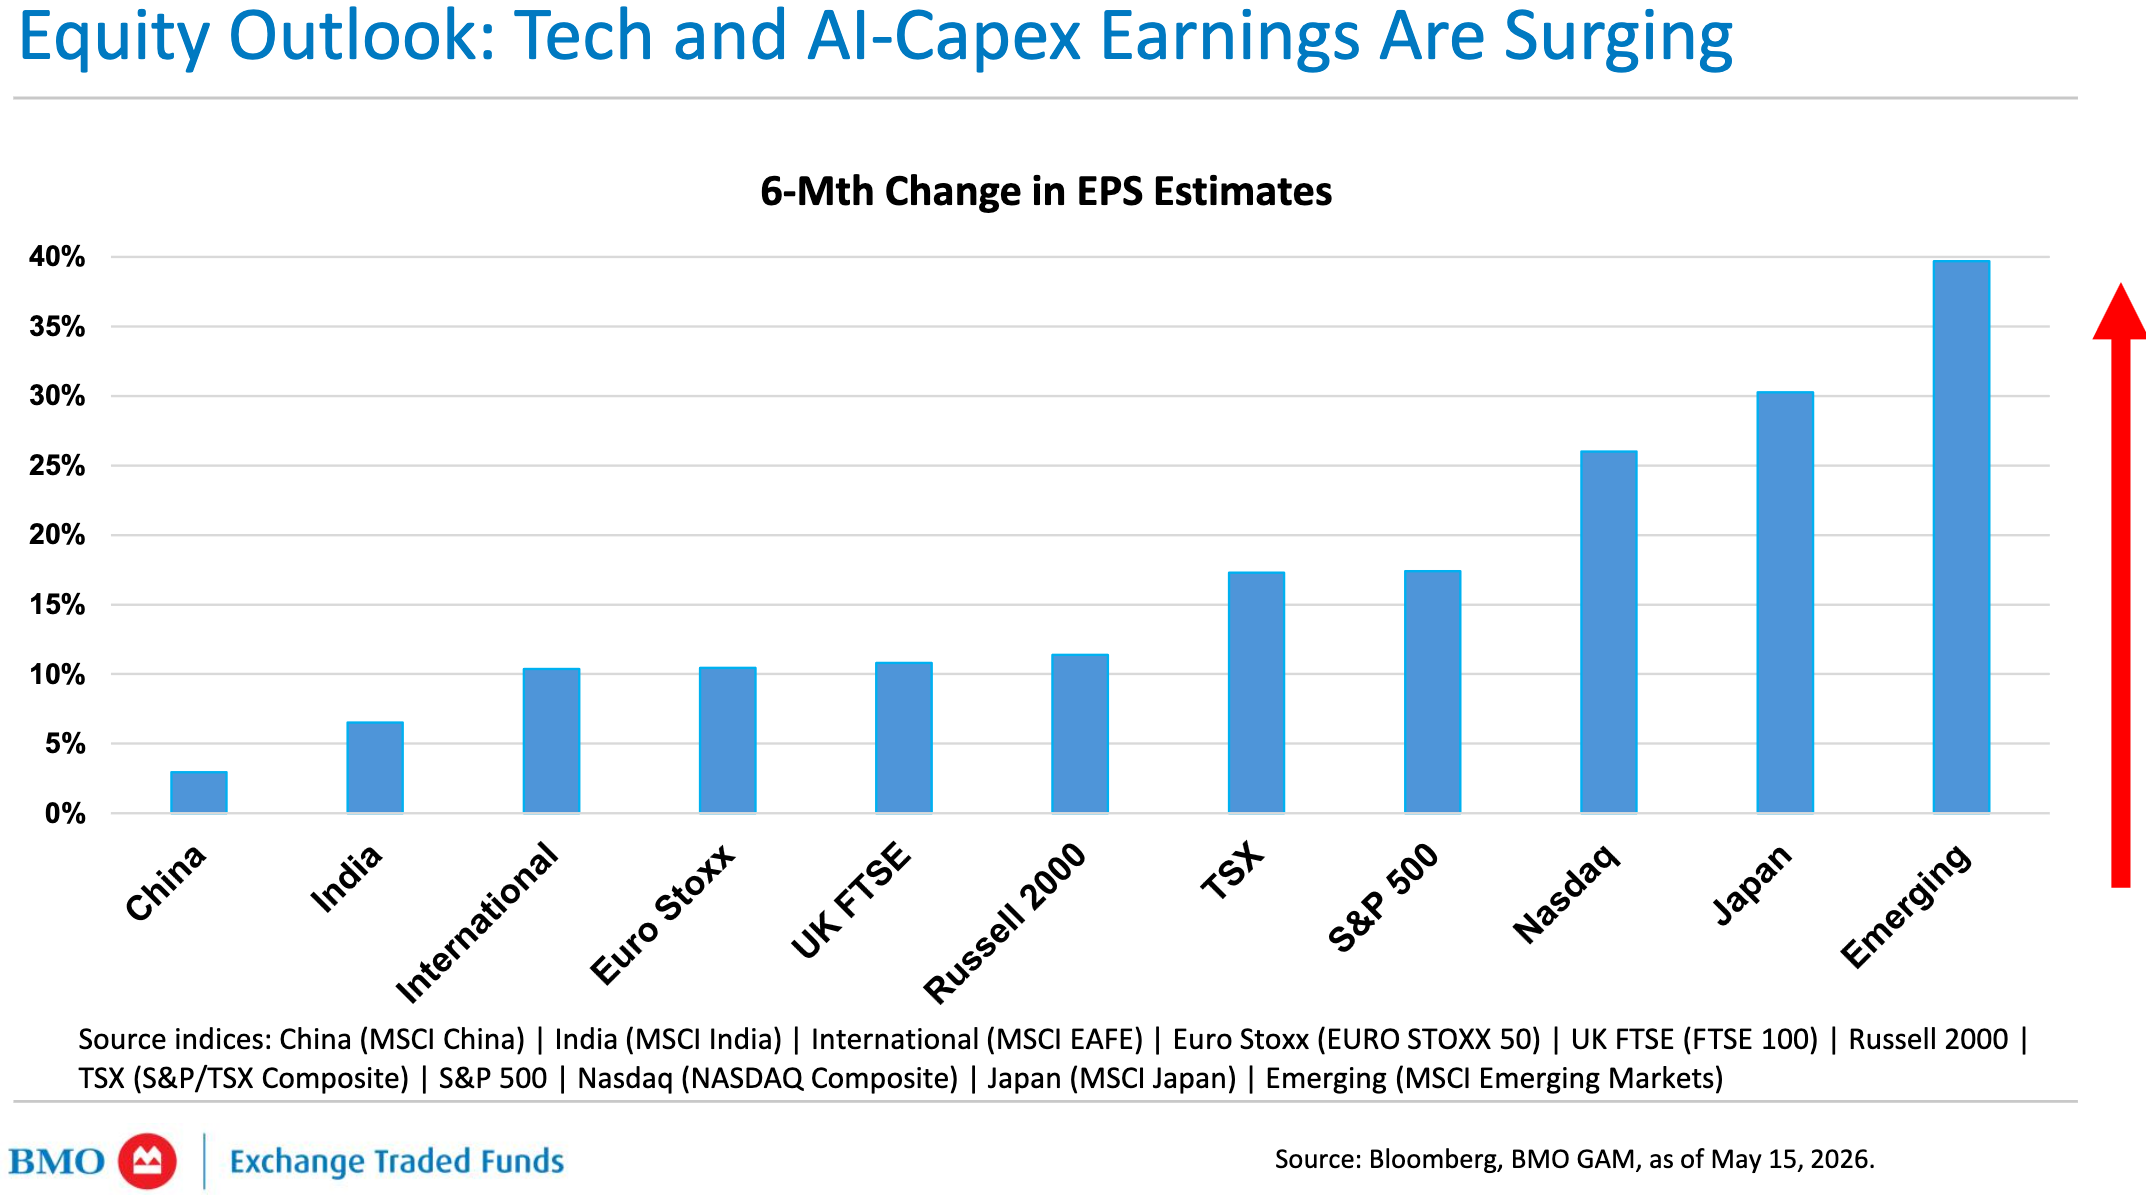
Demers is particularly bullish about the long-term prospects of the U.S. economy and the Tech giants that power innovation and in particular the A.I. Capex boom and AI infrastructure buildout. Stock markets are already seeing beyond the drama of the war in Iran, he said, led by a 12% gain YTD 2026 in Emerging Markets, 9% or so for the Nasdaq and almost 8% for the TSX, as shown in the chart below taken from the presentation.

Fixed income is not doing much of anything, which is to be expected when the economy is doing well but would show its value if a Recession got under way accompanied by Job Loss, which he said is not yet where we are. Gold has returned almost 6%, disappointing given the Middle East conflict but “still doing its thing short-term.” Its role is not to diversify equities but to diversify fixed Income.

Obviously the oil shock hurts and is a clear negative for Growth but it remains to be seen how severe it will be. Demers said Trump’s Tariffs amount to basically the equivalent of a 3% GST (a reference to Canada’s Goods & Services Tax).

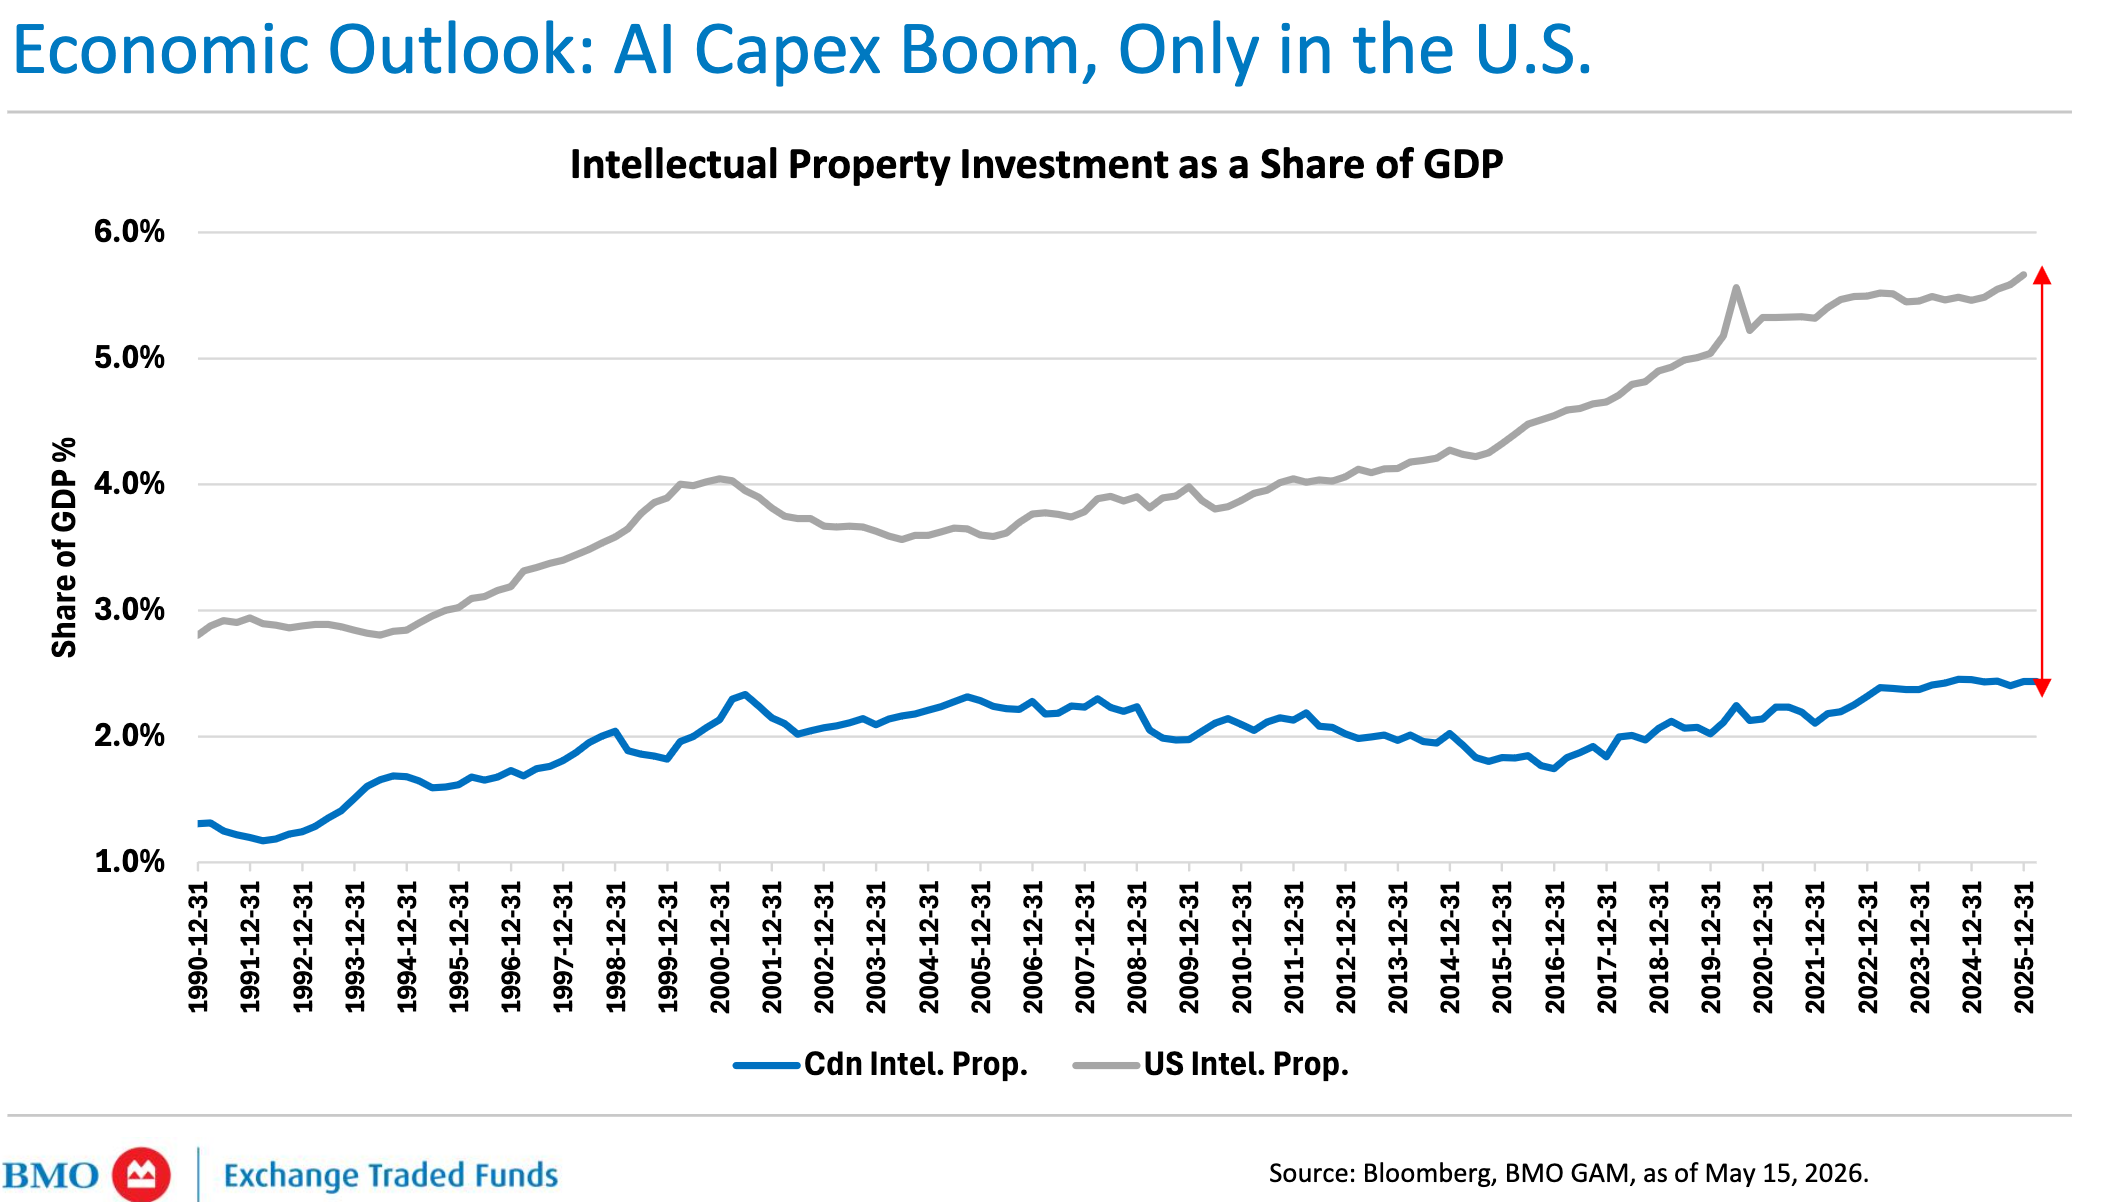
He said it’s good to diversify globally but investors worried about the impact of Trump should “be careful about exiting the U.S. entirely.” The AI race is primarily between the US and China and AI Capex will keep roaring for years if not for decades. We are “not even half way through the capex cycle.” AI Capex spending has reached a “phenomenal” US $350 billion, and is on track to pass US$750 billion in 2026; the hyperscalers are planning between $1.1 and $1.2 trillion.

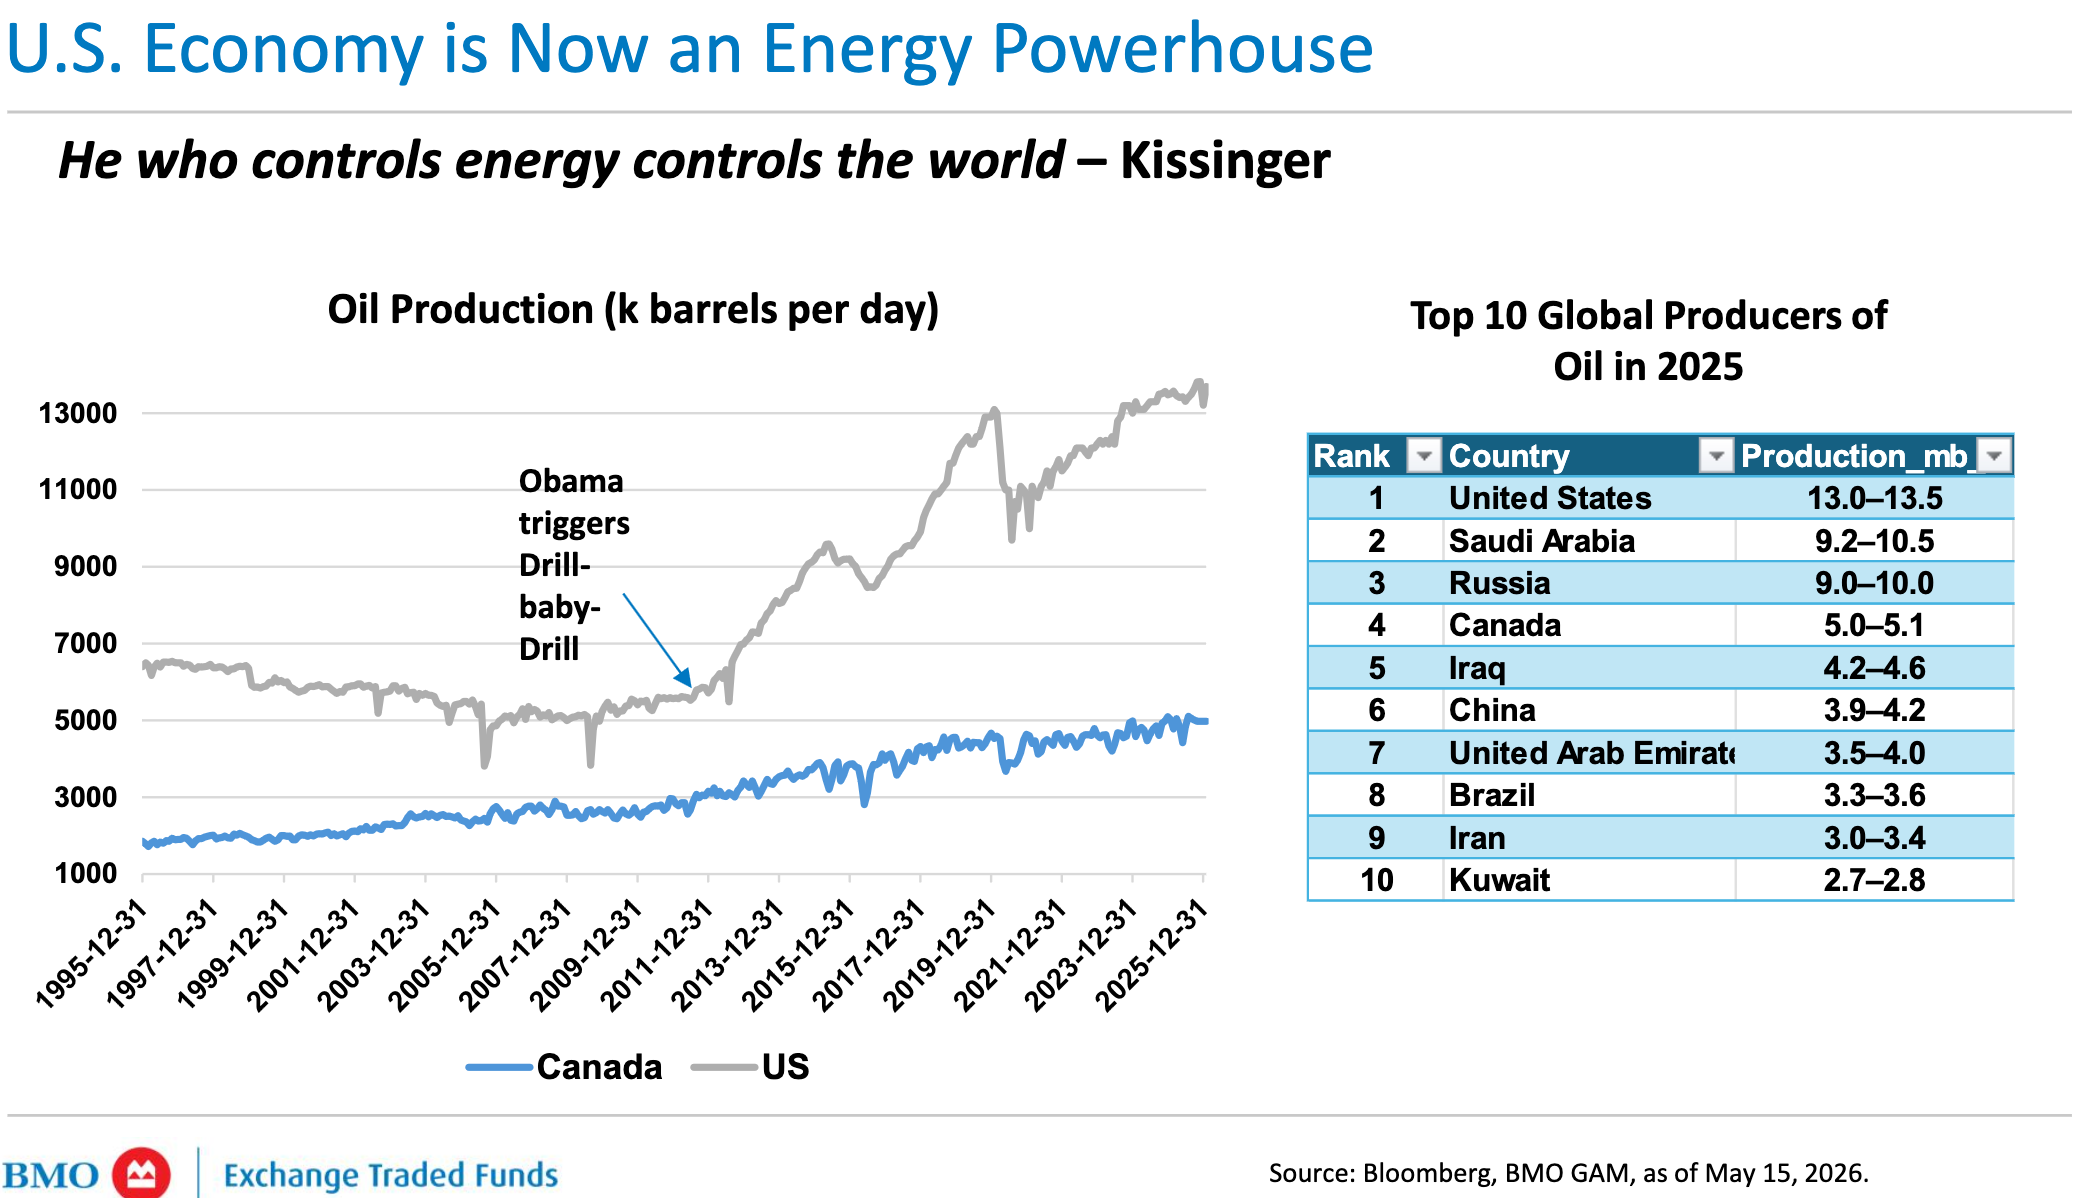
By contrast, AI Capex in Canada is not even $50 billion. Just ten giant American companies generate a third of the country’s economic activity. These are the big-tech titans but the U.S. economy has also become an Energy Powerhouse: the biggest oil producer in the world and net exporter of energy. Next is Saudi Arabia and Russia, with Canada in fourth and Iran is ninth. (See chart shown in the Sector section below)

Sector ETFs

The second talk was by Simona Mocuta, managing director and chief economist for State Street Investment Management (shown on the left). BMO recently launched a suite of BMO SPDR Select Sector Index ETFs with State Street and sector investing was the focus of her talk.  She started by saying she agreed with everything Fred said, drawing laughs when she said “it’s nice to see a Canadian that still likes the United States.”

BMO’s vice president of Online Distribution ETFs Zayla Saunders asked Mocuta about a SPDR energy ETF [XLE/TSX] to capitalize on surging oil and gas prices sparked by the Iran conflict. “Go for it,” Mocuta says, “Talk AI all you want but you need Energy to make it happen.” With the Iran war, the U.S. is telling Europe to buy from the U.S., which makes Energy as “compelling buy-and-hold.” The chart below is from Demers’ presentation:

Among other sectors, Technology was by far the best performer in April, Mocuta said, but there have been over the last 12 months strong inflows into Industrials, Materials and Energy.” However, investors should also consider less-loved sectors like Healthcare.

In response to an audience question about the U.S. financial sector, Mocuta said that in the medium term banks are being deregulated, which is a huge positive after the regulatory burdens imposed after the Great Financial Crisis. Continue Reading…

Dalbar’s Measure of Retail Investor Underperformance

DALBAR/LinkedIn

By Michael J. Wiener

Special to Financial Independence Hub

Lately, I’ve heard a few references to Dalbar’s measure of how much retail investors underperform the investments they hold due to poor behaviour.  I suspect that if the people making these references understood how Dalbar calculates this measure, they’d be embarrassed at having mentioned it.  There can be legitimate academic debate about the best way to measure investor underperformance, but Dalbar’s simple method is just nonsense.

A simple example to illustrate the problem

Ann has invested in ABC fund for the past 5 years.  Her initial investment was $10,000.  Over the first 4 years, she left her investment alone and it grew 50% to $15,000.  Ann then got an inheritance of $20,000, which she put into ABC fund to give her a total of $35,000.  In the final year, ABC went up 6%.  Ann now has $37,100.

By any reasonable method of analyzing Ann’s investment behaviour, she exactly matched the performance of her fund.  She was always fully invested with the money she had available.  She never held back any funds waiting for a better entry point, and she never withdrew any money anticipating a market decline.

But let’s look at what happens when we apply Dalbar’s calculation method.  Over the 5 years, ABC fund produced a 50% total return over the first 4 years, and a 6% return in the last year.  The total return for the 5 years is then

(1 + .50) * (1 + .06) – 1 = 59%.

The compound average annual return for ABC fund is

(1 + .59) ^ (1/5) – 1 = 9.72%.

Ann invested a total of $30,000 over the 5 years.  Her total return is

$7100 / $30,000 = 23.67%

Her compound average annual return is

(1 + .2367) ^ (1/5) – 1 = 4.34%.

Ann’s annual underperformance is then

9.72% – 4.34% = 5.38%.

Apparently, Ann is a terrible investor.  According to Dalbar, Ann’s poor behaviour was in receiving her inheritance late in the 5-year period.  She should have invested the entire $30,000 5 years ago.  This is nonsense, of course, but that’s how Dalbar’s calculations work.

Telling advisors what they want to hear

To my knowledge, Dalbar doesn’t apply their methods to a single investor in this way.  They look at investors collectively across a set of funds.  However, the same problem illustrated above exists.  During any period of net inflows, investors are blamed for the returns these inflows missed at the beginning of the measurement period.  Investors are blamed for “poor timing” because they didn’t invest the money earlier.  The fact that most of them were unable to invest before they had earned the money is not considered a valid excuse. Continue Reading…

Retired Money: FIRE Bloggers starting Early Retirement in their 50s and even 40s

Deposit Photos

My latest MoneySense Retired Money column looks at a handful of FIRE bloggers who should be familiar to readers of this site, Findependence Hub: notably Mark Seed of myownadvisor and Bob Lai of Tawcan.

As you can see by clicking on the column headline, How are FIRE adherents making out?, Seed recently announced he has reached his Financial Independence in his early 50s. Bob Lai, meanwhile, is still working in his 40s but blogged on how he hopes to reach Findependence before 2030.

The MoneySense column also updates the status of veteran personal finance columnist Rob Carrick, who ended full-time employment at the Globe & Mail last year, the subject of an earlier Retired Money column.  And we mention a good blog by The Retirement Manifesto’s Fritz Gilbert about the 12 Good Years between age 60 and 72. As I ironically close the column with, it seems I have just used up my own 12 good years!

The real focus of the MoneySense column is however Mark Seed, just as it was Carrick last summer. In both cases, we exchanged views in Zoom or GoogleMeets over the course of an hour or so.

By now, it’s hardly necessary to remind readers that the FIRE acronym stands for Financial Independence Retire Early, as the image above  illustrates.

Note that our FIRE subjects in the column span four decades: Lai his 40s, Seed his 50s, Carrick his 60s and I am in my 70s, evidently still running this website and writing for MoneySense, a former employer.

The end of Salaried Employment does not mean no more Working

The observant reader will note that none of the bloggers mentioned here have actually begun the traditional “Full-Stop Retirement.” When FIRE proponents describe Early Retirement, they usually mean leaving the comfort of full-time salaried employment and all that it entails: commuting, bosses, endless meetings, tax deducted at source, annual performance reviews and so on. Continue Reading…