Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Rebalancing in Down Markets: Scary, but Important

Special to the Financial Independence Hub

If there is a universal investment ideal, it is this: Every investor wants to buy low and sell high. Fortunately, there is a disciplined process for doing just that. Plus, it can help you stay on track toward your personal goals, even during down markets. The process is called rebalancing. 

When you create your new portfolio, it’s best if you do so according to a personalized plan that prescribes how much weight you want to give to each asset class. So much to stocks, so much to bonds … and so on. Assigning these weights is called asset allocation.

However, as markets shift around, your investments stray from their original allocations, until they’re no longer invested according to plan. When this happens, you end up taking on higher or lower market risks and expected rewards than intended.

Rebalancing shifts your assets back to their intended allocations.

A Bear Market rebalancing illustration

Imagine you have planned for a portfolio mix of 50% stocks and 50% bonds. Then a bear market comes along, in which stock prices tend to decrease and bond prices increase. Your mix may no longer be 50/50. To rebalance, you sell some of the now-overweight bonds, and use the proceeds to buy low-priced stocks. In doing so, you are not only keeping your portfolio on track toward your goals, you’re selling high (overweight holdings) and buying low (underweight holdings), all according to plan.

Striking a rebalancing balance

Rebalancing is an important portfolio management tool. But like any power tool, it should be used with care and understanding.

It’s scary to do in real time

Everyone understands the logic of buying low and selling high. But when it’s time to rebalance, your emotions make it easier said than done. When markets are down, you must sell some of your assets that have been doing okay and buy the unpopular ones. In retrospect, history has shown us this is a sensible thing to do. But at the time, it can take a brave leap of faith that our capital markets will ultimately recover and continue to grow (as they always have before). Continue Reading…

Tips for transitioning your employees to work from home

AdobeStock

By Shannon Hicks

For the Financial Independence Hub

For businesses to thrive, they must give importance to their employees. They are an essential part of any company because their competence is what drives growth.

As an employer, there are a number of practices that you can adopt to make your employees more efficient at their tasks, especially in these times when a worldwide health crisis is at hand and most employees are at home.

Working from home poses a lot of obstacles to employees. Hence, as an employer, it is important to motivate them to concentrate on their respective tasks. This way, even though the whole world and economies have been disrupted, your business is still able to generate high-quality outputs.

Here are some tips to transition your employees to working from home:

1.) Help them set up their workspace at home

The first problem that employees face when they start working from home is whether or not they have the hardware necessary to carry out their tasks. So, as an employer, it should be your first concern as well.

Thus, when transitioning your employees to work from home, ask them if they have the necessary equipment or hardware, such as a computer, for them to be able to perform their tasks. If they lack the essential implements, then, allow them to borrow those from the office. Let them take home the units they use at work; after all, no one would be using those. Of course, they need to return the devices once they resume working at the office.

Furthermore, allow your employees to download or install applications that your company will be using to communicate and manage tasks. Make it clear which tools and workforce management system will be utilized so they can have them installed on their respective devices as soon as possible.

For example, Slack can be used for communication purposes, while Zoom can be used for teleconferencing. Making this clear early on will allow your employees to familiarize themselves with the tools, so they would be efficient in using them as soon as they need to.

AdobeStock

2.) Be flexible in your working policies

Each employee will have a different setup at home. While some are living alone in their own apartments, some are with their families and may even have kids at home. Thus, it is understandable that when employees start working from home, they will have different schedules as to when they are best able to work.

So, when making policies for employees working from home, be understanding of their circumstances. For example, you may not need to set specific working hours; rather, keep them focused on finishing tasks before or on the deadline.

For better communication, you can schedule a weekly or bi-weekly teleconference, or you can also take advantage of a specific time when everyone is available. Thus, communication is always open and everyone can regularly give updates on their tasks.

3.) Keep communication lines open

Weekly teleconference or virtual meetings should not be the only time that managers and employees are able to talk and give updates. Continue Reading…

Should Investors have FOMO?

By Cory Clark

Special to the Financial Independence Hub

Nobody knows if we have reached the turning point in the year’s pandemic-induced market meltdown. The markets are not quite as scary as they were at the beginning of March when some markets lost nearly 20% of their value in a single day.

Some recoveries are rather swift, while others take a little more time, but there is one way to know when the market has reached its bottom … just kidding …. there is no way of knowing, and that’s exactly why the average investor should not be bailing out of their positions when storm seas get rough.

If you decide that you can’t stand the risk of loss and fear that goes along with it, the only way to sell and successfully mitigate losses is to make two correctly timed decisions. Not only must you sell at the right time, but you must also re-enter at the right time. DALBAR has been studying investor behavior since 1994, and it is painfully obvious from history that investors are not going 2-0 and timing it right on both ends.

The common rationalization for selling out at the worst time is that if you are not losing money, you must be better off, right? This an example of a dangerous investor behavior known as risk aversion, and from an economic standpoint it is an invisible hole in the bottom of your bucket. Investors love to make money, but they hate to lose that same amount of money even more. So being out of the market and avoiding a loss provides a measure of comfort, but being out of the market and losing out on a similarly sized gain tends to go unnoticed. But when looking at your investor statement, or when projecting future retirement income, money you lose and money you should have (but didn’t) gain will all have the same net effect on that bottom line.

Don’t get out if you don’t know when to get back in

The situation of today’s average investor perfectly illustrates in live action what DALBAR’s Quantitative Analysis of Investor Behavior (QAIB) has been teaching investors and advisors for years; don’t get out if you don’t know when to get back in.

Imagine an investor who reached their breaking point sometime in March, and sold their equity position with the intention of buying back in when the coast is clear. Not long after, the markets started to shoot back up aggressively, much earlier than anticipated. Now doesn’t that put this investor in a precarious situation? Who wants to be “that guy” (or gal) who buys back into the market after the biggest daily gain ever? If the recovery ends up being a false start, this investor could lose a significant chunk of his portfolio … AGAIN. So perhaps this investor doesn’t fall for a potential false bottom and continues to wait …. and wait … and wait … until the recovery is certain. Unfortunately, by the time the recovery is certain, it’s over and this investor has missed the boat. Continue Reading…

How Multi-Asset Portfolio Managers are adjusting their asset allocation during extreme volatility

Franklin Templeton multi-asset portfolio manager Ian Riach


The following Q&A is between Hub CFO Jonathan Chevreau and Multi-Asset Portfolio Managers Ian Riach & Michael Greenberg of Franklin Templeton. (Franklin Templeton is a Hub sponsor.)

Jon Chevreau: The last few months have seen unprecedented volatility in the markets. How have your portfolios been impacted in this recent drawdown?

Mike Greenberg: Given the speed and severity of this downturn, our Portfolios from an absolute return perspective have been challenged like many others on the street. However, we do believe the current environment and positioning should allow strong returns going forward. We see a scenario similar to 2008 where balanced products suffered, but then rebounded very strongly. We can’t be sure of timing but feel same play book is a realistic expectation.

However, on a relative returns basis, our portfolios have performed better than some of our competitors. This is due to the more defensive positioning we took before the bear market started, where we reduced risk based on what we believed were stretched valuations in a late cycle. We had also reduced credit risk earlier, as we felt risk/reward was not favorable given the spreads. Especially in Canada given the threat of potential illiquidity with some assets. Despite not anticipating the crises, having a lot less credit exposure compared to some peers, worked out very well for us. Within our equity fund selection, we had previously moved more into our core funds, which have held up well in the downturn given their quality bias. We also increased allocations to some of the lower-beta funds/ETFs funded from more cyclical holdings that had more value and small cap bias.

Jon: What effect has this volatility had on your fixed-income allocations?

Mike Greenberg

Mike: There are not many places to hide even in fixed income, as credit and spread products really sold off. Still, being more conservative and selective in our fixed income exposures prior to the downturn has helped us weather the storm quite well. We also feel we are well set up for some good opportunities in fixed income going forward.

We’ve been adding incrementally to credit funded from governments and we see better opportunities in credit but there is still some risk so we are not going ‘all in’ quite yet. We anticipate corporate earnings will crater and bankruptcies rise in the upcoming months. The longer the virus containment goes on, the larger the risk to the global economy, so we are being selective about picking our spots. Given the uncertainty we favour more active exposures in fixed income; even the fixed-income ETFs we hold in our portfolios are more active, and for us, that is important going forward as we are looking to capture some of the opportunities.

We are now a bit more positive on credit, especially in investment grade credit in the US given direct support from the Federal Reserve. Canada has seen some quantitative easing measures, but not direct corporate bond purchases like the US, so we still view this as a very illiquid market in Canada. So, we are bit more hesitant in that space, but we are also aware that there is a tendency to throw the baby out with bathwater, which again highlights why we like active credit management in this space.

Jon: Where do you think the Loonie is going?

Ian: I think the Loonie will continue to remain relatively weak compared to other currencies due to a number of challenges. The Canadian Dollar has been influenced by the economic backdrop of course but also energy prices. The influx of supply from Saudi Arabia and Russia combined with the forecasted decrease in demand due to Covid-19’s effect on the global economy has sent energy prices into a free fall. Canada is feeling it even worse than others.  Just a few weeks ago when West Texas Intermediate oil was close to $50/bbls, our price benchmark Western Crude Select (WCS) was around $35 but recently we’ve seen it trade less than $5.00/barrel which is absolutely devastating for parts of our economy and our dollar.

Given the Loonie’s relationship to the oil price it is no surprise we have seen it drop and we feel it could stay weaker until we see some uplift in oil prices. Right now, we believe that current prices are not sustainable for anyone, Saudi Arabia included. They can likely produce a barrel of oil for somewhere around $10 – $11 per barrel, but really, they require oil prices to be around $60-$70 a barrel to balance their budget. Recently we have seen an OPEC deal that will attempt to curb supply to bring better balance to the market, but the demand hit will be large.

That is why we would not be surprised if we see a recovery in energy prices soon, and that will help the Canadian dollar somewhat, but the general economic backdrop of Canada will still keep our currency at low levels compared to the US dollar even in the recovery.

Hub CFO Jon Chevreau

Jon: How will this downturn impact Canada’s commercial and residential real estate markets?

Ian: It will have an effect on both markets. On the commercial side, probably the hardest hit will be hospitality related properties like hotels, restaurants, coffee shops etc.  Small office complexes with various service industries will also feel the lack of rent coming in and may face re-leasing problems if certain businesses can’t reopen or chose more remote working arrangements. Industrial properties will probably rebound quicker as the economy starts growing again as physical plants and storage are required for manufacturing and there could be pent up demand building right now.

On the residential side the effects may be shorter term in nature: people can’t decide to live “virtually,” they need a physical home. In the short-term buyers may be hesitant to make a move from rent-to-buy or “move up” due to uncertain employment situation. Sellers, unless they really need to move, say because of work, may be reluctant to accept offers that they feel are below “true value.”

Prices may dip in the short term as forced sellers may have to accept price concessions at least until there is more economic certainty.  It also depends on what area of the country we talk about.  Major urban centers like Toronto where supply had been limited before the downturn will likely see activity rebound more quickly than in areas like Calgary where the double whammy of the virus and the collapse of oil prices will affect that city more acutely.

How do you see Covid-19 affecting the economy and how would a recovery play out?

Ian: Obviously Covid-19 has already had a big impact on the economy and there remains many unknowns before we start to see a lasting recovery. We don’t know what letter in the alphabet the economic recovery will look like: a “V” or a “U” or “L” as the recovery is so dependent on the virus and the news on that front is still evolving day-to-day.

If we had to pick one now, I’d say we are looking at a “U”: the resolution of the virus will take longer and its impact lasts longer than expected, thus the rebound starts but with lower force and is more drawn out. In fact, it will probably look more like a “W” and we mean a true double “U” not a double “V” like we use conventionally when we write or type. Meaning we get a low and slow recovery, that will likely include fall backs.  So it will likely look more like a sine wave than a letter.

Given this view we have been reluctant to aggressively add risk to the portfolio, although we have been adding on a measured basis as the outlook for equity returns over bond returns are much more attractive 12-18 months out. One positive note has been the significant policy responses from governments, which should help soften the blow.

What do you think about all this money printing by the Fed and other central banks?

Mike: The amount of money injected into both economies has been as unprecedented as the market shock itself. Continue Reading…

Gold’s role in the current investment climate

By Nick Barisheff

Special to the Financial Independence Hub

Gold has been misunderstood and ignored by retail investors, financial advisors and pension managers as a critical portfolio asset during normal market conditions.  However, during periods of market stress, such as we are experiencing now, gold becomes a safe haven asset that will mitigate losses in the portfolio. For a number of years, many experts have been warning about overinflated markets that were just waiting for a spark to ignite the entire system.

I warned investors that we were in a triple bubble in stocks, bonds and real estate that was created by central bank policies. Although I concluded that a market crash was inevitable, I didn’t foresee that the spark to ignite all three bubbles would be the Coronavirus. While the virus itself is life threatening and will result in large demographic changes across the globe, the economic implications may be worse than the disease. Major economies in Europe, Canada and the United States have been shut down. Every industry — airlines, hotels, manufacturing, entertainment, sports, schools and retail — is in lockdown.  Most of the western world is ravaged by fear, isolation, loss of employment, loss of income and the psychological effect of this massive lockdown situation. Employees have either been terminated or laid off indefinitely. The scale of this unemployment crunch and financial crisis is beyond the reach of governments’ assistance. Many businesses will not be able to reopen once the health issues have been controlled.

When the health crisis subsides, the economic effects will last for years; we may, in fact, never recover.

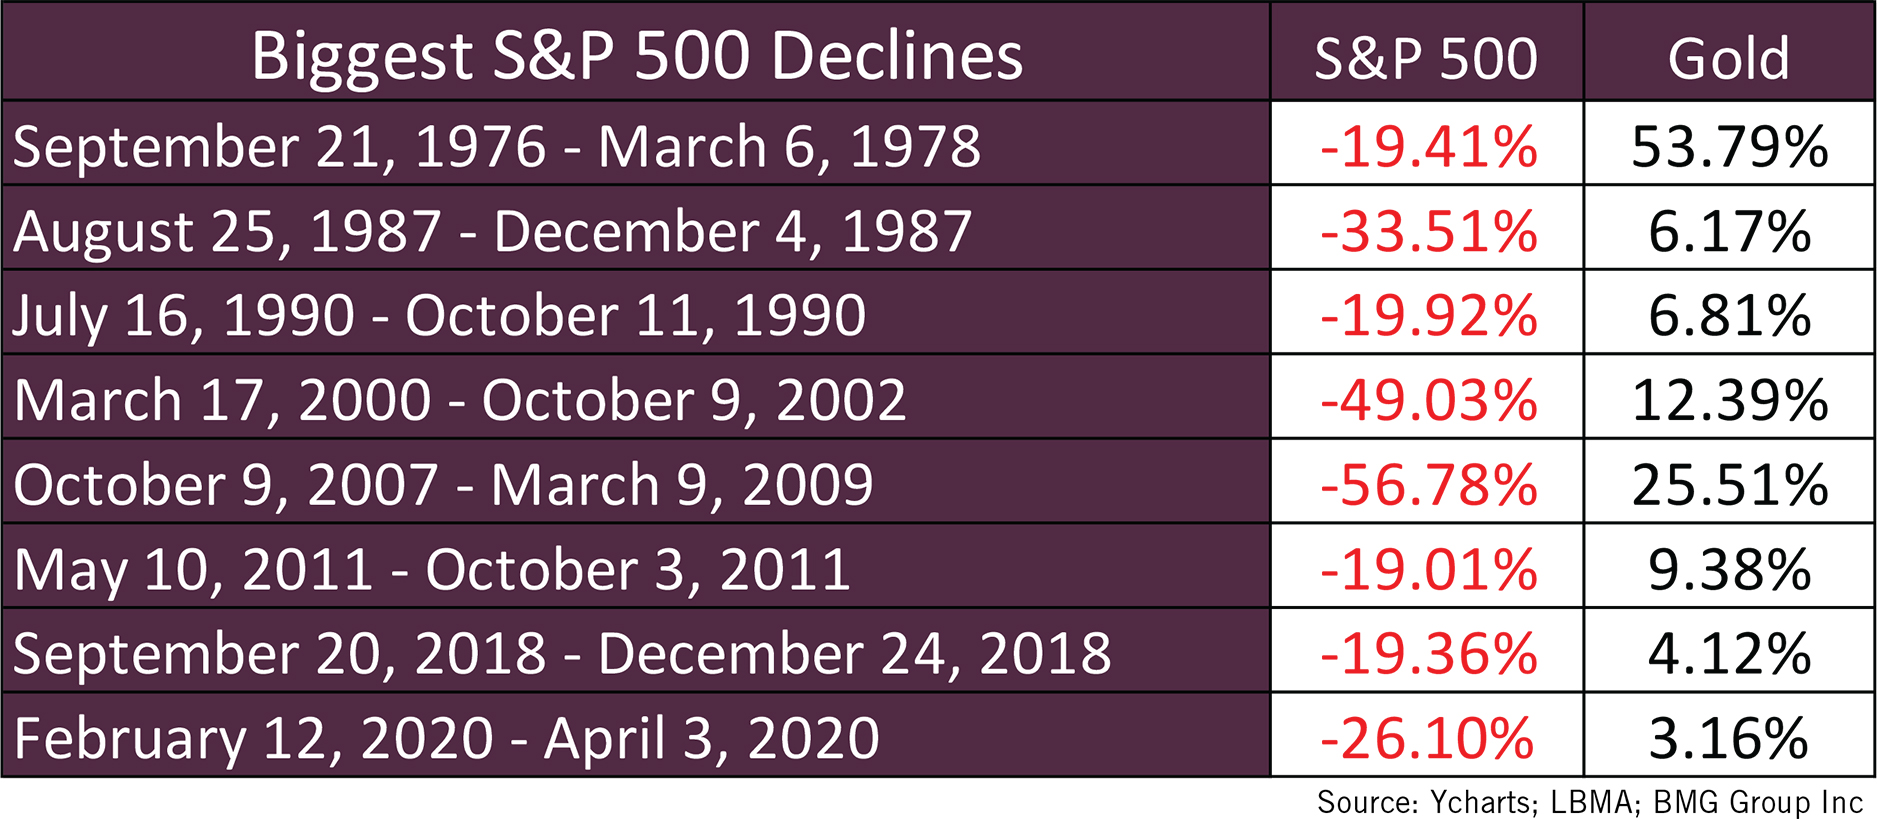
While there is a great deal of uncertainty because of the Coronavirus, there are two things that we know for sure.  Many industry sectors have no revenue, and governments will print enormous amounts of money in an attempt to mitigate the financial crisis. Most companies with no earnings will see enormous declines in share prices. Bonds, particularly corporate bonds, will default and become worthless. Even real estate is likely to suffer dramatic declines as both commercial and residential tenants are likely to default on rent payments. This in turn will result in mortgage defaults at every level, and properties will be sold at fire sale prices. These conditions create a perfect storm for an increasing gold price.

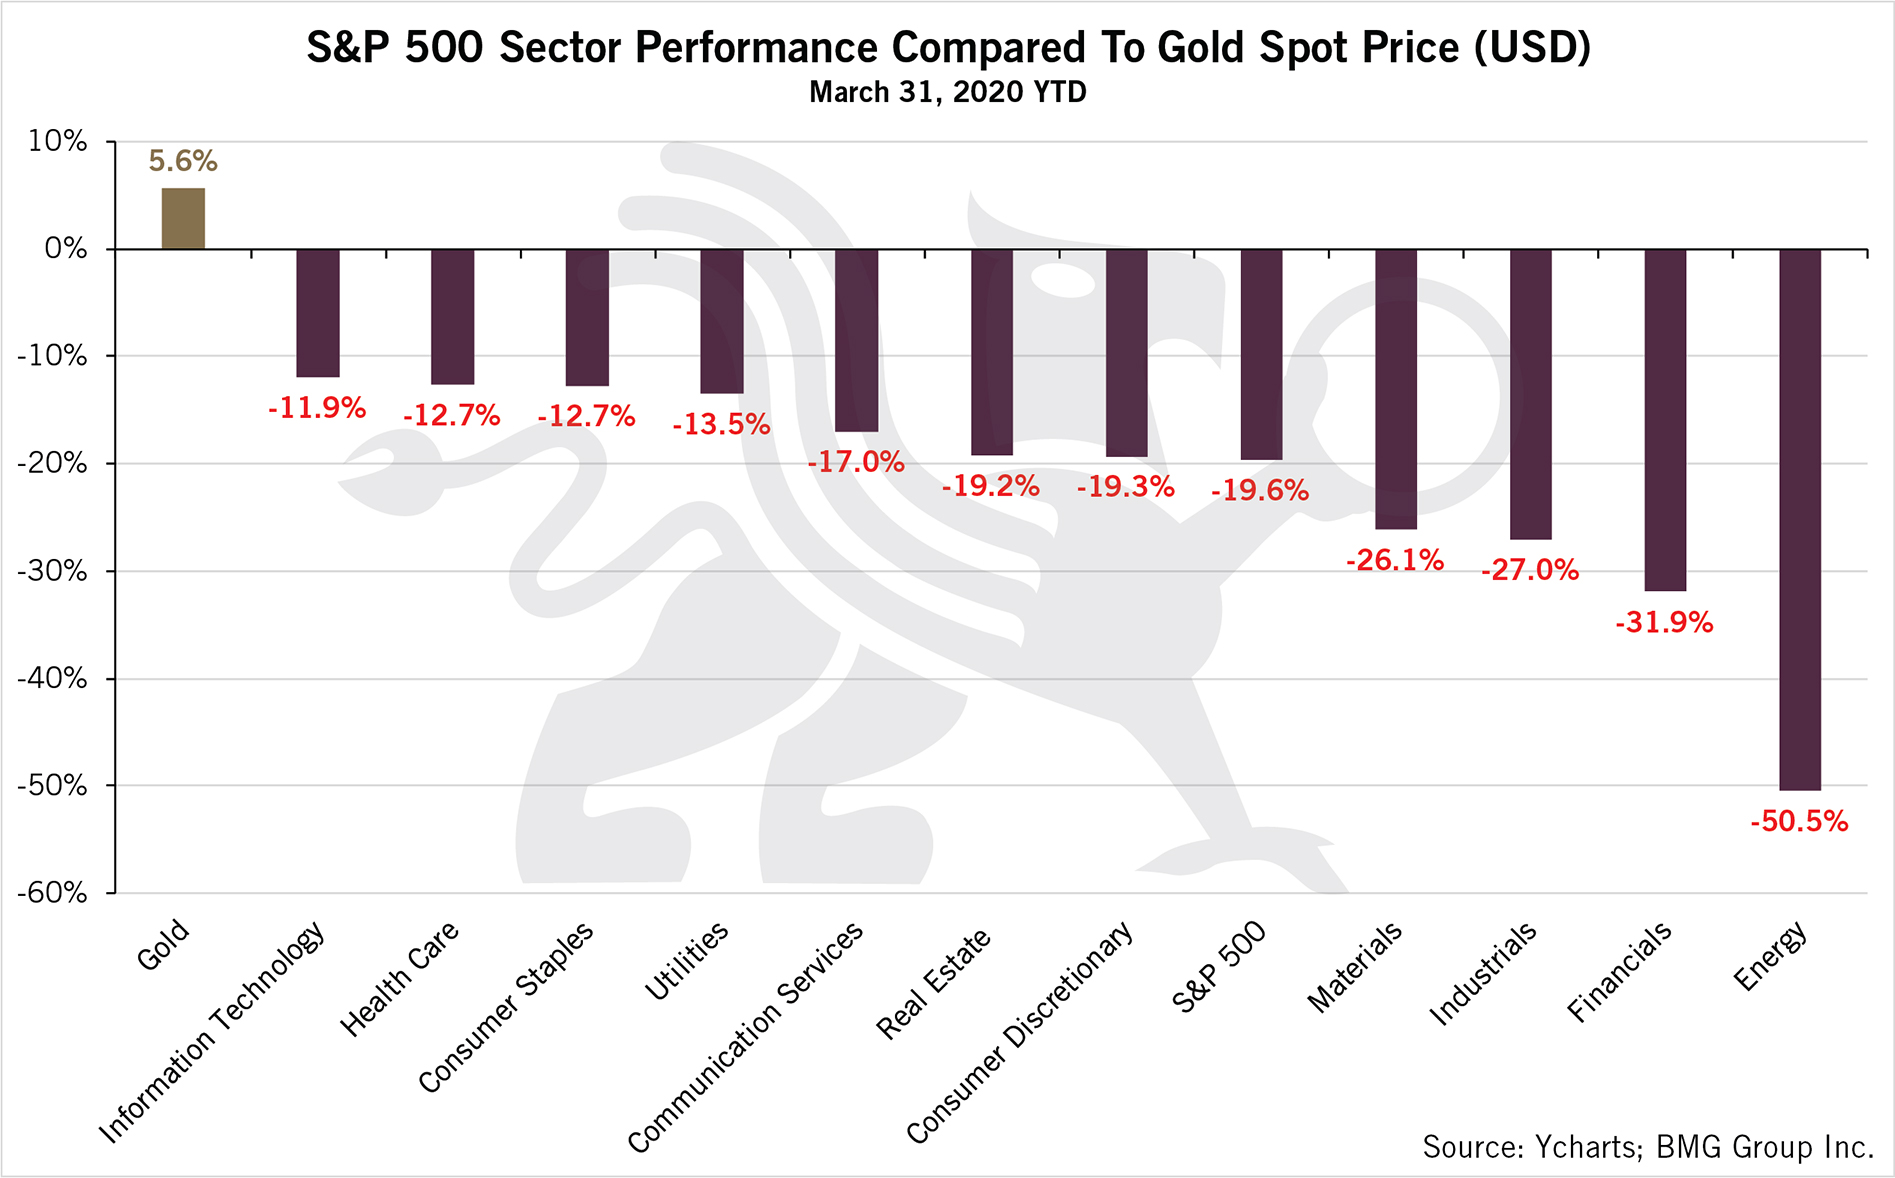
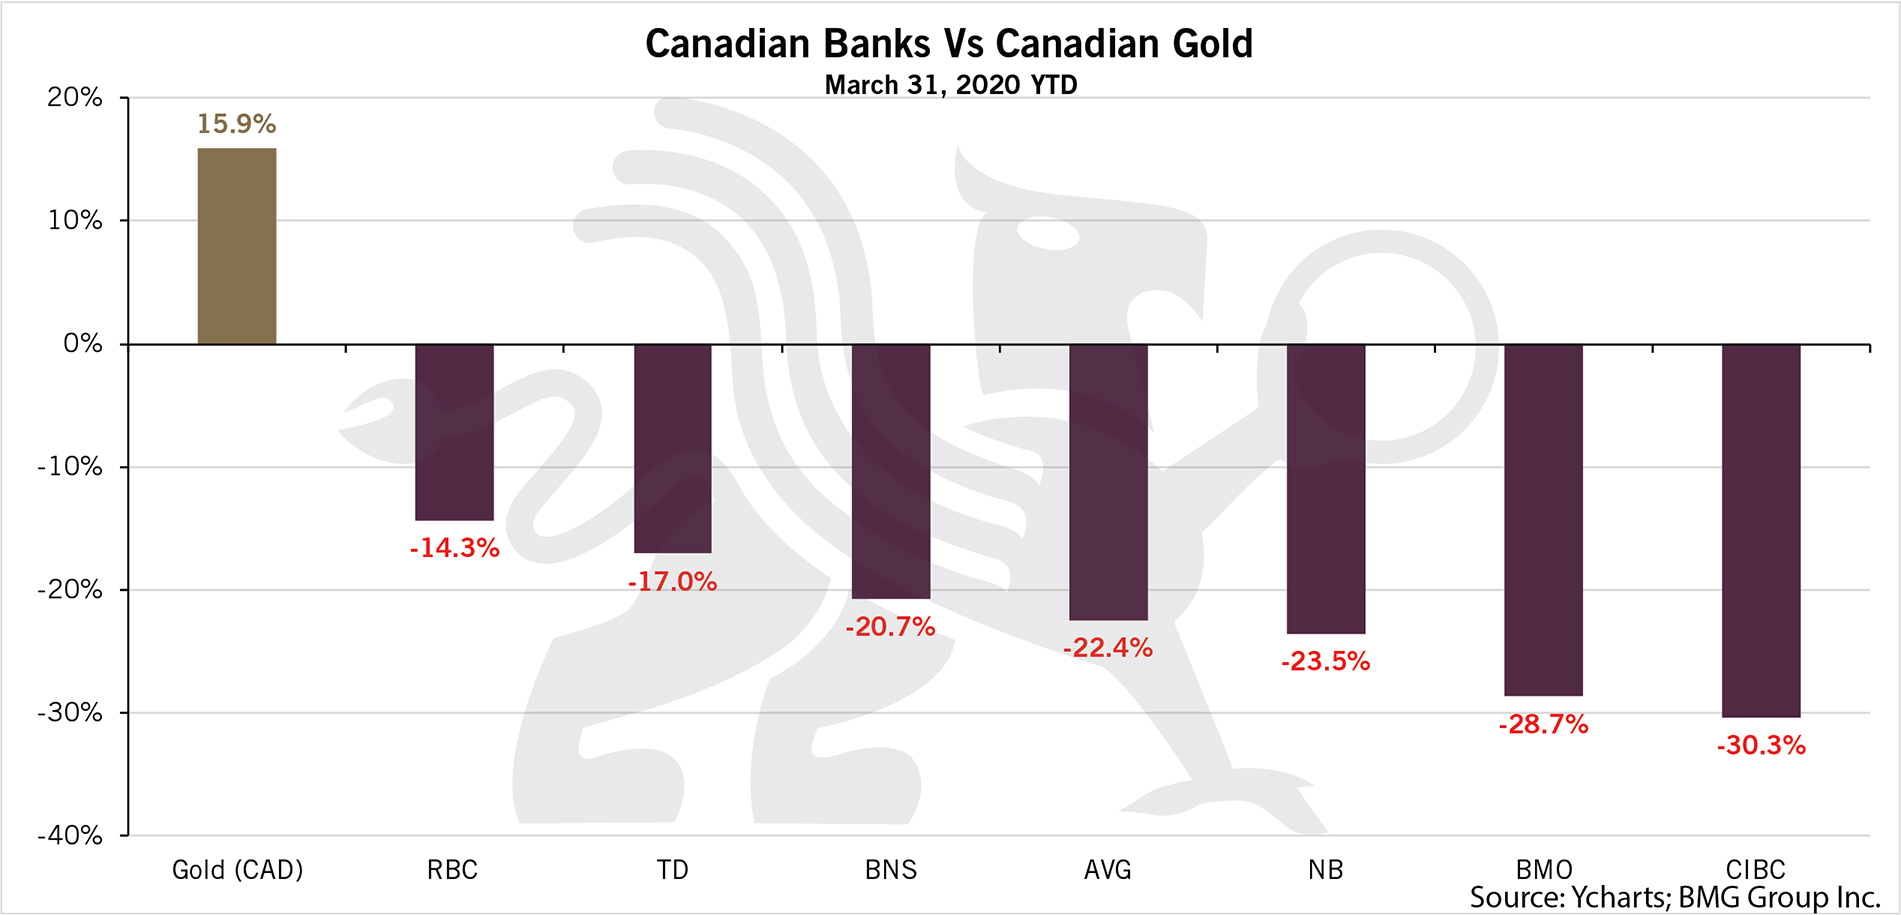
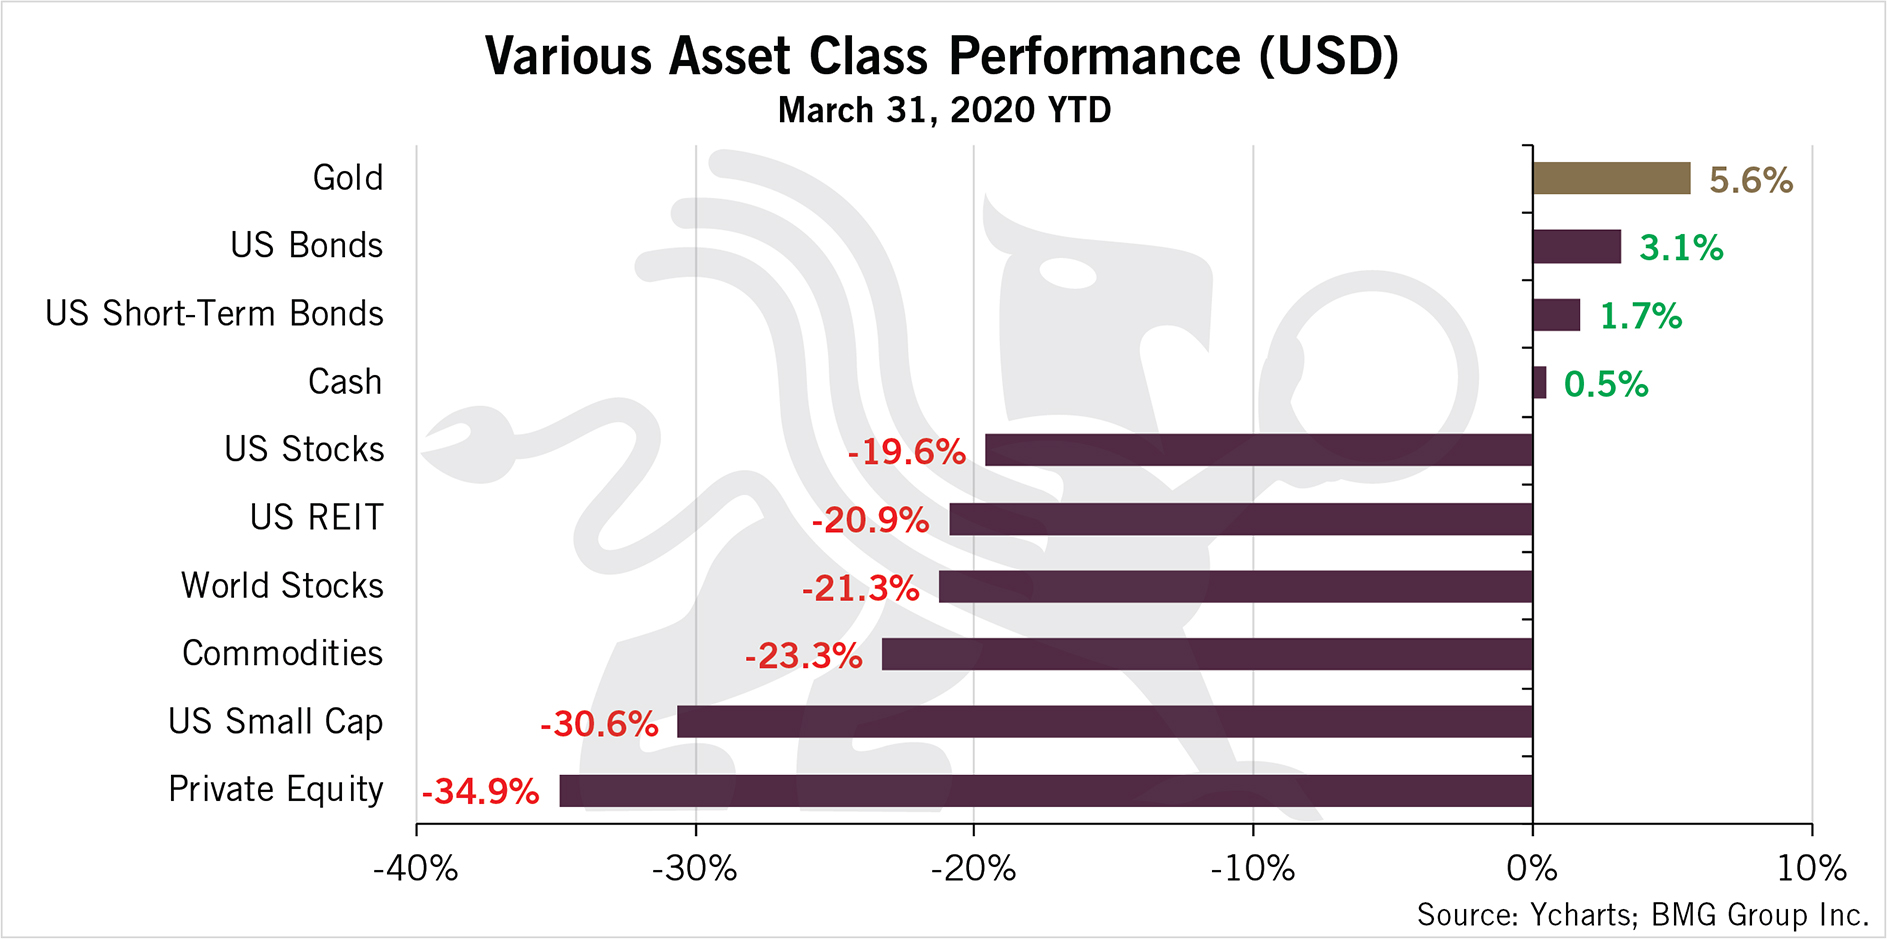
Stock markets around the world have suffered the worst first quarter in history.  Every sector, other than gold, has suffered losses from 12% to 50%. (See chart at the top of this blog)

These declines will be particularly hard on individual retirement portfolios, as well as pension funds. The baby boomer’s dreams of retirement are quickly evaporating. I wrote about the coming pension problem in September 2019. Even the largest pension funds, which have more diversified portfolios due to their real estate holdings as well as stocks and bonds, will experience dramatic increases in unfunded liabilities. Most smaller pension funds that only hold stocks and bonds will be devastated. Even before the Coronavirus implication, many municipal pension funds in California had already sent notices to retirees informing them that their future pension cheques would be reduced by 50%. Riots had already started in France and Chile.

For North American public companies, the increases in unfunded pension liabilities will negatively impact balance sheets, and the unfunded liabilities will have to be amortized over five years, thereby reducing corporate profits at a time when they may be non-existent due to the Coronavirus lockdown. This will put additional downward pressure on stock prices at a time when they are experiencing ongoing declines.

For current retirees, there is the double whammy of declining pension assets together with unemployed workers no longer contributing to the pension funds. The reduction in monthly payments is inevitable, and so are the lawsuits that will follow.

Most pension funds and individual retirement portfolios consist of only financial assets – stocks and bonds. These have already suffered significant declines; REITs and oil have been hard hit, too.

Even bank stocks, which are considered safe for conservative investors, have suffered significant declines.
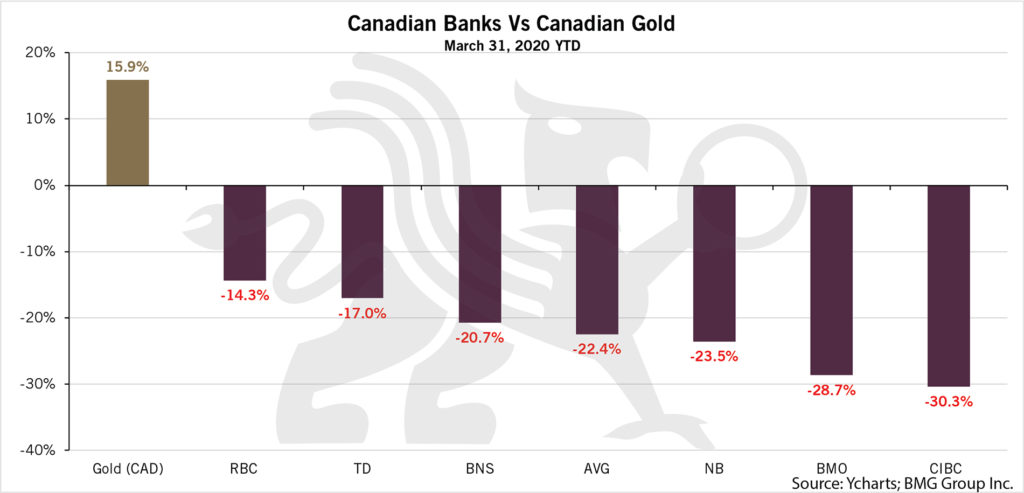
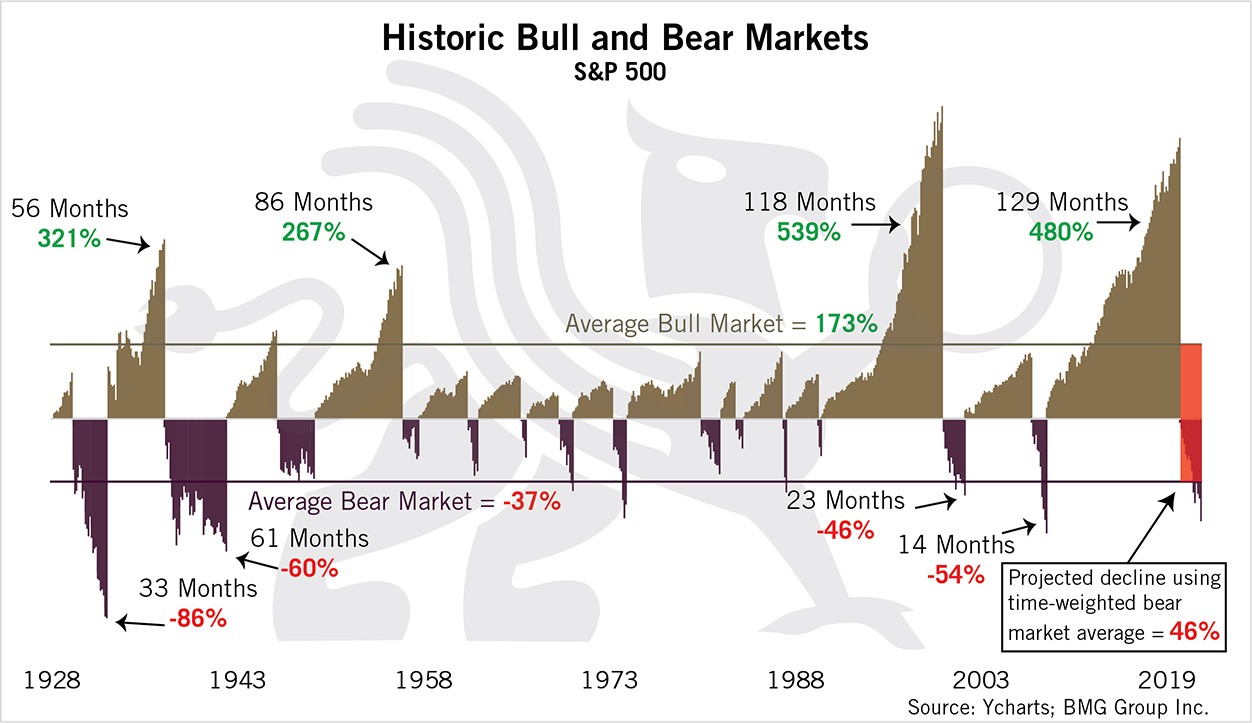
It is critical to note that there is no recovery in sight, and corporate earnings will be non-existent for the foreseeable future. Many experts believe this crash will be worse than that of 1929, and that we have just experienced the first phase.

The only asset class that will do well in the foreseeable future is precious metals, particularly gold.
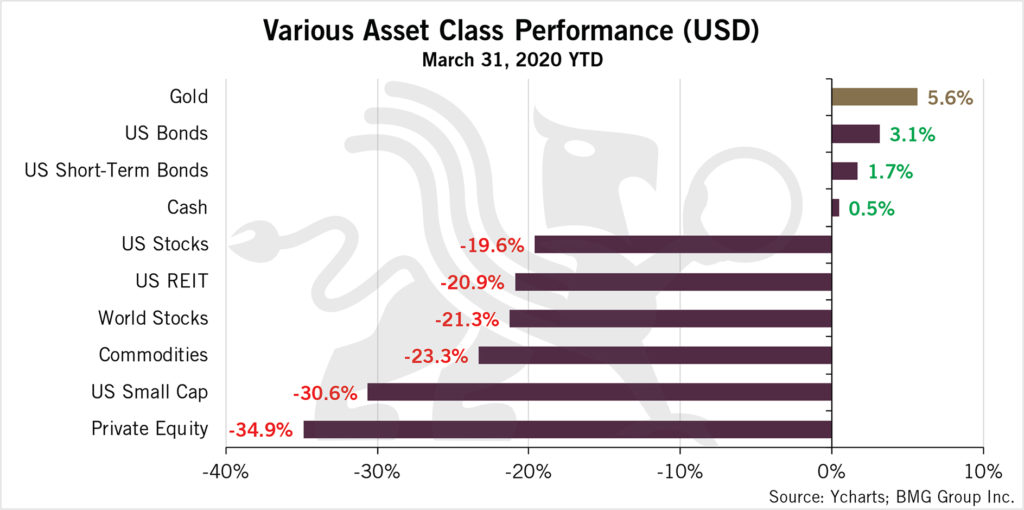
While there have been years of losses, particularly in 2013, gold has risen in all currencies since 2000 (see chart), and many investors are surprised by its steady performance. If you’d purchased gold in 2000 at $350, it’s now worth around $1,700, which gives you an average compounded return of about 9%. Most pension funds have target performance requirements of 6% yet have totally ignored gold in their portfolios. From its low in 2018 gold’s performance has dramatically improved. In 2019, the average increase was 17.8%. The YTD average for 2020 is 15.8% in the first quarter alone. This should annualize at about 63% per annum. Since the US dollar is often used as a safe haven by citizens all over the world, the gold performance in US dollars has been the lowest at 5.6% in Q1 2020. In Canadian dollars, gold is up 15.9% YTD.

When compared to stocks, gold has performed extremely well against all major stock exchanges.

Today, the mainstream media is misleading investors by encouraging them to stay invested for the long term. While it is a good strategy not to trade in and out during a bull market, it is completely misguided in today’s environment. The market is poised to fall much farther, and it makes no sense to stay invested in financial assets and sustain further losses. This chart shows how long it has taken to break even after major declines:
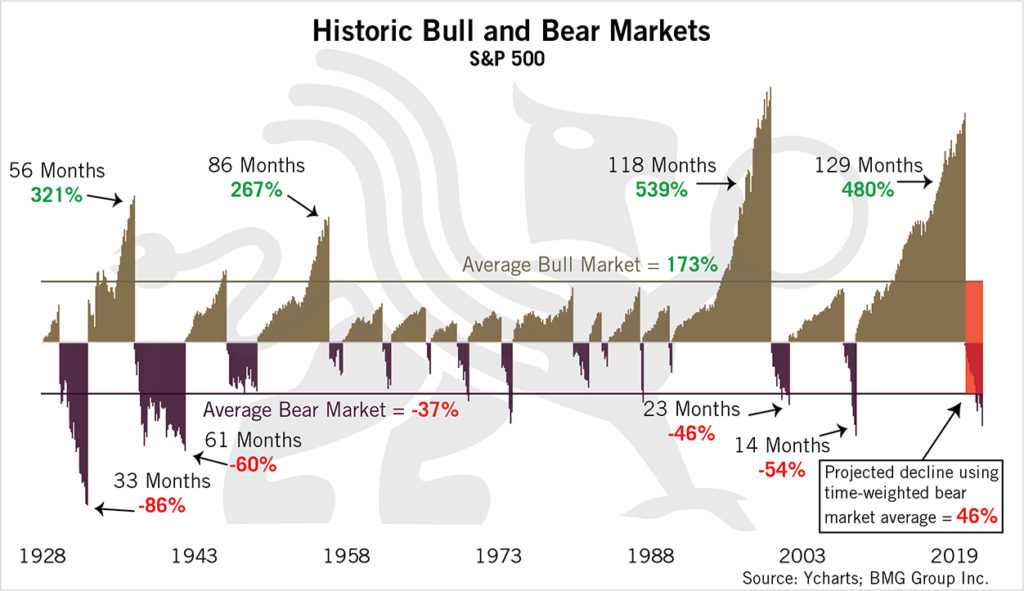
What many investors don’t realize is that if a portfolio declines by 50%, it would have to increase by 100% just to break even.

Most baby boomers will simply not live long enough to break even after this market crash. Investors would be better off switching to cash, and then reinvesting at close to the bottom. What is the point of staying invested in order to get dividends of 3-4%, while risking capital losses of 50-70%? Better still would be switching to gold, experiencing significant gains and then redeploying the gains to a diversified portfolio of stocks, bonds, REITs, gold and silver when the market has finished correcting. Gold will rise dramatically while everything else will sustain massive losses, as in every market decline.
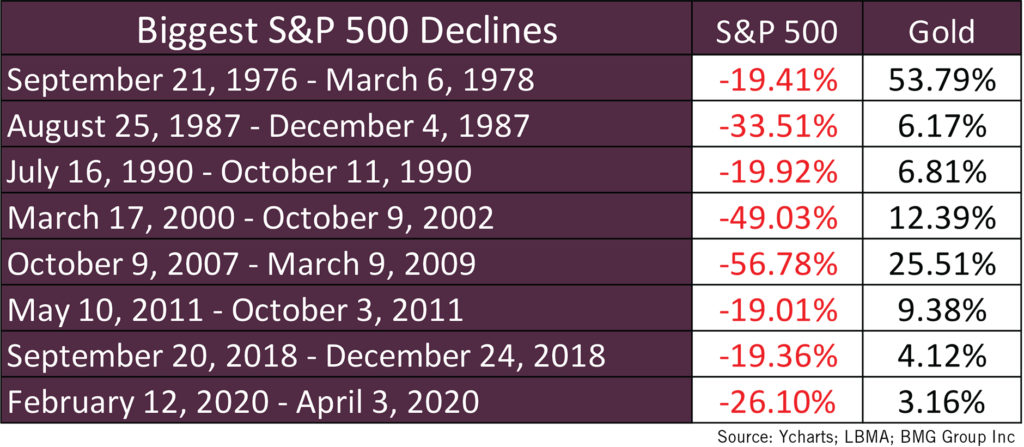
BMG has spent three years analyzing this approach, and it has established a hedge fund to implement this strategy

for accredited investors and institutions. BMG’s back-tested model for implementing this policy during the 2008 crash would have yielded returns of over 20% per annum.

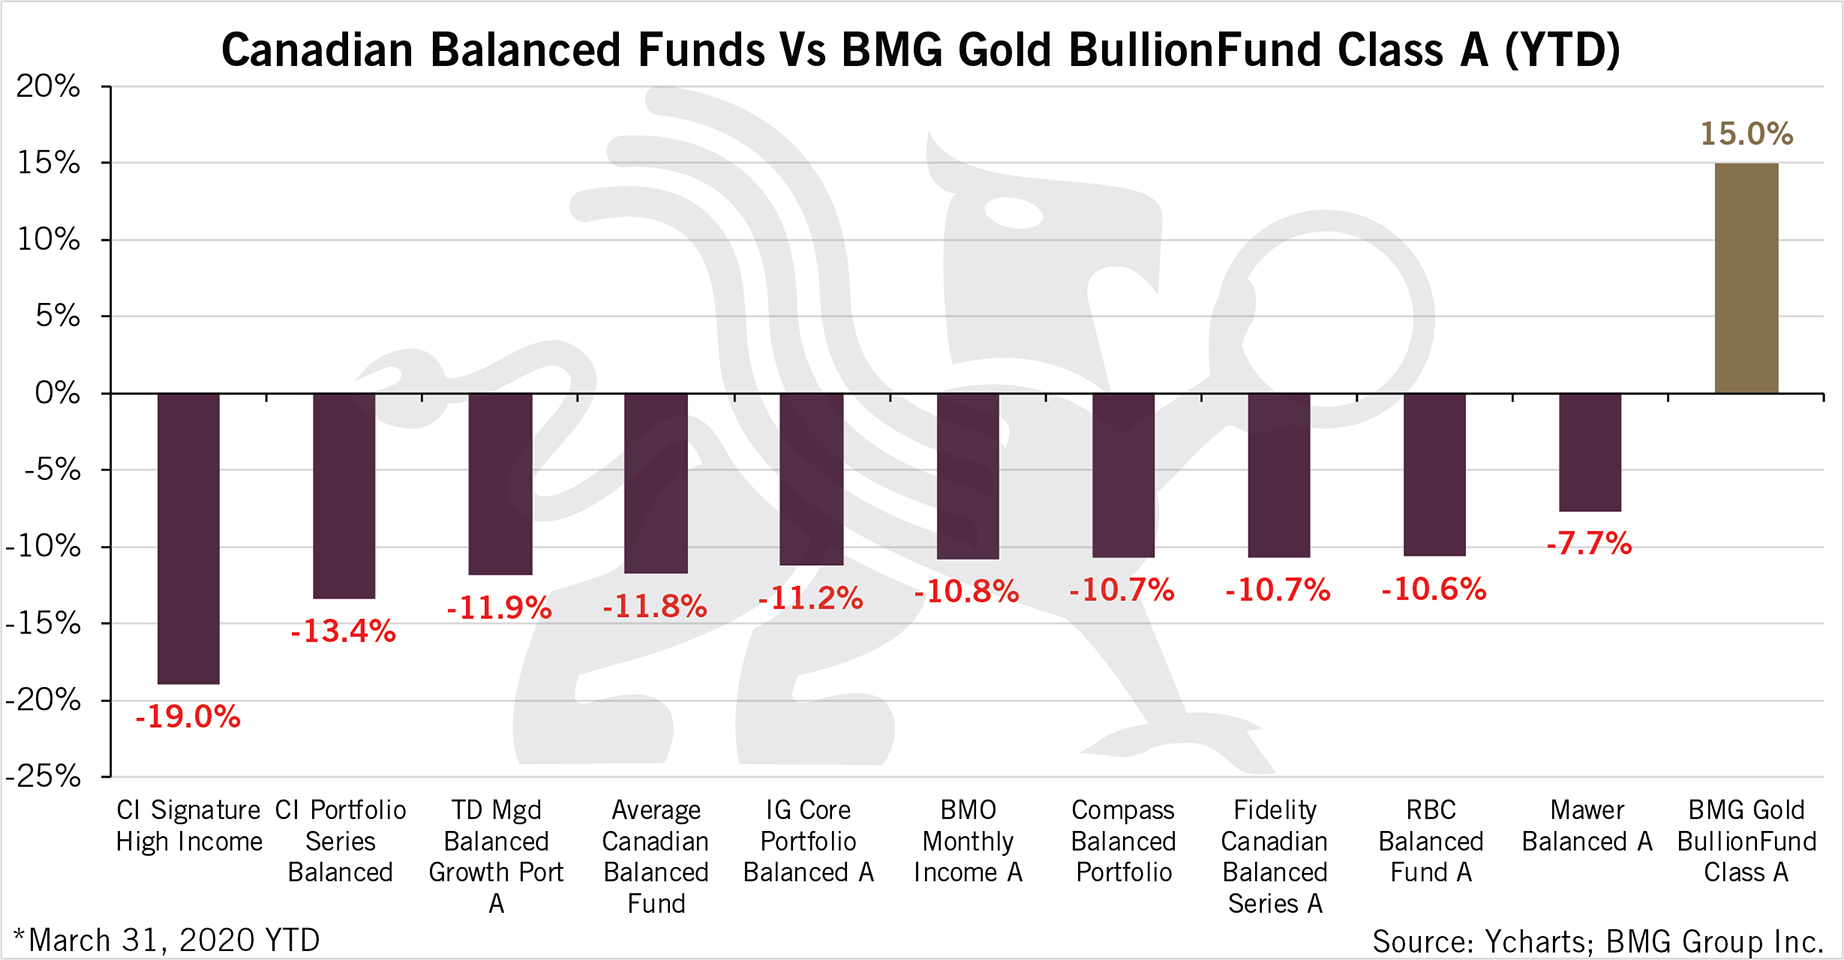
Over the past few years, many retail investors were forced into selling their bullion holdings by their advisor’s compliance department because their stated risk tolerance in their KYCs didn’t match the mandatory risk rating of their portfolio investments based on standard deviation. Many were persuaded by their advisors to sell their bullion holdings and purchase equities: particularly Balanced Funds. This chart clearly shows how bad this advice has been.
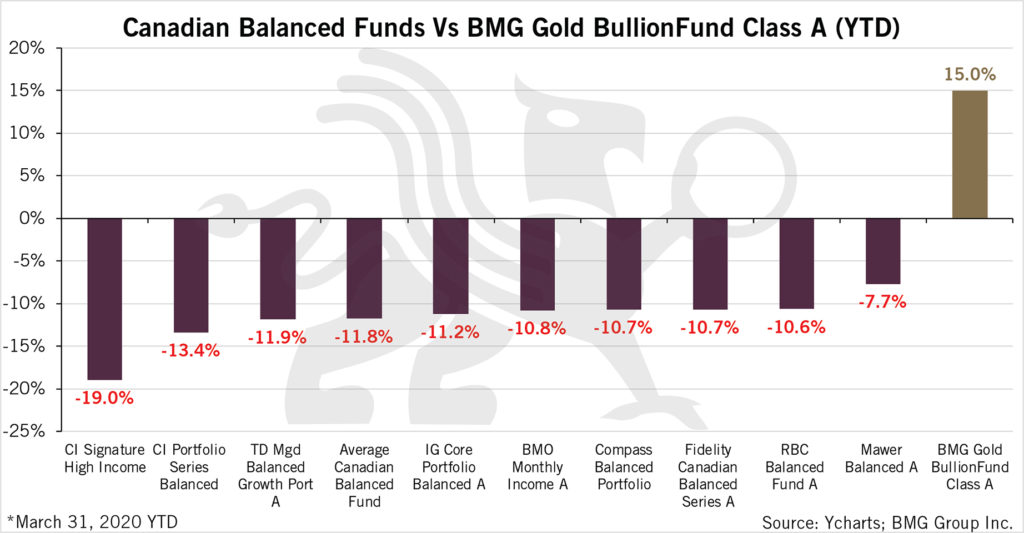
The only way investors could avoid these forced losses would be to open a discount brokerage account and make their own investing decisions by purchasing Class D units in a BMG Fund.  Not only would this reduce fees, but investors could allocate their portfolio as they saw fit and not be impeded by the rules imposed by the advisor’s compliance department. I have written about how these regulations were misleading investors.

To summarize: Under the current conditions, do you believe that now is not the time to stay invested? Would it be prudent to take whatever losses you have incurred and move to cash to preserve what you have left? Maybe it is time to become educated on the subject of gold by reading everything you can. When comfortable with what you have learned, do you think that a 20% allocation or more to gold makes sense? Here are some educational resources to help you start on your gold journey, the BullionBuzz, will keep you informed, and my book, $10,000 Gold—Why Gold’s Inevitable Rise Is The Investor’s Safe Haven, will give you a complete background.

Nick Barisheff is the founder, president and CEO of BMG Group Inc., a company dedicated to providing investors with a secure, cost-effective, transparent way to purchase and hold physical bullion. BMG is an Associate Member of the London Bullion Market Association (LBMA) as well signatory to the Six Principles of Responsible Investments (United Nations endorsed Principles for Responsible Investment – PRI).


Widely recognized as international bullion expert, Nick has written numerous articles on bullion and current market trends that have been published on various news and business websites. Nick has appeared on BNN, CBC, CNBC and Sun Media, and has been interviewed for countless articles by leading business publications across North America, Europe and Asia. His first book, $10,000 Gold: Why Gold’s Inevitable Rise Is the Investor’s Safe Haven, was published in the spring of 2013. Every investor who seeks the safety of sound money will benefit from Nick’s insights into the portfolio-preserving power of gold.
www.bmg-group.com

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.