Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Speculative Volatility in a free society

American economist and 2013 Nobel Prize Laureate Robert Shiller in 2014

John DeGoey, CFP, CIM

Special to the Financial Independence Hub

The final chapter of Robert Shiller’s book Irrational Exuberance has the same title as this blog post and contains a cogent synopsis regarding what some people believe is going on now.  In essence, stock market valuations (especially in the U.S.) have been high for years and most people (investors and advisors alike) didn’t seem to be fussed about it.  Here’s a verbatim passage from the book (page 225 of the 3rd edition), which was written in 2014, when markets were substantially lower than they were when the current down draft began:

The high stock market levels did not, as so many imagine, represent the consensus judgment of experts who have carefully weighed the long-term evidence.  The markets have been high because of the combined effect of indifferent thinking by millions of people, very few of whom have felt the need to perform careful research on long-term investment value, and who are motivated substantially by their own emotions, random attentions, and perceptions of conventional wisdom.  Their all-too-human behaviour has been heavily influenced by news media that are interested in attracting viewers or readers, with limited incentive to discipline their viewers or readers with the type of qualitative analysis that might give them a correct impression of fundamental value.

My translation of that passage might be as follows:

People make decisions about the value of stocks in general in a vacuum of personal experience and in the context of what others are doing; not in the context of whether stocks are cheap or expensive as compared to historical metrics.  Consequently, “groupthink” causes people to make their personal decisions based on the consensus behaviour of others, who, in turn, are not really looking at valuations, either.  The media exacerbates this behaviour.

On the following page, Shiller is even more pointed:

Understanding how social forces cause speculative market moves has been a major theme of this book.  It is so difficult for most of us to figure out which moves are caused by sensible good reasons and expert opinions and which are caused by human imagination and social psychology.  I hope that the argument to this point has made it clear that, as these major markets go, it is often the latter that drives prices.

My  translation: Continue Reading…

How to get through a stock market crash – and benefit from it

By Mark Seed

Special to the Financial Independence Hub

Unless you’ve been living under a rock, the stock markets have been a terrible mess.

On our Canadian side, we triggered market circuit breakers to halt trading in recent days.

In the U.S., the stock market dropped thousands of points in rapid successive trading days and remains well into bear-market territory within just a matter of weeks. It’s as almost if the market jumped out of a plane with a faulty parachute and spiraled out of control to earth; only some mild turbulence kept it from a total free fall.

Dow March 14, 2020

All havoc, no sanity

These market dives in very short order made me reflect on my own investing journey and how I might be able to survive this stock market crash. For today’s post, here are my ideas on how to get through a stock market crash – and benefit from it.

1.) Learn from history – reset your expectations

A sudden stock market crash is quite unnerving, but I don’t think it’s a sign of imminent full-on financial collapse. At least history tells us so. You’ll see from the chart above, recent weeks have been very messy to say the least. But over many years of investing in equities, the chart actually looks like this:
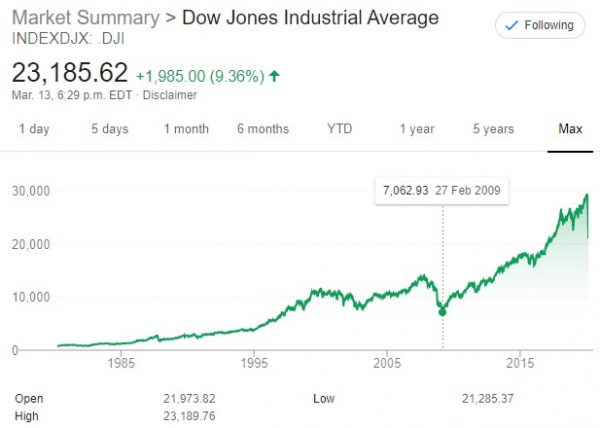
I’ve highlighted near the bottom of the 2008-2009 Great Recession for reference.

Although it’s very difficult to wrap your head around this fact and behave accordingly, stock market history consistently tells us the financial markets do eventually recover. And, after they recover, looking back through time, they continue to deliver rather predictable long-term returns. Here is what the U.S. stock market has returned by the decade and from what:

A Wealth of Common Sense - Returns by Decade

Source: https://awealthofcommonsense.com/2019/12/where-have-all-the-stock-market-returns-come-from-this-decade/

Even near-term, our Canadian and U.S. stock markets have been a very good place to be to build wealth:

Index Proxy Fund 5-year return 10-year return Since inception
S&P/TSX (Canada) XIC 6.27% 6.77% 6.53% (2001)
S&P 500 (U.S.) IVV 11.65% 13.50% 6.15% (2000)

Source: iShares site, up to December 2019.

I firmly believe this is why you need to stay invested throughout a stock market crash.

What goes down will (eventually) go back up in time.

2.) Learn from history – buy when stocks are on sale

The fact that equity markets have done well over the last decade, let alone generations (despite the occasional very scary bump) should be a reminder that stocks remain a great long-term investment to build wealth. But as we all know by now, scary bumps can and do happen. As in now.

Dow since 1985 to March 14, 2020

This means selling stocks in a panic (also as in now) is probably not a wise move. Ideally, successful investing is about buying something at a low to modest price and watching that asset accumulate in value. That means staying investing like I mentioned above but that also means buying low, selling high (if you need to sell at all). When you sell after a market crash or a major correction you do just the opposite.

You and I both know by now we cannot control market swings. We can control our investing behaviour. We have no idea of when the market will swing nor by how much. We only know that it will.

The best time to buy stocks is when you were going to buy them anyway.

So, I believe, you should consider stock market crashes as a buying opportunity. I mean, a market correction or crash simply signifies stocks are on sale per se. Consider the following and your behaviours associated with these statements:

  • Would you panic sell your house if it dropped 20% in value in a few days or weeks?
  • Would you buy more gas for your car if it dropped 20% at the pumps?
  • Would you buy more groceries and toilet paper if it was on sale during the impending viral apocalypse?

You know your answer and I know yours too.

So why is the stock market different? 

Much has been written about buying in lump sums being somewhat more favourable than any dollar-cost averaging (i.e., buying-in slowly) during a market correction. To be honest, I don’t care what you pick. Just invest. 

As Jonathan Clements, a former Wall Street Journal columnist once said:

“If you want to see the greatest threat to your financial future, go home and take a look in the mirror.”

This implies that successful long-term investing is directed tied to your emotional fortitude and behavioural discipline. While poor investing decisions can and may very well occur from time to time, it’s important to learn from them. It is therefore imperative that investors recognize their behavioural pitfalls before committing to any decisions which can affect their investment goals.

One of my favourite, easy-to-read books on the subject of building wealth is targeted to millennial investors but applies equally to investors of all ages is If You Can. This book is designed for modern attention spans. It’s only 15-minutes of reading and gives you information you need to be a successful investor in a few pages.

You can read an overview of this book and download a FREE copy of it (yes FREE) here. 

3.) Learn from history – continue to improve

How high your returns could be (for a long-term stock market investor) over the next 30+ years is not really up for too much debate – based on market history. A 100% equity portfolio in the broad U.S. stock market is probably going to deliver close to 7% annualized (plus or minus a bit) and likely 3-4% in real returns (after inflation is factored in) in the coming decades.

I can say with more confidence that I will not find myself wealthier if I do not learn from my own investing history and continue to improve upon it over time.

I got a few reader emails over the last few weeks and I thought I would share them before I share my next steps in this current market correction for context – what I’m doing to improve. Emails adapted only slightly for posting. Continue Reading…


7 ways retirees can weather the Coronavirus storm

By David Field, CFP

Special to the Financial Independence Hub

If you’re a retiree or looking to retire soon, the COVID-19 Coronavirus is likely causing you anxiety about your finances: and I want to help relieve it.

As a financial planner, I’ve spent the last couple weeks providing guidance to my clients during this tumultuous time.

While I have no medical advice to offer (nor should I), nor do I have any way to predict the future, I’ve heard some very dangerous generic advice regarding people’s personal finances.

Simply advising people to “wait for the markets to go back up, and all will be well” ignores the fact that you may need income now, meaning you can’t just “wait it out.”

If you are retired, or looking to retire soon, here are seven actions you can take now to help reduce your financial anxiety.

1.) Create or maintain a cash reserve

Having cash easily accessible gives you options, especially in stressful times. There is a lot of noise out there in the financial media suggesting that “stocks are on sale right now,” and, as a result, you should allocate some of your resources to buying them.

If you are close to retiring (in the next year or so), or you are retired, I advise you to make sure you have enough cash to cover your living expenses for the next three years.

Then, and only then, if you have cash left over then you may want to take advantage of depressed stock prices.

2.) Sell your bonds, not your stocks

If you need to create cash, don’t sell your stocks: sell your government bonds. Assuming you have a balanced investment portfolio, you likely have government bonds somewhere in there.

With stocks decreasing, along with interest rates, those bonds have increased in value. This is why you have government bonds as part of your portfolio. (Be careful: don’t mistake government bonds for corporate bonds when selling your bonds.)

If you are in balanced mutual funds or ETFs, you may not be able to sell just your government bonds. If you sell your balanced mutual funds or ETFs to create your cash reserves, you’ll likely suffer some investment losses: but those losses should be much smaller than if you were to sell all-equity funds or ETFs.

Human behaviour causes us to want the safety of government bonds when we see our stocks decreasing in value: that means we’re selling stocks at a discount and buying government bonds at super-high prices. Try to avoid this behaviour, as it means your portfolio will get hurt on both sides.

3.) Postpone your retirement date, if you can

If you were planning on retiring soon, I recommend delaying implementing that decision by at least a few months. (The exception would be if you have a defined benefit pension that will provide most of your retirement income, and which gives you a defined retirement date.)

Once you start your retirement income, which is likely to come from many different sources, it can be difficult — or even near impossible — to make changes. With the COVID-19 virus changing the narrative every day, there’s a ton of uncertainty out there; meaning it is likely prudent to hold off retiring if you can.

In addition, if your employer needs to reduce its workforce in response to the current crisis, there may be some attractive options or financial offers that provide incentives for you to retire. If this happens, any kind of severance will provide an income cushion before you start your retirement income.

4.) Cut back spending

The math is very basic: If you reduce what you spend, then you will require less income from your investments.

While this is always the case, right now cutting back might be easier than ever. With vacation plans cancelled or postponed and no sports, music or performances to go to, it may be easier to save money than if you’ve tried in the past.

5.) Expecting a refund? File your 2019 tax return ASAP Continue Reading…

How is your portfolio holding up? How are you holding up?

CutTheCrapInvesting: Image by Christian Dorn from Pixabay

By Dale Roberts, CuttheCrapinvesting

Special to the Financial Independence Hub

It’s possible that you haven’t looked at your portfolio. It’s possible as well that you haven’t looked in the mirror. To not look at your portfolio might be a good strategy. I’ve heard from a few readers who offer that they will not look, just yet. But it’s certainly important to be aware. Your portfolio has likely lost some value. Today we’ll frame that for you with a look at the iShares one-ticket asset allocation portfolios. How is your portfolio holding up in the recent correction? Let’s have a look at the recent performance of Balanced Portfolios.

Is USA 2020 like Japan 1990?


Tokyo. From a high of 38,915 late in 1989 the Nikkei then fell 82% by March 2009

John DeGoey, CFP, CIM

Special to the Financial Independence Hub

It sure looks like there’s a fair amount of hubris in the American stock market these days.  The American 30-year bond just hit an all-time low of 1.89%.  We had three rate cuts in late 2019 despite strong employment and GDP numbers.  Household debts are again high as are defaults on car loans.  Many people (and especially many advisors) continue to blithely opine that we might be the middle of a more than 20-year supercycle and that it’ll be another decade before we have a major pullback in capital markets.

I call B.S.  Perhaps more to the point, my view is that this is a clear example of groupthink / herding / motivated reasoning that will almost certainly give way to narrative fallacy justifications down the road.

What if the pundits got it exactly wrong?  I want to stop here and remind that I’m asking a question; not making a statement.  I don’t know (neither does anyone else), but … what if instead of this being the beginning of a supercycle, we’re at the tail end of a 11-year long bull market?  What if this is as good as it gets for a long, long time?

Nikkei fell from a high of 38,915 late in 1989, to low of 7,055 by March 2009

I’d like to take this opportunity to remind you of what has already happened to the second-largest stock market on the planet.  On December 29, 1989, the Tokyo Nikkei hit an all-time high of 38,915.  That high, coinciding nearly exactly with the end of the decade, has not been seen since.  Ironically, stock markets around the world also took a big tumble at the end of 1999 heading into the scare around Y2K.  Again, a big tumble coincidentally occurred at the end of a decade.  As I write this, we’re in Q1, 2020 and the roaring 2010s have just ended.

Getting back to Japan, their market dropped all the way down to a low of 7,055 in March 9, 2009 – a total drop of nearly 82%.  That’s comparable to the experience of the Great Depression.  Even now, more than 30 years after hitting that peak, the Nikkei is below 24,000.  That’s STILL a drop of well over one-third more than thirty years AFTER hitting an all-time high.  With Japan as a backdrop, we could  point to that experience as a potential cautionary tale.  I personally would not be particularly surprised if the U.S. market was trading at a lower number in 2030 than it is today.  Does your plan take that possibility into account?

John De Goey, CIM, CFP, FP Canada™ Fellow, is a Portfolio Manager with Toronto-based Wellington-Altus Private Wealth Inc. This blog originally appeared on the firm’s “Newswire” site on March 9, 2020 and is republished on the Hub with permission.