

 Posted By
 By Rick Lunny, Manulife Bank
Special to the Financial Independence Hub
As a father of five with two 20-something daughters who recently moved out, I often hear how the sheer amount of information in this digital age overwhelms those who are entering the workforce and starting their adult lives. Somehow by default, I have become an unofficial mentor for both my kids, and their broad circle of friends, as they regularly seek my advice when facing important financial and career decisions that will shape their future.
They frequently comment how there’s always new, conflicting advice on how best to live life. Especially when it comes to money and how to make the most of it: save more, live for the moment, pay down debt, and yes, even plan for retirement at age 24.
It’s a struggle to find time to break through the noise and choose the best financial options that truly fits their needs.
And it’s not just the younger generation who struggle to make decisions and take control of their finances.
As the head of Manulife Bank, a subsidiary of Manulife which serves seven million Canadians, I know customers of all ages are looking to develop better financial habits and improve their financial wellbeing.
Canadians are looking for clarity, simplicity and value from their bank. This applies equally to technology interfaces. They expect – and deserve – from initial application to ongoing experience, products that have a human-centric design, with intuitive and easy to use interfaces.
That’s what I love about Manulife Bank. I joined five years ago because it was different from other Canadian banks. It had an entrepreneurial reputation for going beyond the status quo with innovative banking products designed in the best interest of Canadians. Continue Reading…
 Posted By
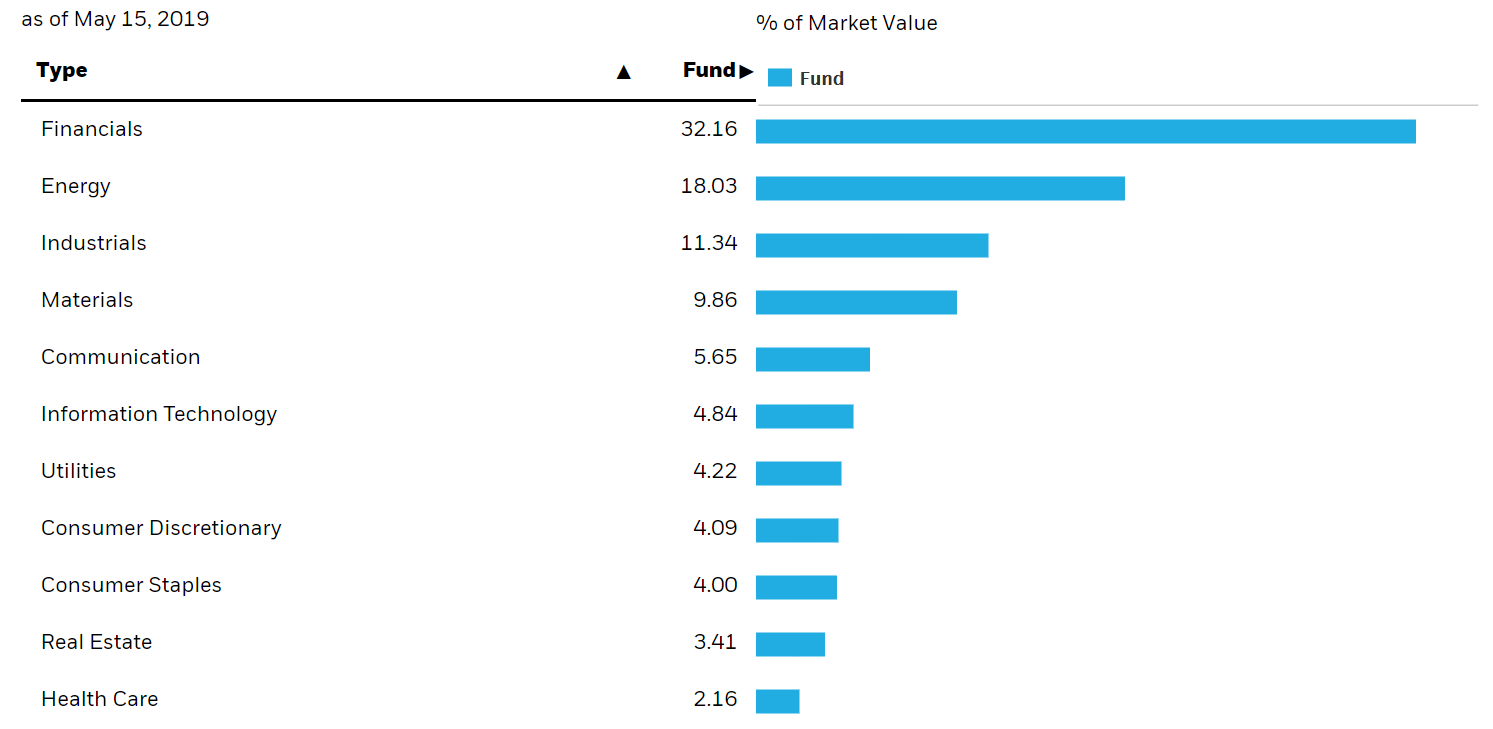 The Canadian investor needs the sector and geographic diversification offered by the US and perhaps International markets. Here’s the sector breakdown of the S&P 500, by way of iShares IVV.
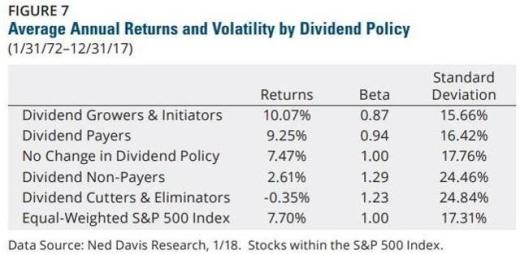
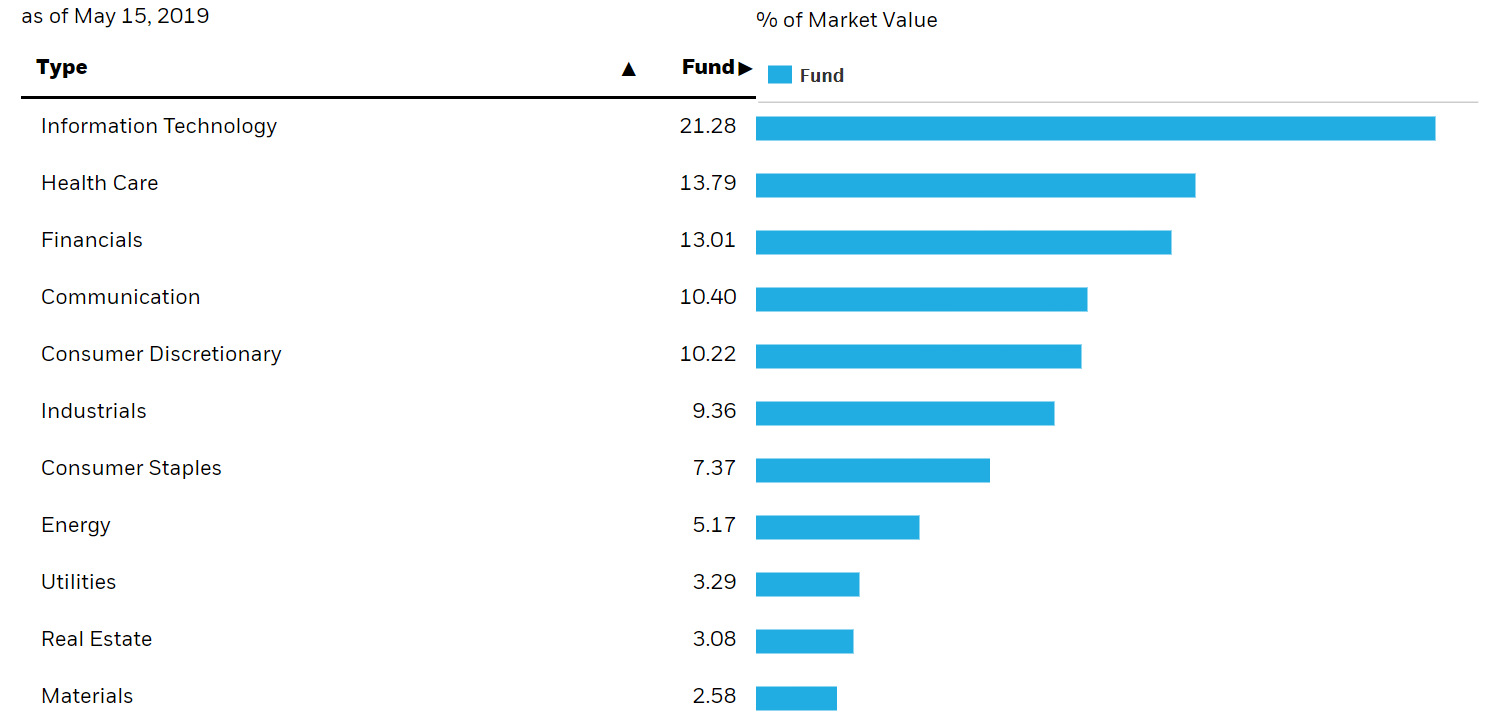 The basic principle of the need for added diversification holds true whether a Canadian investor embraces core index funds or dividend focused funds. How much you add by way of International exposure is certainly a personal decision. I am of the opinion that you might go light on that front given that the large and mega cap US companies earn a considerable percentage of their profits overseas. That said, in a recent CTCI investing post I suggested you might also look to developing markets where there is
