Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Franklin Templeton unveils multi-asset ETF portfolios for mutual fund advisors

Franklin Templeton Canada president and CEO Duane Green

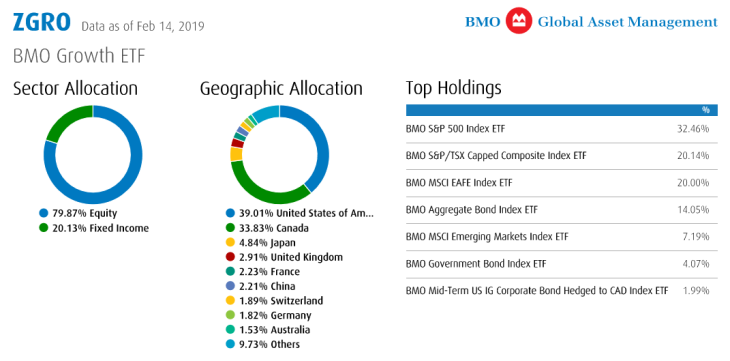
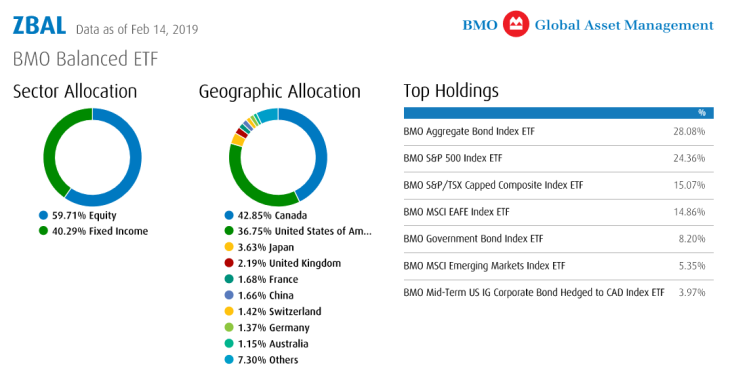
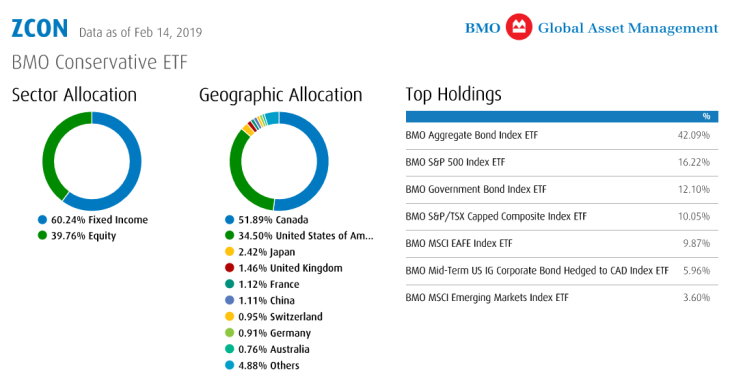
Since Vanguard Canada introduced three (now five) asset allocation ETFs a year ago, rivals have been scrambling to catch up. Little wonder, as those first three products — bearing TSX tickers VBAL, VGRO and VCNS — quickly scooped up a billion dollars in assets. Next out the gate was BlackRock Canada’s iShares, which launched two All-in-One ETF portfolios in December 2018 with similar-sounding tickers: XBAL and XGRO. Then a few weeks ago, as Dale Roberts nicely summarized here at the Hub, BMO ETFs jumped aboard with a similar suite as Vanguard’s original suite: ZBAL, ZGRO and ZCON, driving costs down as they did. See BMO keeps it simple.

Up until now, mutual fund salespeople operating in the MFDA channel (Mutual Fund Dealers Association) have been clamouring for ETF portfolios because if they aren’t also securities licensed, they couldn’t buy ETFs for their clients directly. That’s why Thursday’s announcement by Franklin Templeton is of interest: it announced the launch of three multi-asset ETF portfolios to provide advisors and investors with a simple solution for investing in ETFs. Managed by Franklin Templeton Multi-Asset Solutions, each portfolio is a mutual fund that provides access to active asset allocation utilizing a combination of active, smart beta and passive ETFs across multiple asset classes and geographies.

These portfolios let mutual fund investors access Franklin Templeton’s new passive ETFs (see this Hub post a few weeks ago), in addition to its active and smart beta ETFs while not having to worry about asset allocation, rebalancing and currency management.

Franklin Templeton Investments Canada president and CEO Duane Green said in a press release that “Many investors are overwhelmed by the choice of ETFs available in the Canadian market.” That’s  a fair statement, which is why I am working with Dale Roberts and eight other ETF experts to select the 2019 edition of the MoneySense ETF All-Stars, which will be published later this month. A year ago we were quick to spot the trend and made all three of the Vanguard portfolios All-Stars, albeit in a new category. The question for us this year is which of the newer offerings should be added? Stay tuned!

How these differ from Balanced Mutual Funds

We’ll outline the names of the new Templeton funds shortly but I did want to add the fact that mutual fund companies have long offered balanced mutual funds and asset allocation funds, both Canadian and global. These are usually actively managed and of course generally bear the high MERs that have caused Canada’s fund industry to be so criticized. Once upon a time, I often wrote about the Rip Van Winkle two-fund portfolios, which was simply a Trimark Balanced Fund and Templeton Growth Fund. And I have written in the past that “in theory, the only fund an investor needs is a global balanced fund.” That’s because they would cover all asset classes and geographies, with rebalancing and asset allocation all taken care of by active managers. That’s pretty much what’s going on with these ETF portfolios, with the difference being that the fees are much much lower: 20 basis points plus or minus 2, or a tenth the price of a typical balanced mutual fund.

So back to Franklin’s new entry. Continue Reading…

Are current beliefs about RRSPs costing Canadians money in the long term?

By Edward Kholodenko

Special to the Financial Independence Hub

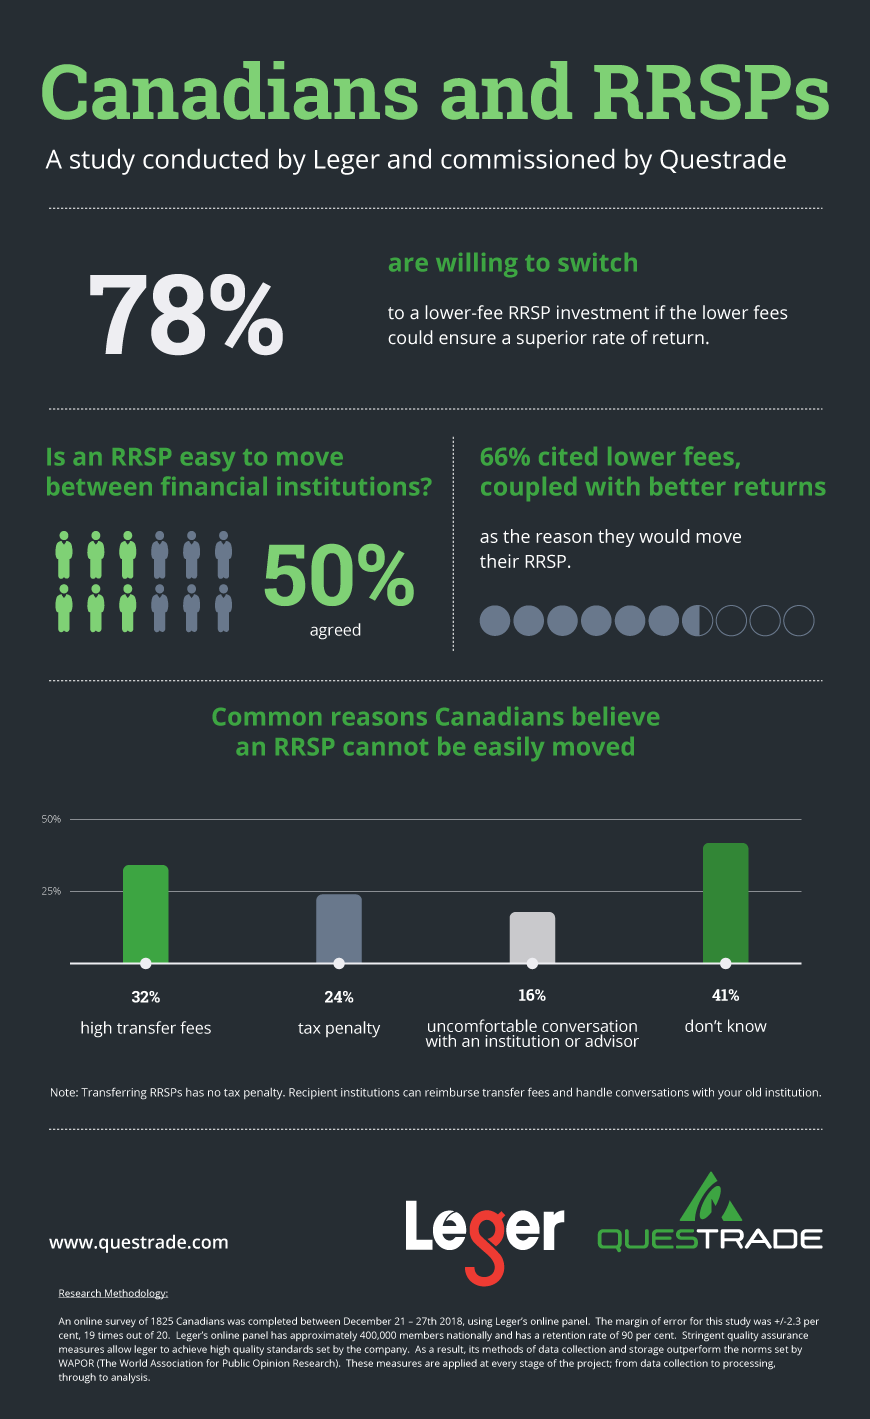
A recent study we conducted with Leger (www.leger360.com) asking what Canadians wanted in relation to their RRSP investments unearthed some compelling findings demonstrating that many Canadians have misconceptions that could be costing them money, especially in the long term.

Our research confirmed 78 per cent would be willing to switch to a lower-fee RRSP investment, if the lower fees could ensure a superior rate of return.  When we asked if they were able to move their RRSP easily, which factors would be most important, 66 per cent once again said they would move accounts for lower fees and better returns.

In addition to lower fees and higher returns, 31 per cent of people we talked to identified the ability to easily manage their RRSPs and make contributions online as a factor to consider in a switch (highest in those between the ages of 25 – 44 years), speaking perhaps to the rising appeal of newer fintech companies who offer the ability to do everything online.

When asked for other reasons they might consider switching their RRSPs, respondents cited frustrations including feeling like they’re being upsold (28 per cent), having to book an appointment and visit their financial institution in person (27 per cent) and not knowing what their RRSP is invested in (26 per cent).

This strongly suggests Canadians are far from content with their current RRSP contribution process and provider and would be willing to switch; however, there are misconceptions that are holding people back.  Most interesting — only 50 per cent believe their RRSPs can easily be transferred between financial institutions.

Common misconceptions

Why? Common misconceptions included high transfer fees (32 per cent), incurring a tax penalty (24 per cent) and even the fear of an uncomfortable conversation with their current advisor or financial institution (16 per cent).  While only 50 per cent of Canadians told us that they believe their RRSP can be easily moved between financial institutions, the reality is that RRSPs are easy to transfer.  There are no tax penalties incurred when an account is transferred and furthermore, most institutions would cover the cost of any transfer fee that may be charged and by consolidating your RRSPs at an institution with lower fees, you may reach your retirement goals faster. Continue Reading…

Retired Money: What retirement savers can learn from the finances of pro athletes

My latest MoneySense column looks at the seemingly enviable situation of professional athletes, and what us ordinary folk can learn about what it’s like to retire from a (typical) five-year career of earning big bucks, but then having a half century ahead of them. Click on the highlighted text to retrieve the full story: Why so many athletes run into financial trouble.

The article is based on an interview with Chris Moynes, a financial planner who specializes in managing money for NHL and other pro athletes, and reviews his book After the Game. it is available at Amazon.com or directly through his web site at www.onesports.ca, as is an earlier book called The Pro’s Process.

Most pro athlete careers average about 5.5 years. The median is just 4 years (so half have careers that last less than that) and of course a sudden critical injury could end it all at any moment. Of course, while it lasts the pay is astronomical compared to what mere mortals can generate in regular jobs: an average US$2.4 million per season. That means the average pro athlete will earn about $13 million over that short career. However, citing sportrac.com, Moynes says 200 of the 683 players in the NHL earn less than US$1 million per year, because the stats are skewed by the huge salaries of the biggest stars.

The 6 financial “Landmines” facing pro athletes

The opening chapter of After the Game outlines the six biggest “landmines” facing pro athletes. First is overspending and the combination of big paycheques spread over a short career. They seldom understand finances and often make poor investment choices, typically being prime targets for those selling “can’t miss” investments like nightclubs, casinos, real estate ventures and other private-equity type deals. Continue Reading…

5 common financial mistakes Millennials are making

By Noel Gonzales

Millennials have many opportunities in their hands today. With their skills and talent, they can earn more and do more with their lives. However exciting this is, it also becomes quite a challenging task for millennials to use wisely what they have.

Today’s trends on consumerism entice people to buy and spend more when they earn more, and this is where the trap of debt begins. Aside from this, here are five other common financial mistakes that millennials are making:

1.) Millennials don’t invest in the stock market or other financial markets

Millennials are tech-savvy, and most own a smartphone. Hence, investing in the stock market is not difficult to do nowadays. However, a lot of people, including millennials, still consider traditional savings as the way to go; they’re unaware that stocks grow more income than savings.

If you’re confused with how to start, you can take advantage of online resources and tools that can do the following:

  • Teach the basics of financial markets and investing.
  • Maximize your income, like a great position size calculator, that decides the estimated amount of currency units to buy or sell.

In investing, the younger you start, the better. If you start early, you’d surely thank your young and smart self 10 years from now.

2.) Millennials don’t invest in health insurance

Health insurance is a good investment for your future, as you have a shield that covers all your costs in the event of any health issues. Remember, health is your greatest asset. Illness can be very expensive, but when you have health insurance, your expenses are covered and you can focus on recovering.

There are now easy payment plans on health insurance, depending on your salary. You’ll be surprised to know that paying your insurance premiums can cost you less than the money you spend on your daily coffee run.

3.) Millennials don’t have an emergency fund  

As a millennial, you’re at the top of your health and age. Hence, you forego saving for an emergency fund. An emergency fund refers to money set aside to cover:

  • Emergency travel, such as when you need to go home because a family member died
  • Home repairs after a natural disaster
  • Sudden job loss

You should have at least three to six months’ worth of your monthly expenses as savings for emergencies. For example, if you spend a total of 500 USD every month to cover living expenses, home loan, etc., 3000 USD should be your emergency fund.

4.) Millennials don’t write a monthly budget

Not writing down a monthly budget is a mistake that can lead you to overspend. When you write your budget down, you can visualize it better and stick to it; hence, you know where and how to allocate your money efficiently. Continue Reading…

Which All-in-one, One-ticket Portfolio Is right for you?

By Dale Roberts, CuttheCrapInvesting

Special to the Financial Independence Hub

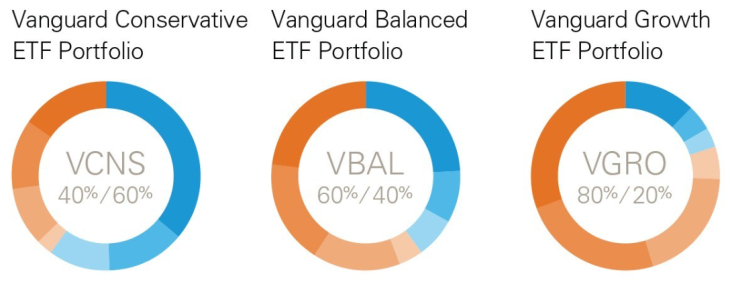
In February 2018 Vanguard Canada changed the investment game in Canada with the launch of complete Balanced Portfolios that you can purchase by entering one ticker symbol. For example, once logged into your discount brokerage account you would enter the symbol VBAL, and press buy to get a complete globally diversified Balanced Portfolio. The Portfolio is 60% Canadian, US and International stocks with 40% of those shock absorbers known as bonds.

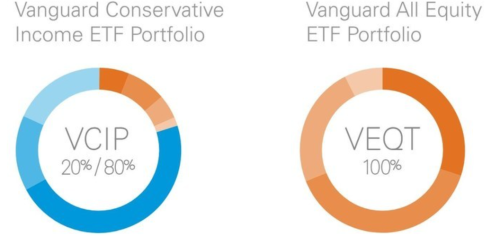
Vanguard offers One-ticket Portfolios at five different risk levels.  With an MER of .22% these portfolios are a game changer. (In the pie charts below, Orange shows equities and blue fixed income percentages). 


iShares has also had One-ticket solutions available for several years. The asset allocation was ‘weird’ and the fees were not that low. considering the low fees on the underlying ETF assets. In response to Vanguard, iShares recently took the scrub brush to the funds, cleaned up the asset allocations and then cut the fees. In fact they undercut Vanguard just slightly with an MER of .20%. Here’s the link to the iShares product page; this will take you to XBAL, their Balanced Portfolio.

And then last week along comes one of the big banks with their own One-ticket offering. Here’s my review at the Hub: BMO keeps it simple with its One-ticket Portfolio Solutions.


The one-ticket solutions are the most cost-effective managed portfolios available in Canada. This should be the final dagger in the heart of the high fee mutual fund industry.

Which One-ticket provider is best?

Let’s call it a draw. The portfolios are equally great. They include the basic and sensible asset allocation building blocks of Canadian, US and International stocks supported by a bond component. All the One-ticket providers use Canadian and foreign bonds to manage the risks.

How to select the right portfolio

Nothing is more important than investing within our risk tolerance level. We could argue it is the most important ‘part of it all.’ The Portfolios do not come with an owner’s manual for when and how to use them. Matching the appropriate portfolio to your risk tolerance level, time horizon and objective is key.

We have to invest within our risk tolerance level; bad things happen when we invest outside of our comfort level – usually permanent losses. We must be comfortable with the percentage and dollar value that the portfolio could decline.

Are you comfortable with a portfolio that could decline by 5% in a major correction, 10%, 20%, 30%, 40% or 50%?

Remember those bonds work like shock absorbers to soften the blow and smooth out the ride during periods when the stock markets tank.  And tank they can; Canadian and US and International markets have declined by some 50% or more twice in the last 20 years. Continue Reading…